
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brightstar Lottery (BRSL), What Is Behind The Fresh Attention?
Brightstar Lottery (NYSE:BRSL) has moved into the travel themed gaming arena after signing a five year exclusive licensing deal with Pan American World Airways to create Pan Am branded omnichannel lottery products.
Recent share price moves tell a different story to the product news. Brightstar Lottery’s stock has retreated, with the 30 day share price return down 7.37% and the year to date share price return down 38.37%. This has contributed to a 1 year total shareholder return decline of 39.46% as investors reassess both growth potential and risk around new initiatives such as the Pan Am partnership.
Scan beyond Brightstar Lottery and see how other gaming and consumer services stocks are positioned for potential rebounds with our hand picked 35 high quality undervalued stocks.
Brightstar Lottery is signing fresh licensing deals while the share price resets lower. Does that recent drop offer a reasonable entry now, or does it still pay to wait for a cheaper ticket?
Most Popular Narrative: 44% Undervalued
Brightstar Lottery last closed at $9.43, while the most widely followed narrative anchors on a fair value estimate of $16.71 using a 13.56% discount rate. That gap raises a clear question about whether the market is underestimating the lottery specialist's earnings power and contract profile.
Regulatory liberalization and successful contract renewals (notably Italy Lotto secured through 2034 and new or extended deals in Missouri, Portugal, and France) are expanding the addressable market and extending Brightstar's average revenue weighted contract life to 7 years, providing long-term revenue stability and enhanced cash flow visibility.
See why 2 investors see Brightstar Lottery as 44% undervalued.
Result: Fair Value of $16.71 (UNDERVALUED)
Still, the narrative could crack if Italy’s much higher renewal spending fails to earn its keep, or if tighter gambling rules start to bite key markets.
Find out about the key risks to this Brightstar Lottery narrative.
Another View On Brightstar Lottery’s Value
The narrative around Brightstar Lottery leans heavily on a $16.71 fair value based on future earnings assumptions. A different lens comes from Simply Wall St’s DCF model, which estimates future cash flow value at $2.30 per share, well below the current $9.43 price. That gap raises a simple question for you: Which risk matters more, execution on growth or the possibility cash flows never fully catch up?
Look into how the SWS DCF model arrives at its fair value.
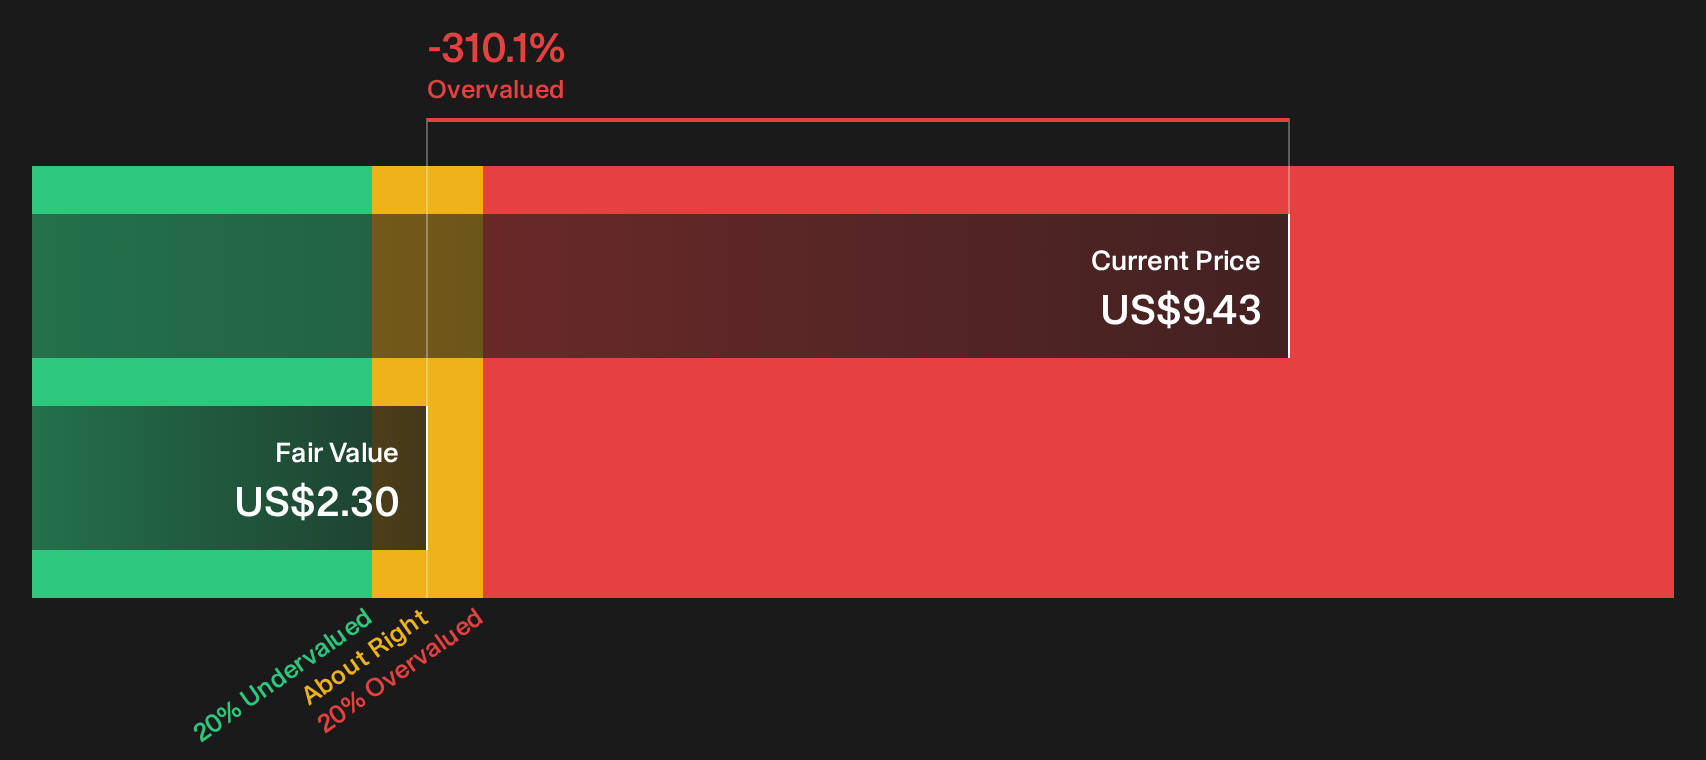
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brightstar Lottery for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Brightstar Lottery’s value and risk profile come through clearly in the data. Consider acting promptly and weighing both sides for yourself using 3 key rewards and 4 important warning signs.
Looking for more Brightstar Lottery investment ideas?
If Brightstar Lottery has your attention, do not stop here. Put a shortlist together now using targeted screeners that surface different kinds of opportunities.
- Chase potential upside in smaller companies that already show financial strength by scanning the 12 elite penny stocks with strong financials.
- Zero in on companies where quality and price line up more cleanly by reviewing the 20 high quality undiscovered gems.
- Prioritize peace of mind and focus on resilience first by filtering for a 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com