
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Analyst Downgrades Might Change The Case For Investing In LCI Industries Stock (LCII)
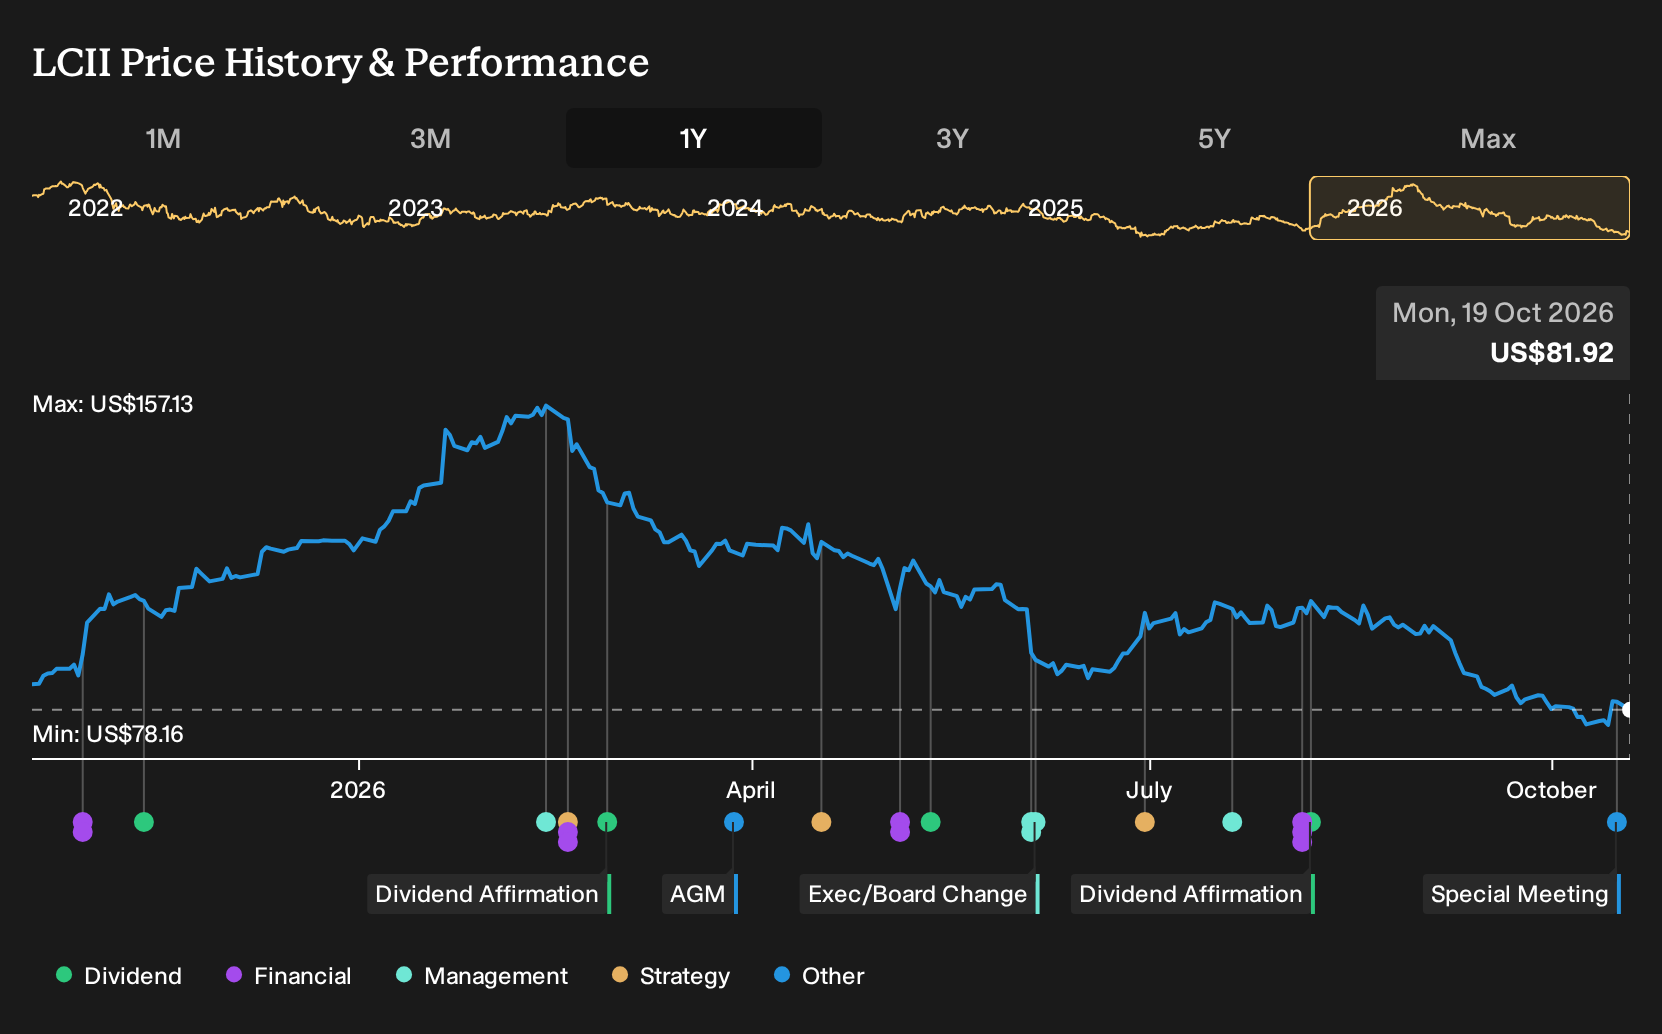
- LCI Industries recently faced a series of analyst downgrades after concerns resurfaced about ongoing cost pressures, RV demand softness and the pace of its margin improvement efforts.
- The reassessment highlights how dependent the investment case still is on cost optimisation, facility consolidation and aftermarket expansion to support earnings beyond the core RV cycle.
- This section now examines how LCI Industries’ investment narrative could be affected by Stifel’s downgrade and related analyst concerns.
Pressure test your reaction to the LCI Industries downgrade by comparing it with a curated set of resilient balance sheet opportunities in our list of solid balance sheet and fundamentals (25 results).
LCI Industries Investment Narrative Recap
To stay invested in LCI Industries, you have to believe the RV downcycle does not swamp the progress in aftermarket, adjacent OEM markets and content per unit. The Stifel downgrade shines a light on that tension but does not change what matters most. In the near term, the key swing factor is how quickly cost optimisation and facility closures translate into steadier margins despite tariff and raw material pressure.
The biggest risk right now remains exposure to a softer North American RV wholesale backdrop and what that means for OEM volumes. Management is leaning on higher margin aftermarket demand and diversification into marine, transportation and housing to cushion that. If RV shipments stay under pressure for longer than expected, that reliance gets tested and earnings could tighten.
The most relevant backdrop to this downgrade is the proposed all stock merger with Patrick Industries. Management has outlined more than US$150m in targeted cost synergies and described a combined profile of roughly US$1b of adjusted EBITDA at a 12.6% margin and about US$508m of free cash flow. That represents a sizable operational swing factor for LCI Industries if integration goes to plan.
For you as a shareholder, this potential combination sits directly on top of the same issues flagged by the downgrade. Integration risk now layers onto an already cyclical RV base, rising tariff and material costs and a balance sheet that carries a high level of debt. Execution on facility consolidation, synergy capture and aftermarket growth will do more to shape the medium term outcome than the rating change itself.
What The LCI Industries Downgrade Assumes About 2029
Analysts building the current LCI Industries story are effectively asking investors to underwrite a slow build in revenue and a modest step up in profits over the next few years, rather than a sharp rebound. Their models factor in revenue growth of 1.7% a year, a lift in profit margins from 5.2% today to 5.9% in three years, and a shift in the earnings mix toward aftermarket and non RV exposure, in addition to the pending Patrick Industries deal.
On earnings specifically, the consensus view places LCI Industries at US$211.3 million of profit today and US$248.6 million by about 2029, an increase of roughly US$37 million. That forecast underpins a price target framework that assumes the stock eventually trades on a 15.8x P/E multiple of those 2029 earnings, compared with about 9.7x at the moment and slightly above the current 15.7x P/E cited for the broader US auto components peer group.
Set those numbers against the downgrade and the pressure points become clearer. The bridge from today to 2029 relies on cost work, facility consolidation and a tilt toward higher margin lines being sufficient to offset a sluggish RV shipment backdrop and rising material costs, while the combined LCI Industries and Patrick Industries entity achieves more than US$150 million of cost savings without running into integration risk.
LCI Industries' narrative projects US$4.2 billion of revenue and US$248.6 million of earnings by 2029. This is based on 1.7% yearly revenue growth and an earnings increase of about US$37 million from US$211.3 million today.
Uncover why LCI Industries' fair value indicates a 46% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate angle on LCI Industries focuses on the Patrick Industries merger as a potential upside swing factor. Before this downgrade, the most optimistic analysts were pencilling in about US$4.6b of 2029 revenue and US$263.2m of earnings. You can treat this as a reference point and then consider how the latest news might push those views higher or lower.
Explore 4 other LCI Industries fair value estimates, including one that suggests as much as 155% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your LCI Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for LCI Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LCI Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond LCI Industries?
If the LCI Industries story has you rethinking concentration risk, it can help to line it up against other businesses with different drivers, balance sheets and income profiles using the Simply Wall St Screener.
- For investors who want potential value paired with quality fundamentals, compare LCI Industries against a curated set of 35 high quality undervalued stocks that may offer a different mix of risk and return.
- If capital protection is your priority, contrast this RV exposed group with 32 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- To widen your opportunity set beyond well known tickers, set LCI Industries alongside 20 high quality undiscovered gems that combine solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com