
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Flowers Foods (FLO) Could Be 19% Below Fair Value As Bakery Sales Slip
Recent commentary on Flowers Foods (FLO) highlights a mixed picture, with net sales declining 4% year over year as bakery volumes soften and competition tightens, while the Wonder cake line gains unit and dollar share.
At a share price of US$5.98, Flowers Foods has seen its 90-day share price return fall 29.65% and its 1-year total shareholder return decline 48.83%. This points to fading momentum even as management focuses on Wonder cake growth and adjusts to weaker bakery volumes.
Scan beyond Flowers Foods and compare these bakery headwinds with other packaged food producers in our curated list of list of solid balance sheet and fundamentals (25 results).
Flowers Foods now trades well below both analyst targets and some intrinsic value estimates after a steep share price slide. Is that a reasonable discount for bakery headwinds, or an overcorrection that the valuation work exposes?
Most Popular Narrative: 19% Undervalued
On the most followed view, Flowers Foods screens as undervalued, with a narrative fair value of $7.40 against a last close of $5.98. This puts the recent selloff and bakery softness in tension with a longer term reset story.
The main thing that has to go right is Flowers Foods successfully shifting its portfolio and marketing toward Better For You and snacking platforms while managing promotions, costs and leverage so that earnings pressure does not outweigh mix and efficiency gains.
Current valuation levels imply that the share price does not fully reflect this narrative, which views Flowers Foods as undervalued and suggests that progress on portfolio reset, Better For You initiatives and balance sheet repair could be rewarded.
See why 31 investors see Flowers Foods as 19% undervalued.
Result: Fair Value of $7.40 (UNDERVALUED)
Still, the Flowers Foods story can break if traditional loaf weakness deepens or if oil linked costs such as diesel and packaging squeeze already thin margins.
Find out about the key risks to this Flowers Foods narrative.
Another View: Flowers Foods On Earnings Multiples
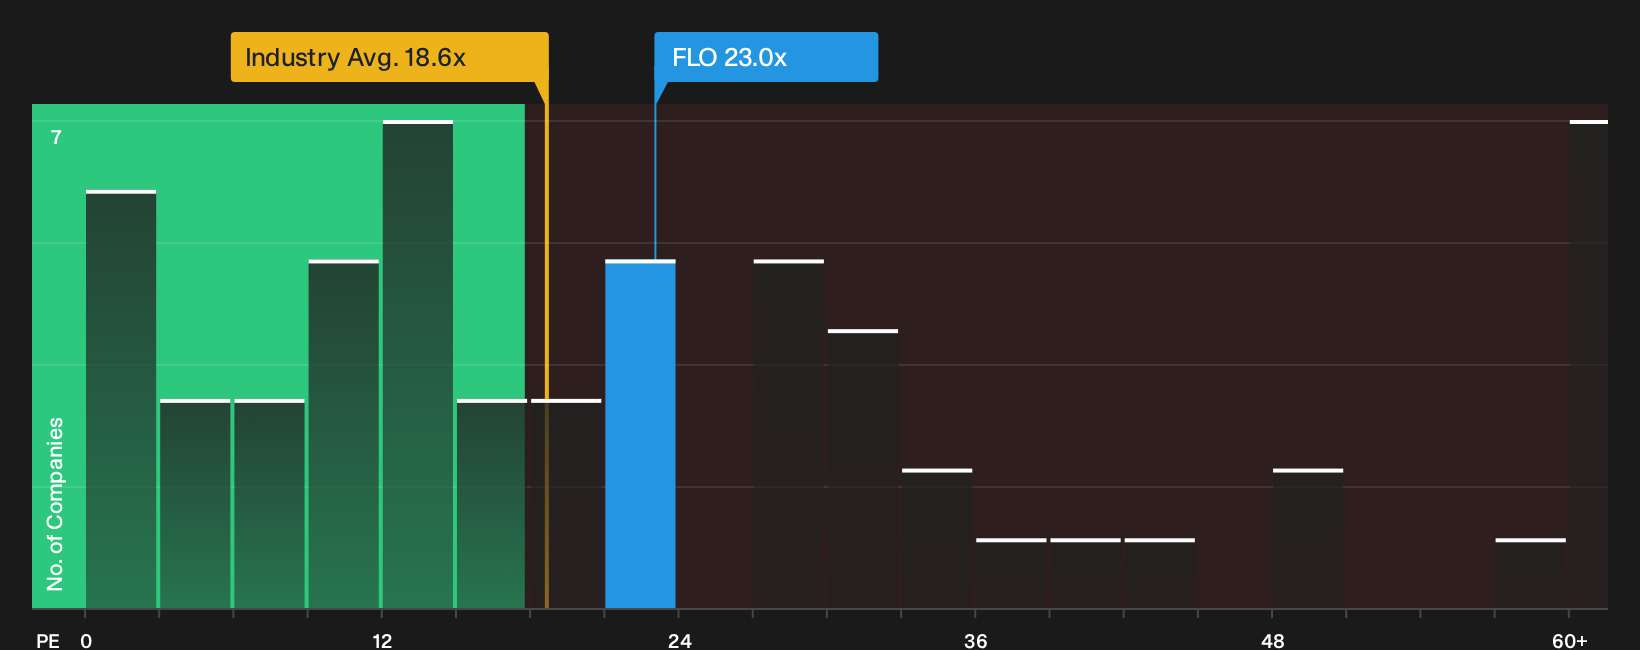
There is a very different message when Flowers Foods is viewed through its P/E. The stock trades at about 23x earnings, compared with 21.3x for peers and a fair ratio of 17x. That richer multiple hints at less margin for error if the bakery reset takes longer or proves bumpier than expected.
For a clearer sense of how that gap lines up against history and peers, take a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around Flowers Foods leaves you undecided, move quickly from headline takes to your own scorecard using the underlying data and narrative. To weigh both sides of the story in one place, start with the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Flowers Foods?
Do not stop your research with Flowers Foods when the broader market is full of other potential setups that could fit your risk and income goals.
- Boost your hunt for deep value by scanning companies that line up with 35 high quality undervalued stocks and see which ones deserve a closer look.
- Strengthen your income playbook by reviewing the 8 dividend fortresses that might match your need for yield with fundamental support.
- Dial down portfolio stress by filtering for 32 resilient stocks with low risk scores that keep financial risk scores in focus instead of chasing story alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com