
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Altria Group (MO) Could Be 6% Overvalued Following Its Credit Facility Extension
Why Altria’s Latest Credit Extension Matters
Altria Group (MO) just secured an extra year on its US$3.0b senior unsecured 5 year revolving credit facility, extending the credit agreement’s expiration from October 24, 2029 to October 24, 2030.
The revised timeline, agreed with JPMorgan Chase, Citibank and a syndicate of lenders, keeps all other terms intact. For investors tracking Altria’s balance sheet flexibility, this extension is a fresh data point on available liquidity.
Recent trading reflects that investors have been rewarding Altria Group’s resilience, with a year to date share price return of 29.28% and a 1 year total shareholder return of 22.83% that adds to already substantial 3 and 5 year total shareholder returns.
Scan how Altria Group compares on balance sheet strength and payout resilience against a curated 8 dividend fortresses.
Altria Group trades at a steep intrinsic value discount, even as the share price has climbed and now sits above analyst targets. Is the market being too cautious, or is it seeing something the valuation flags miss?
Most Popular Narrative: 6% Overvalued
Altria Group closed at $74.09 compared with a narrative fair value of $70 that uses an 8.06% discount rate. This frames the current price as slightly ahead of that model and places more emphasis on execution in smoke free products and capital returns.
Expansion of Altria Group's on! and on! PLUS nicotine pouch platform, with the category now close to 60% of oral tobacco volume and year to date shipment volume for on! up 5.1%, positions smoke free products to contribute more meaningfully to revenue and earnings. Additional FDA marketing approvals for Helix nicotine pouches, bringing the total number of authorized pouch products to 30, create scope for broader distribution and future line extensions that can support oral tobacco revenue growth.
See why 261 investors see Altria Group as 6% overvalued.
Result: Fair Value of $70 (OVERVALUED)
Still, the current Altria Group story can crack quickly if discount brands continue to pull share from Marlboro or if new legal and regulatory investigations escalate into higher costs.
Find out about the key risks to this Altria Group narrative.
Another View: What Multiples Say About Altria Group
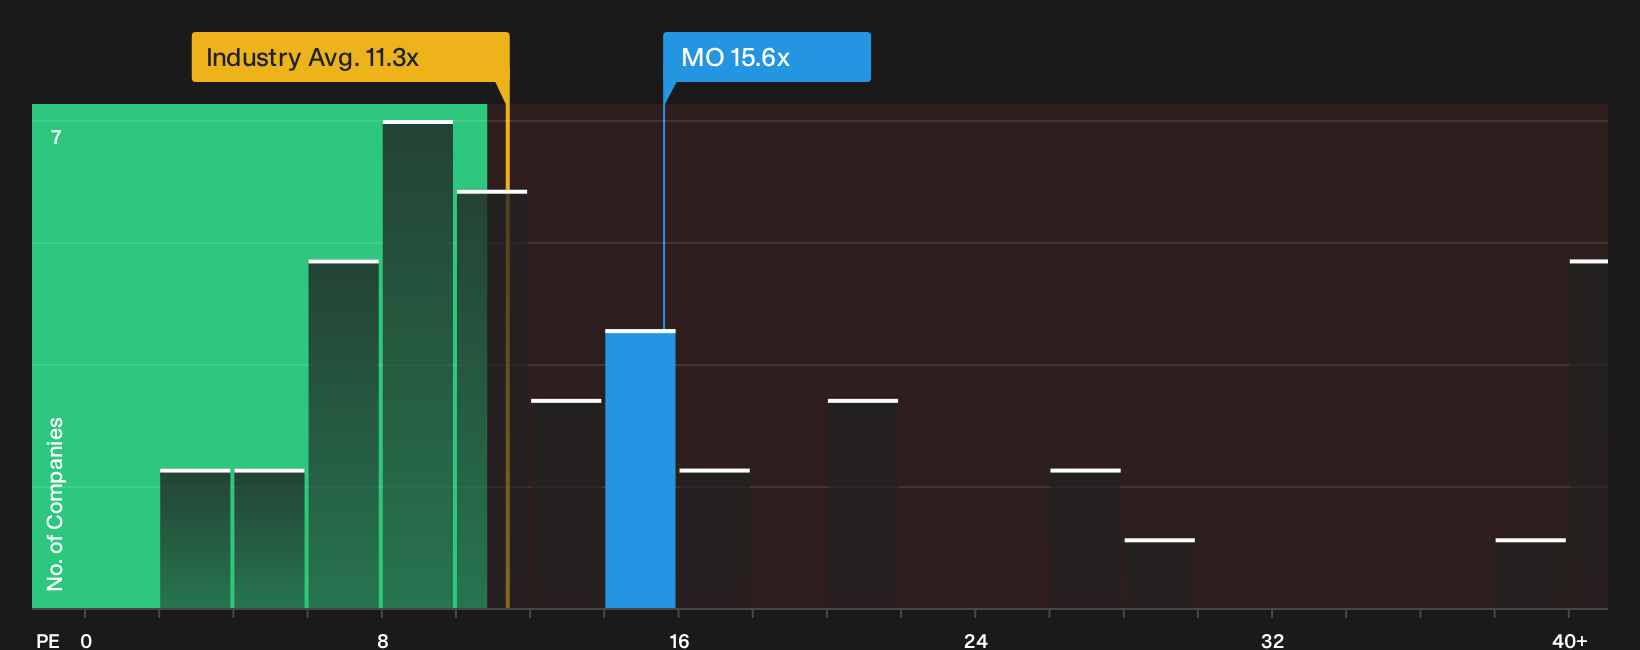
Analyst narratives frame Altria Group as slightly overvalued against a $70 fair value, yet the current P/E of 15.6x paints a different picture. The stock trades well below a peer average of 30.1x and under a fair ratio of 20.6x, which signals that sentiment risk and upside potential are pulling in opposite directions. Which one do you think wins out over time?
For a closer look at how that P/E gap stacks up against both peers and the fair ratio, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Altria Group can create noise, so use that tension as a prompt to move quickly, review the data, and weigh both sides for yourself with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Altria Group?
If Altria Group has you thinking more broadly about your portfolio, do not stop here. Use the tools available and give yourself more high quality options.
- Target quality at a discount by scanning a curated pool of companies that combine strong balance sheets with appealing valuations through the 35 high quality undervalued stocks.
- Strengthen your income stream by comparing reliable high yield payers side by side using the focused 8 dividend fortresses.
- Protect your capital first by filtering for businesses with resilient financial profiles through the dedicated 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com