
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OMV Petrom Stock And 2 Energy Shares With Oil Exposure
Oil is back on the front page, with Brent crude above $111 and the IEA hinting that tight supply and higher input costs could linger well into 2027. That kind of backdrop can reward some global integrated oil and gas producers while leaving others exposed to sharper swings. This article breaks down three stocks from the screener that appear especially sensitive to the current news flow.
The three stocks below are just a starting sample from this theme, and the full screen surfaced 18 more global integrated oil and gas producers with equally compelling narratives that are not covered here. To go deeper into the opportunity set, head straight into the Global Integrated Oil & Gas Producers screener to identify, analyze, and focus on the ideas that best fit your risk profile.
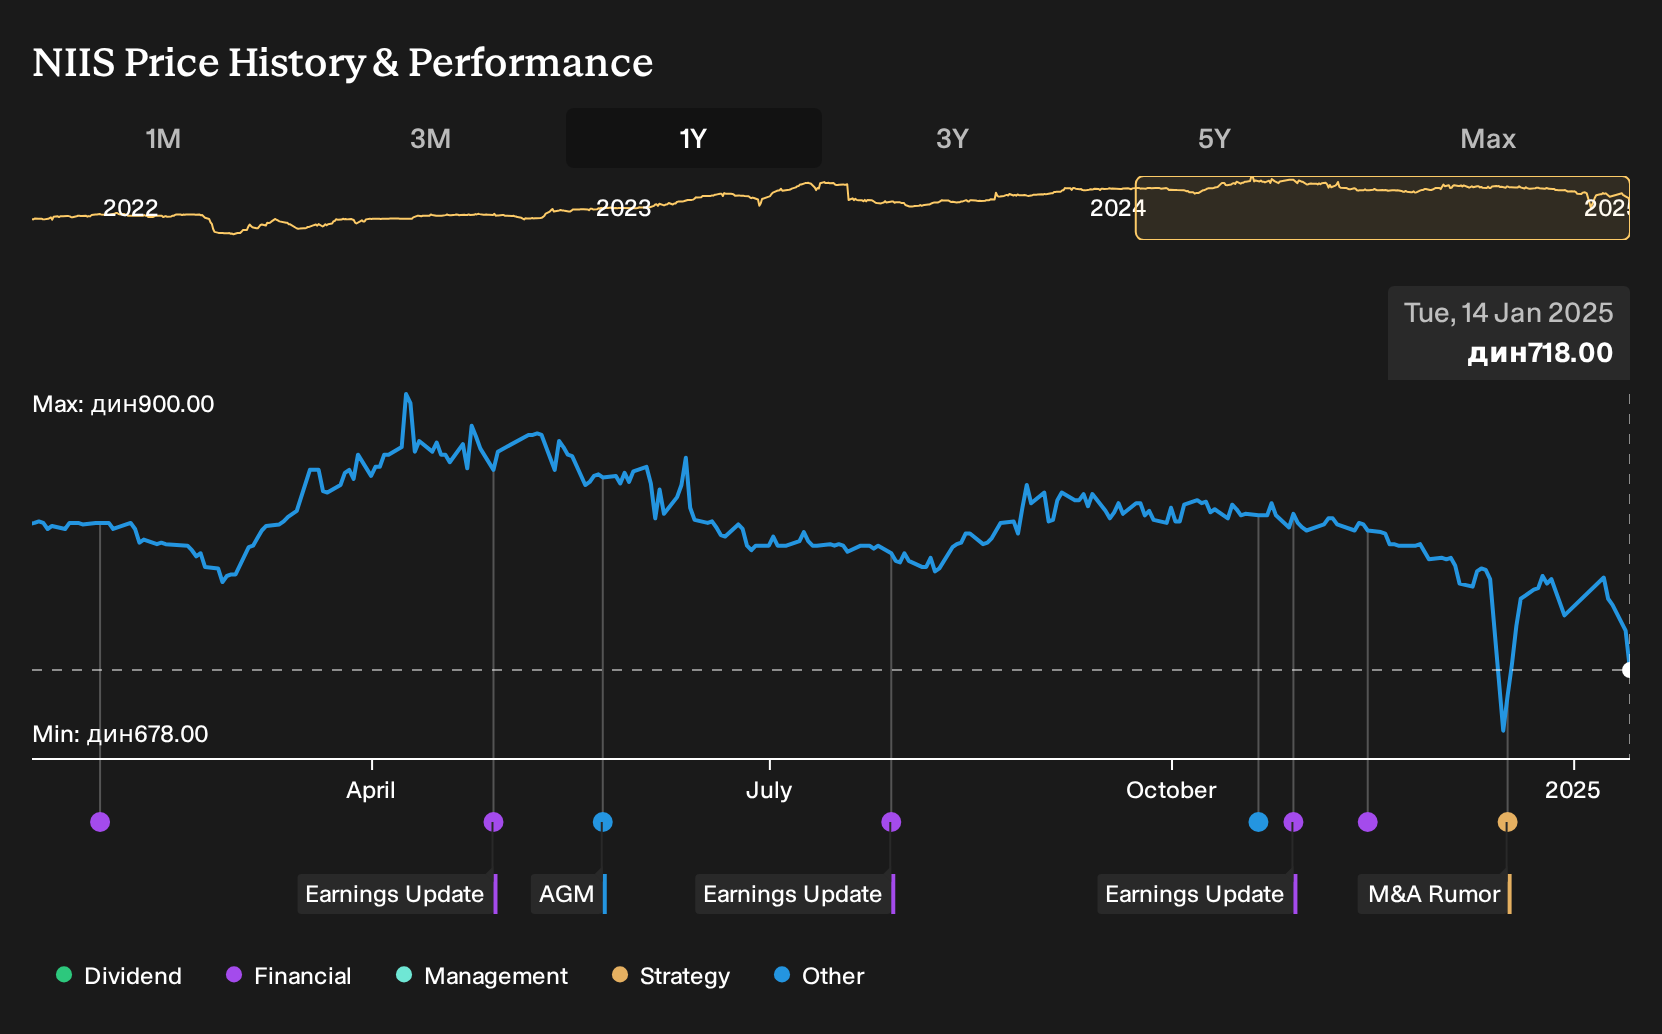
Naftna Industrija Srbije a.d (BELEX:NIIS)
Overview: Naftna Industrija Srbije a.d is an integrated Serbian oil and gas group spanning exploration, production, refining, fuel retail and power.
Market Cap: RSD117.1b
Naftna Industrija Srbije a.d gives you direct exposure to the Global Integrated Oil & Gas Producers theme through upstream wells, refining assets and a regional fuel station network that all sit close to the current crude and diesel story. Recent profitability recovery and a high headline yield make the set up appealing, depending on how one unseen pressure plays out.
That unseen pressure is exactly what you need to size, so head to the 1 key reward and 3 important warning signs (1 is major!) for the full risk and reward picture hiding behind the yield.
OMV Petrom (BVB:SNP)
Overview: OMV Petrom is an integrated Romanian energy group that explores for and produces oil and gas, refines fuels and sells power.
Operations: OMV Petrom generates most revenue from Refining and Marketing at RON27.7b, with Exploration and Production contributing RON9.9b and Gas and Power RON13.7b.
Market Cap: RON83.6b
OMV Petrom plugs straight into the Global Integrated Oil & Gas Producers theme because its upstream barrels, downstream fuels and power platform all tie directly into the same crude price story that now dominates headlines.
"Progress at the Neptun Deep Black Sea gas project remains on track and is expected to materially increase OMV Petrom’s production volumes, reduce unit production costs and lower E&P cash flow breakeven towards about US$30 per barrel of oil equivalent."
The real swing factor is what happens to OMV Petrom’s cash generation if a single assumption about future profitability fails to hold.
If that assumption is wrong or accelerates, the full narrative for OMV Petrom outlines how OMV Petrom’s production mix, capex plans and risk points could still reshape the story.

Yancoal Australia (ASX:YAL)
Overview: Yancoal Australia is a pure-play producer and marketer of metallurgical and thermal coal serving power and steel customers across Asia and Europe.
Operations: Most revenue comes from New South Wales coal mining at A$5.7b, with Queensland mines adding A$592m and smaller unallocated income streams.
Market Cap: A$8.3b
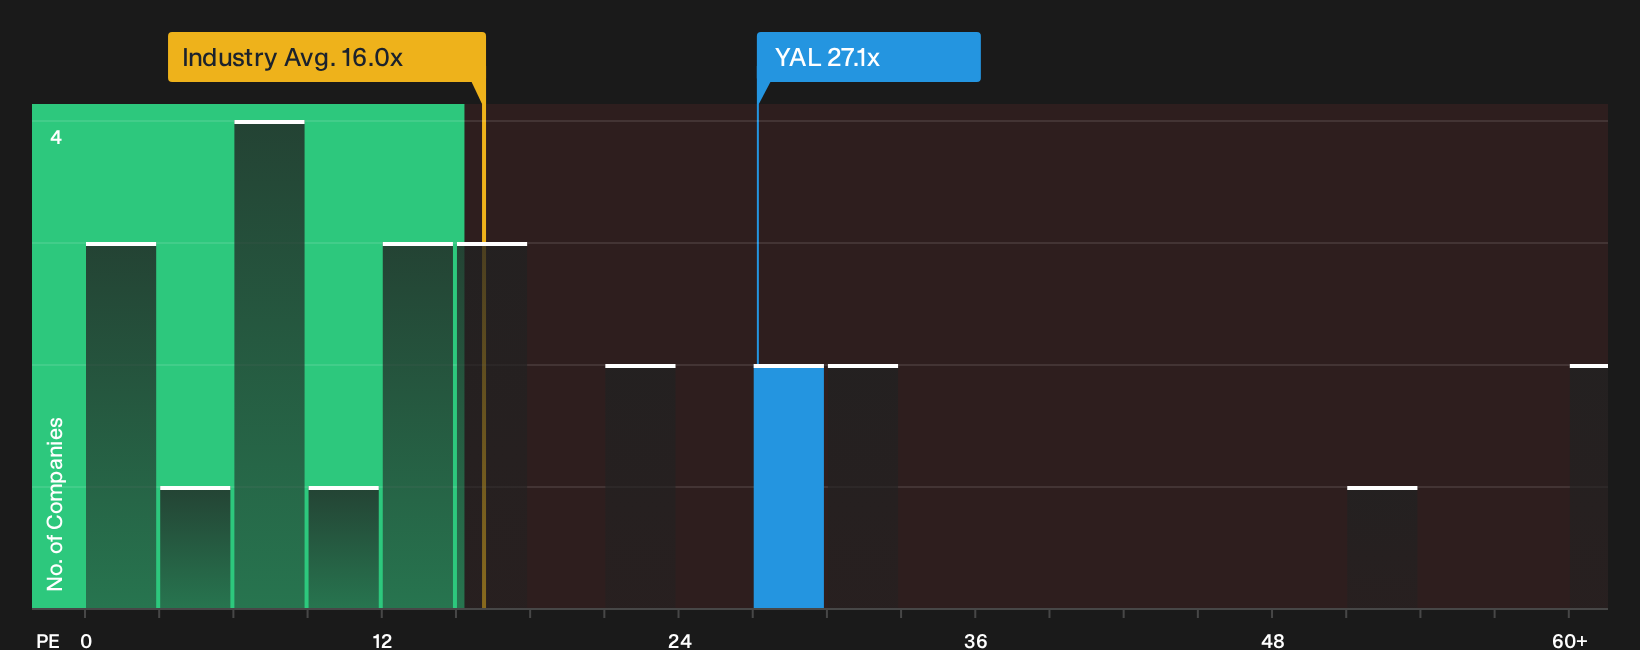
Yancoal Australia provides coal exposure within an oil and gas oriented screen, with A$3,024m revenue and earnings paired with 4.7% margins and a 27.1x P/E. Investors receive exposure to fossil fuel pricing through long-life Australian assets and major Asian offtake, while capital structure and one unresolved board and funding risk could influence how much coal price strength is reflected in equity returns.
That unresolved capital structure angle is exactly where a lot of the story sits. Go straight to the 2 key rewards and 2 important warning signs for how Yancoal Australia’s coal leverage really plays out.
Seeking Alternatives Before Everyone Else
Fresh themes are building momentum while attention stays glued to oil. Spot potential breakouts and quality ideas still flying under the radar for now, then act now.
- Target income that does more of the heavy lifting for your portfolio with a curated set of resilient payers inside the 223 dividend fortresses.
- Chase early-stage potential where tiny movers can become portfolio drivers by scanning the hand-picked opportunities inside the 131 elite penny stocks with strong financials.
- Position ahead of the next compute breakthrough by zeroing in on companies powering the hardware and plumbing behind AI through the 55 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com