
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Ten Year VMware Deal Require Action From Broadcom (AVGO) Investors?
- Broadcom signed a 10 year VMware Cloud Foundation agreement with NTT Docomo to support private cloud, AI workloads, and future 6G ready digital services on a unified infrastructure platform.
- The deal ties Broadcom’s VMware stack directly into a large carrier’s next generation cloud and AI plans, reinforcing how software, security and AI infrastructure now intersect in its operating model.
- We will look at how Broadcom’s investment narrative is shaped by this long term NTT Docomo VMware cloud and AI agreement.
Broadcom Investment Narrative Recap
To own Broadcom, you need to believe its AI centric chip and VMware software engines can offset pressure from lower margin XPU products and complex financing structures. The key near term swing factor is whether hyperscaler AI demand keeps translating into firm orders that support the guided gross margin of 73% in Q4 2026 without further compression.
The biggest risk right now is the AI XPV financing exposure of about US$29b in residual value guarantees, alongside investor sensitivity to any cooling in AI bookings or guidance. The NTT Docomo deal and broader AI push help the operating story, but do not remove those funding and margin questions.
The VMware HyperArmor launch looks especially relevant next to the NTT Docomo agreement, because both sit directly on VMware Cloud Foundation and speak to how Broadcom wants AI ready infrastructure to be secured at the hypervisor, network, and app layers. HyperArmor targets two concrete pain points: stolen root credentials and unpatched ESX vulnerabilities, with host level virtual patching and integrated MFA.
For you as an investor, this matters because it links VMware security depth to the same AI build out that drives Broadcom’s XPU and Ethernet catalysts. Strong demand for AI semis and networking is one side of the story. Keeping those clusters secure without downtime through products like HyperArmor is another execution test that can influence adoption of VMware based private AI clouds.
Broadcom's outlook projects US$317.5b in revenue and US$155.8b in earnings by 2029. This is based on analysts assuming 52.7% yearly revenue growth and an increase in earnings of about US$117.5b from US$38.3b today.
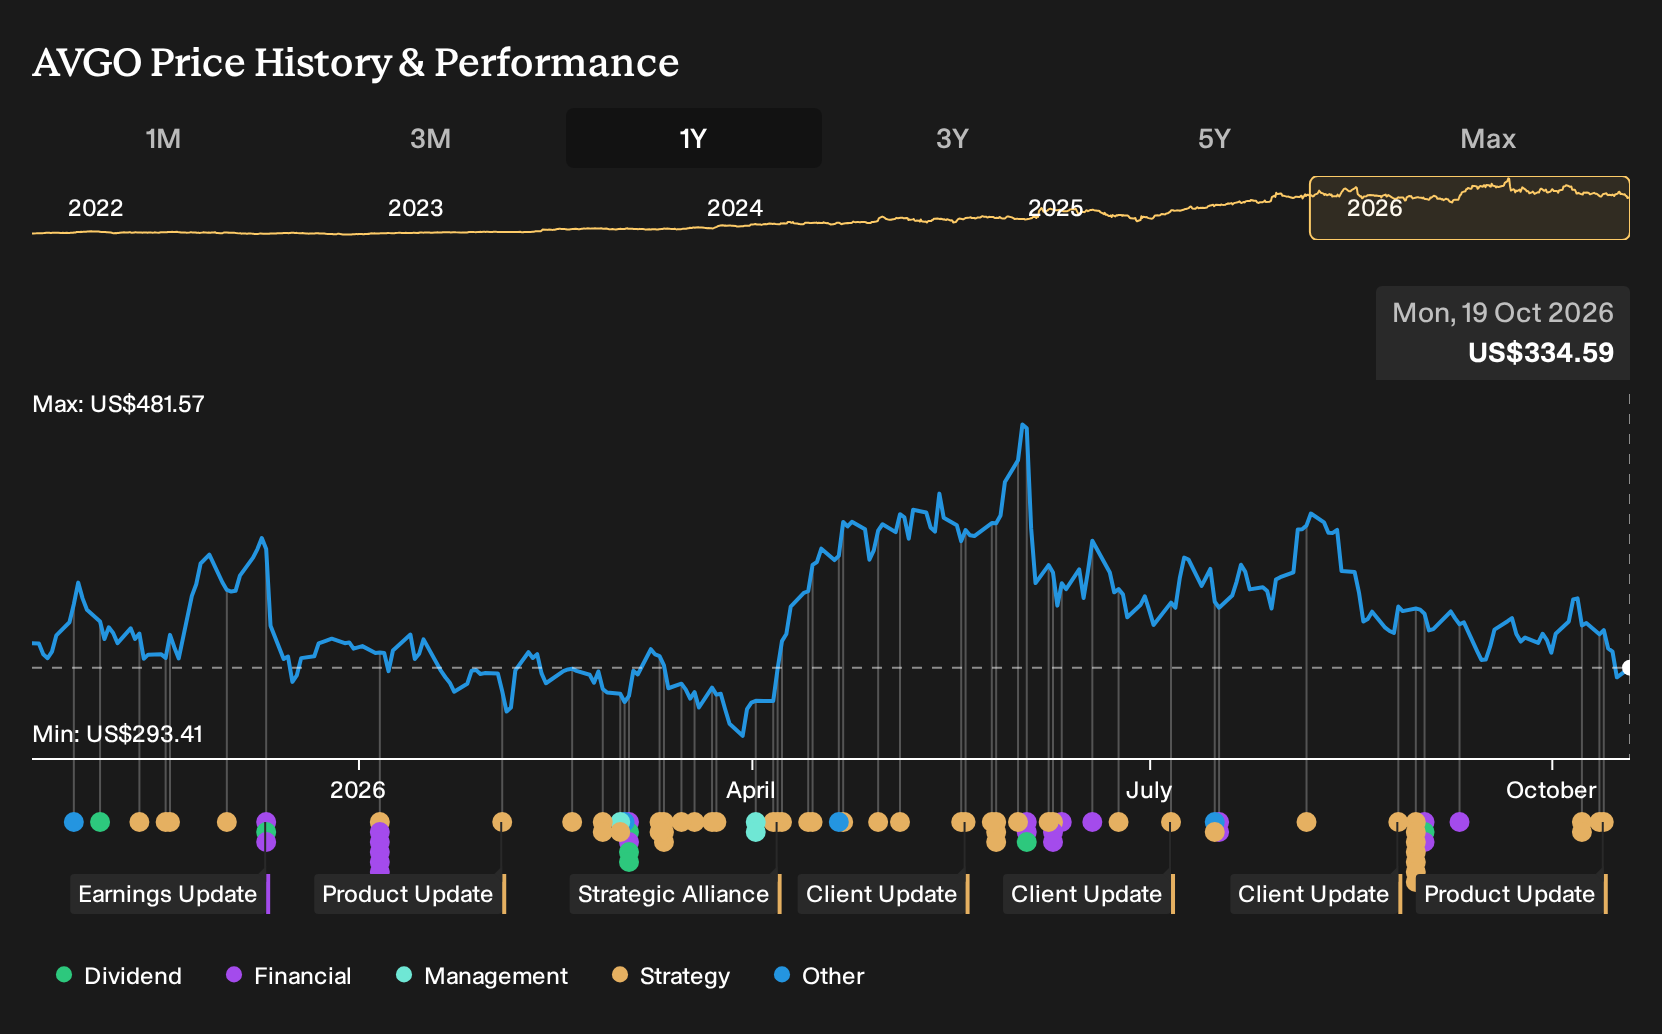
Uncover why Broadcom's fair value indicates a 59% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Broadcom analysts base their case on the large AI-focused backlog and customer pipeline, not on security products like HyperArmor. They were already estimating revenue of US$394.9b and earnings of US$218.4b by 2029. You can treat those pre-news forecasts as one extreme scenario that may change as this VMware and NTT Docomo story develops.
Explore 18 other Broadcom fair value estimates, including one that suggests as much as 95% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Broadcom research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Broadcom. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Broadcom's overall financial health at a glance.
Looking For More Ideas Beyond Broadcom?
If you want to balance your view on Broadcom with a wider watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit the kind of profile you care about most.
- For investors focused on quality at a reasonable entry point, scan a curated 35 high quality undervalued stocks and see which businesses currently trade below their estimated worth.
- If resilience matters more than excitement, filter for 32 resilient stocks with low risk scores to find companies with sturdier fundamentals and lower overall risk scores.
- When income is a priority, use the yield focused 8 dividend fortresses to spot potential candidates offering 5%+ payouts backed by stronger balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com