
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Knight Swift Transportation Holdings (KNX) Nears Earnings, Is The Undervalued Case Still Convincing?
Knight-Swift Transportation Holdings (KNX) heads into Wednesday afternoon’s earnings release with the market expecting 12.7% year-on-year revenue growth, compared with a 2.7% rise in the same quarter last year.
The share price tells a mixed story. Knight-Swift Transportation Holdings is down 17.6% on a 90-day share price return and 5.2% over the past month, yet still shows a 21.0% year-to-date share price gain and a 34.5% total shareholder return over the last year. This suggests earlier optimism is being tested as investors reassess earnings risk heading into this update.
Scan how Knight-Swift Transportation fits alongside other freight and logistics plays by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
The question now is whether Knight-Swift Transportation’s recent pullback reflects a real reset in the freight business or just investors cooling on the story, and how that squares with where the shares trade today.
Most Popular Narrative: 25.7% Undervalued
On the most followed view, Knight-Swift Transportation Holdings screens as undervalued, with a fair value estimate of $85.10 against a last close of $63.21. That gap is tied directly to how freight mix, costs and capital structure interact over time.
Diversification into LTL and Intermodal is starting to reshape the earnings mix, with LTL delivering adjusted operating ratio improvement to 92.1% despite a small revenue decline and Intermodal growing revenue almost 35% with a 470 bps operating ratio gain in Q2 2026. This gives Knight-Swift Transportation Holdings multiple avenues to grow segment revenue and consolidated operating income beyond one way truckload cycles.
See why 2 investors see Knight-Swift Transportation Holdings as 26% undervalued.
Result: Fair Value of $85.10 (UNDERVALUED)
Still, this hinges on tricky execution, from integrating the enlarged LTL footprint without further cost drag to managing higher insurance and third party logistics expenses.
Find out about the key risks to this Knight-Swift Transportation Holdings narrative.
Another View On Knight-Swift Transportation’s Valuation
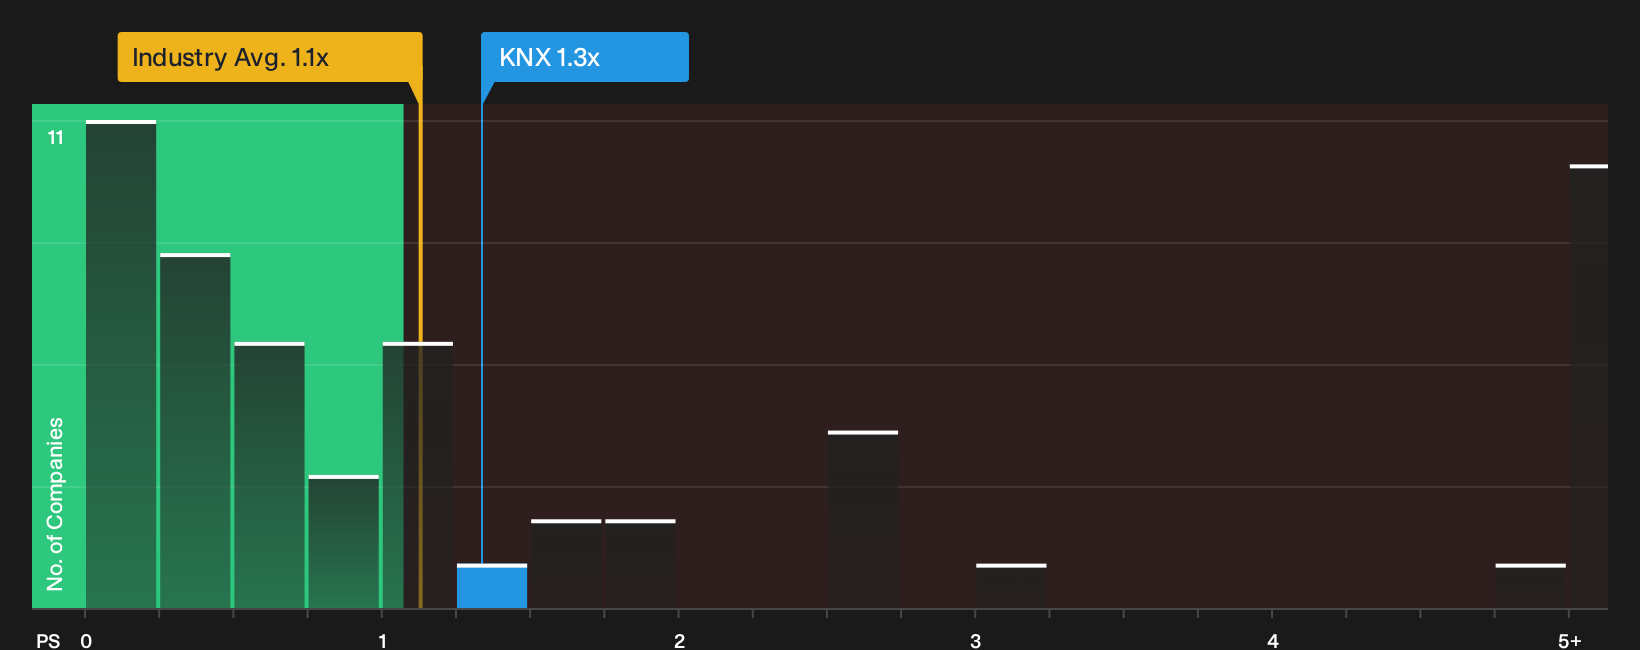
The first take leans on future earnings power and analyst targets. A different lens looks at what investors are already paying for Knight-Swift Transportation through its P/S ratio of 1.3x. That level is higher than the US Transportation industry at 1.2x, yet matches the 1.3x fair ratio estimate. For readers, this points to a stock that screens as relatively cheaper than peers but closer to fair on this single metric, which raises a simple question: How much weight should you put on a cash flow heavy story when the revenue multiple already assumes a fair outcome?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment around Knight-Swift Transportation Holdings leaves you undecided, move quickly to review the underlying numbers, read through the competing narratives, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Knight-Swift Transportation?
If Knight-Swift Transportation Holdings leaves you on the fence, do not stop here. Broader opportunities often emerge when you compare quality, income, and risk side by side.
- Target steadier portfolio behavior by reviewing a 32 resilient stocks with low risk scores that focuses on companies with more resilient profiles when volatility picks up.
- Hunt for mispriced quality by scanning a 35 high quality undervalued stocks that highlights businesses where fundamentals and current pricing look out of sync.
- Build a cash flow cushion by checking out a 8 dividend fortresses that focuses on higher yielding payouts supported by underlying earnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com