
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Price Discipline Change The Bull Case For Packaging Corporation of America (PKG)?
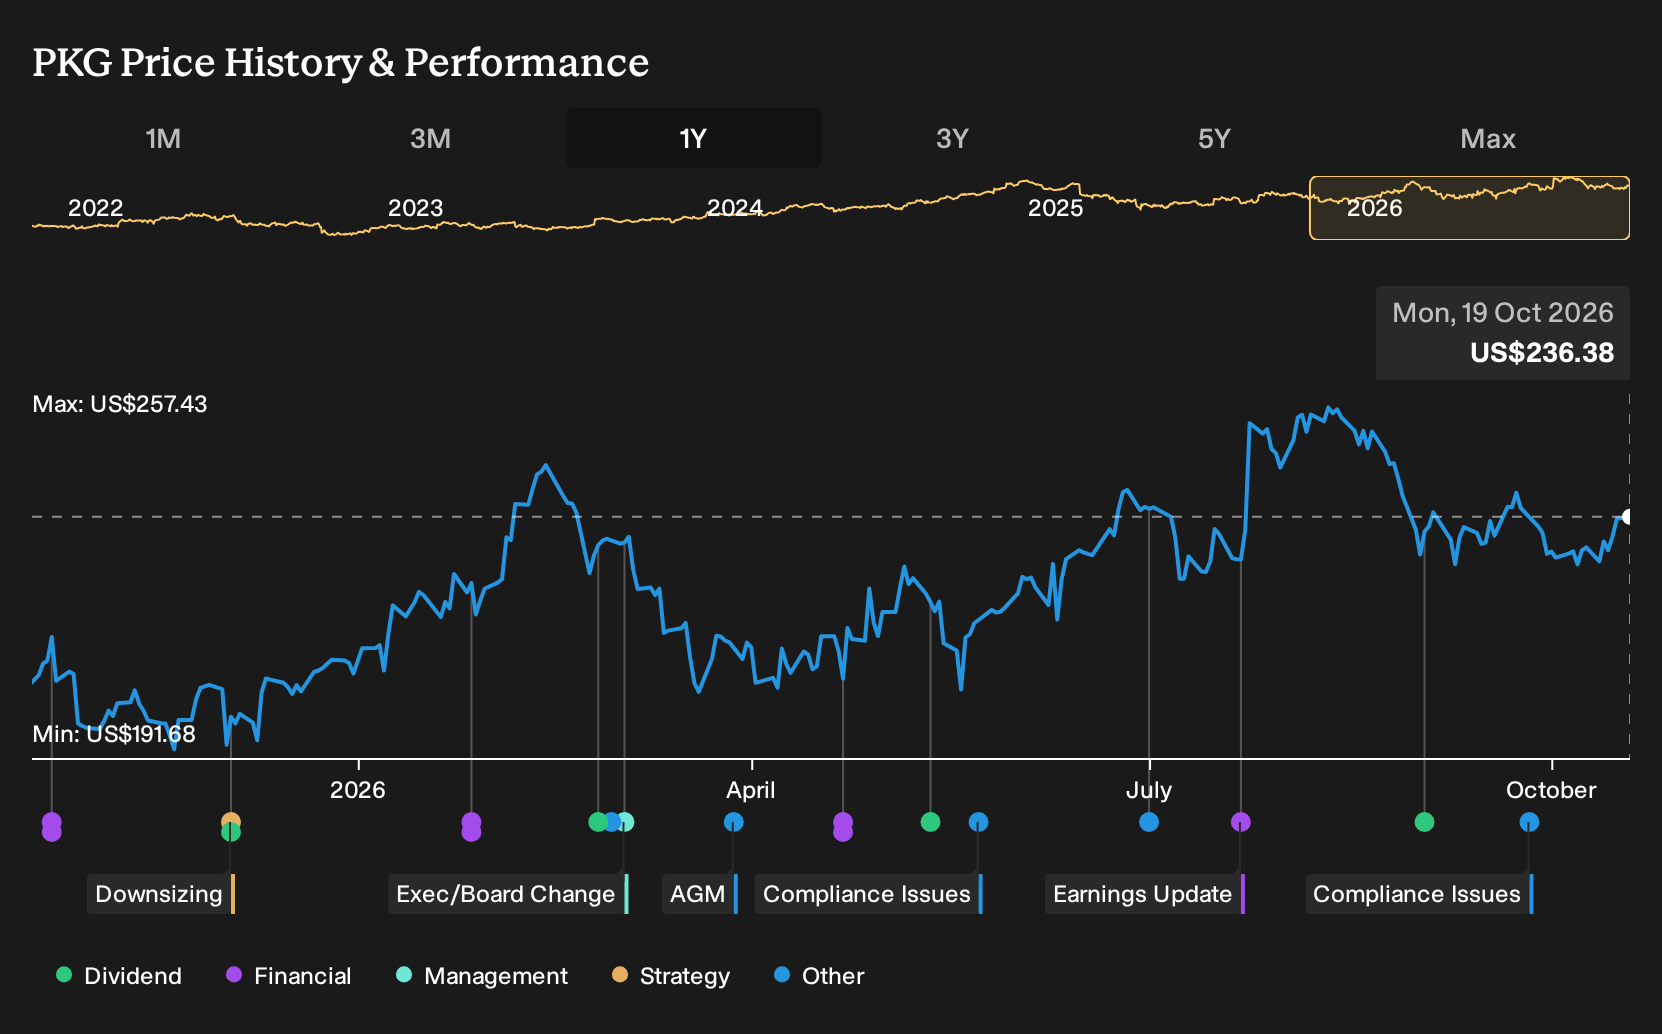
- Packaging Corporation of America led a third round of containerboard price increases in 2026, announcing a US$140 per ton hike that fed into substantial September pricing, while October levels held steady across North America after this earlier reset.
- The chief executive emphasized a willingness to accept some customer losses to preserve pricing, which highlights a focus on margin resilience over volume growth as these containerboard moves flow into fourth quarter financials.
- We will examine how Packaging Corporation of America's firm containerboard pricing stance influences the existing investment narrative around tight system operations.
Scan how Packaging Corporation of America's pricing resolve compares with peers facing the same supply tightness by zeroing in on the hand-picked list of solid balance sheet and fundamentals (25 results).
Packaging Corporation of America Investment Narrative Recap
For Packaging Corporation of America, the core belief is that a tight containerboard system and heavy mill investment can support resilient earnings while cost inflation and debt are managed. The recent US$140 per ton increase and flat October prices keep that thesis intact in the near term. The key short term swing factor remains how quickly these higher board prices translate into box pricing.
The biggest operational risk still sits with demand and input costs. A weaker industrial cycle or sustained pressure from recycled fiber, freight and energy could keep margins closer to the current 7.2% net level. Management’s willingness to risk some volume for price discipline could either cushion profitability or expose earnings if demand softens.
There were no new company specific announcements tied directly to this October pricing outcome, which makes the July containerboard hike itself the key reference point. That US$140 per ton move, on top of earlier 2026 actions, is already baked into the current setup. Your focus now is whether box customers absorb it cleanly or push back.
Seen alongside prior commentary on tight mill utilization and ongoing capex of about US$840 million to US$870 million in 2026, the July action frames the near term story. Execution risk is practical. Keep an eye on shipment trends, packaging segment margins that previously compressed from 22.6% EBITDA margin to 21.1%, and any sign that customers successfully claw back pricing.
Packaging Corporation of America Consensus Setup
Packaging Corporation of America sits in front of a fairly punchy analyst blueprint. The current earnings base is about US$687.4 million, while consensus points to profits of roughly US$1.6 billion by 2029. That change represents an earnings increase of about US$912.6 million from earnings today if the analyst path plays out as modeled.
On the top line, the same group is working with annual revenue growth of 5.8% and a 2029 revenue figure of roughly US$11.3 billion. Put together, the narrative assumes Packaging Corporation of America lifts revenue to US$11.3 billion and earnings to US$1.6 billion by 2029, with profit margins moving from 7.2% today to 14.1% over the next three years as the tight system, capex program and pricing reset filter through the business.
Uncover why Packaging Corporation of America's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some bullish analysts focus on a different catalyst for Packaging Corporation of America. They lean on the idea that tight supply plus heavy capex could support stronger long term pricing than consensus assumes. Before this pricing news, the most optimistic forecasts were for about US$11.9b of 2029 revenue and US$1.8b of earnings. Those projections have not yet absorbed the latest containerboard moves, so you should expect that views may shift. Use this spread in expectations as a reminder that smart people can disagree, and treat it as an invitation to explore several scenarios for yourself.
Explore 2 other Packaging Corporation of America fair value estimates, including one that suggests as much as 114% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Packaging Corporation of America research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Packaging Corporation of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Packaging Corporation of America's overall financial health at a glance.
Looking For More Investment Ideas Beyond Packaging Corporation of America?
If the setup around Packaging Corporation of America has sharpened your thinking, use that same framework to scan a wider opportunity set. A focused screener helps you compare balance sheet strength, income potential and valuation in a structured way rather than relying on headlines.
- For investors who want potential upside without sacrificing financial resilience, start with a curated 20 high quality undiscovered gems that already clear quality and fundamentals checks.
- If capital preservation ranks high on your list, narrow the field to companies that score well on stability metrics using a 32 resilient stocks with low risk scores tailored to resilience.
- Income oriented investors can focus on cash returns by reviewing a 8 dividend fortresses that screens for higher yielding businesses with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com