
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Simpson Manufacturing (SSD) Earnings Miss Risk
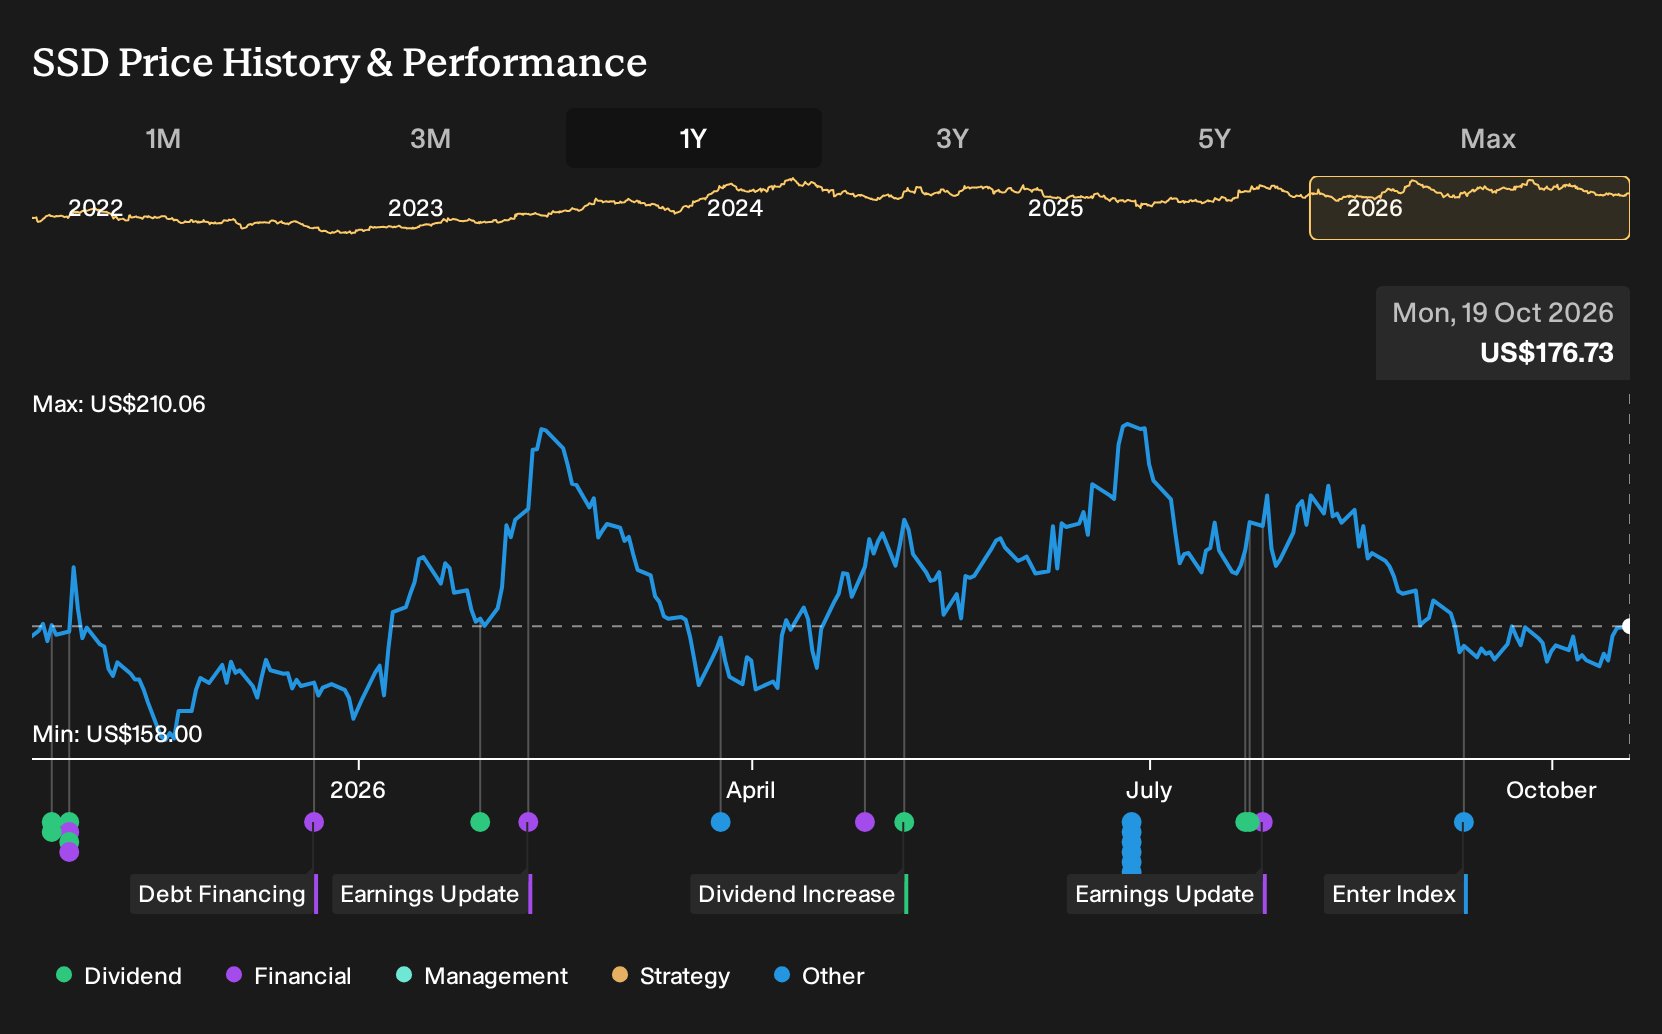
- Simpson Manufacturing is expected to report Q3 2026 earnings that are lower than the prior year, even though revenue forecasts point to a slight uptick.
- This combination of softer profit expectations and only modest top line progress raises questions about cost pressure, product mix and pricing power heading into the print.
- We will look at how Simpson Manufacturing's investment narrative is tested by the prospect of a year over year earnings decline.
Scan how other construction and industrial suppliers are priced for earnings risk by running a curated screen of list of solid balance sheet and fundamentals (25 results) alongside Simpson Manufacturing's setup this quarter.
Simpson Manufacturing Investment Narrative Recap
To own Simpson Manufacturing, you need to believe the business can convert code driven demand for structural connectors and fasteners into steady earnings, even when construction volumes are soft. The Q3 setup, with earnings expected to decline while revenue edges higher, tests how much pricing, mix and cost control can realistically carry that story.
The near term swing factor is whether higher value engineered products and component manufacturing can offset any margin pressure from weaker volumes or sharper competition in fasteners. The key risk is a deeper or more prolonged slowdown in construction activity, which could keep volumes subdued and make cost inflation harder to absorb.
The upcoming Q3 2026 earnings release on 26 October is the operational event that ties this all together. Expectations now point to a year over year earnings decline for Simpson Manufacturing alongside slightly higher revenue, and the latest estimates carry a negative Earnings ESP of 0.85%, which makes an upside surprise less likely on current numbers.
That setup matters because Simpson Manufacturing has beaten consensus EPS for four straight quarters. A weaker print this time would not automatically change the longer term story around building code driven demand, automation or the Gallatin fastener facility. However, it would sharpen investor focus on execution in higher margin segments and on how resilient profitability really is when top line growth remains modest.
What The Current Consensus Implies For Simpson Manufacturing
Simpson Manufacturing's narrative projects US$2.7b revenue and US$433.9m earnings by 2029. That profile assumes 3.3% yearly revenue growth and an earnings increase of about US$55m from US$378.9m today.
Uncover why Simpson Manufacturing's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community span roughly US$73.5 to US$219 for Simpson Manufacturing, so you are seeing retail opinions that pull in very different directions. That spread sits against fresh earnings risk, where softer Q3 expectations could pressure sentiment and prompt you to reassess which scenarios feel realistic.
Explore 4 other Simpson Manufacturing fair value estimates, including one that suggests as much as 58% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Simpson Manufacturing research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Simpson Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simpson Manufacturing's overall financial health at a glance.
Looking For More Ideas Beyond Simpson Manufacturing?
If Simpson Manufacturing has sharpened your thinking about quality, balance sheets and earnings risk, use that same lens across the wider market. The Simply Wall St Screener can help you quickly filter for other listed businesses that fit the kind of profile you want to research next.
- For investors who want potential mispricing with fundamentals in focus, start by checking a curated set of 35 high quality undervalued stocks that might warrant a closer look.
- If capital preservation and steadier profiles are higher on your list, consider scanning 32 resilient stocks with low risk scores and compare how their risk scores line up with your comfort level.
- To combine financial strength with business quality, broaden your watchlist using a 20 high quality undiscovered gems that could complement or contrast with Simpson Manufacturing in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com