
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Revisions Could Change The Case For Antero Resources Stock (AR)
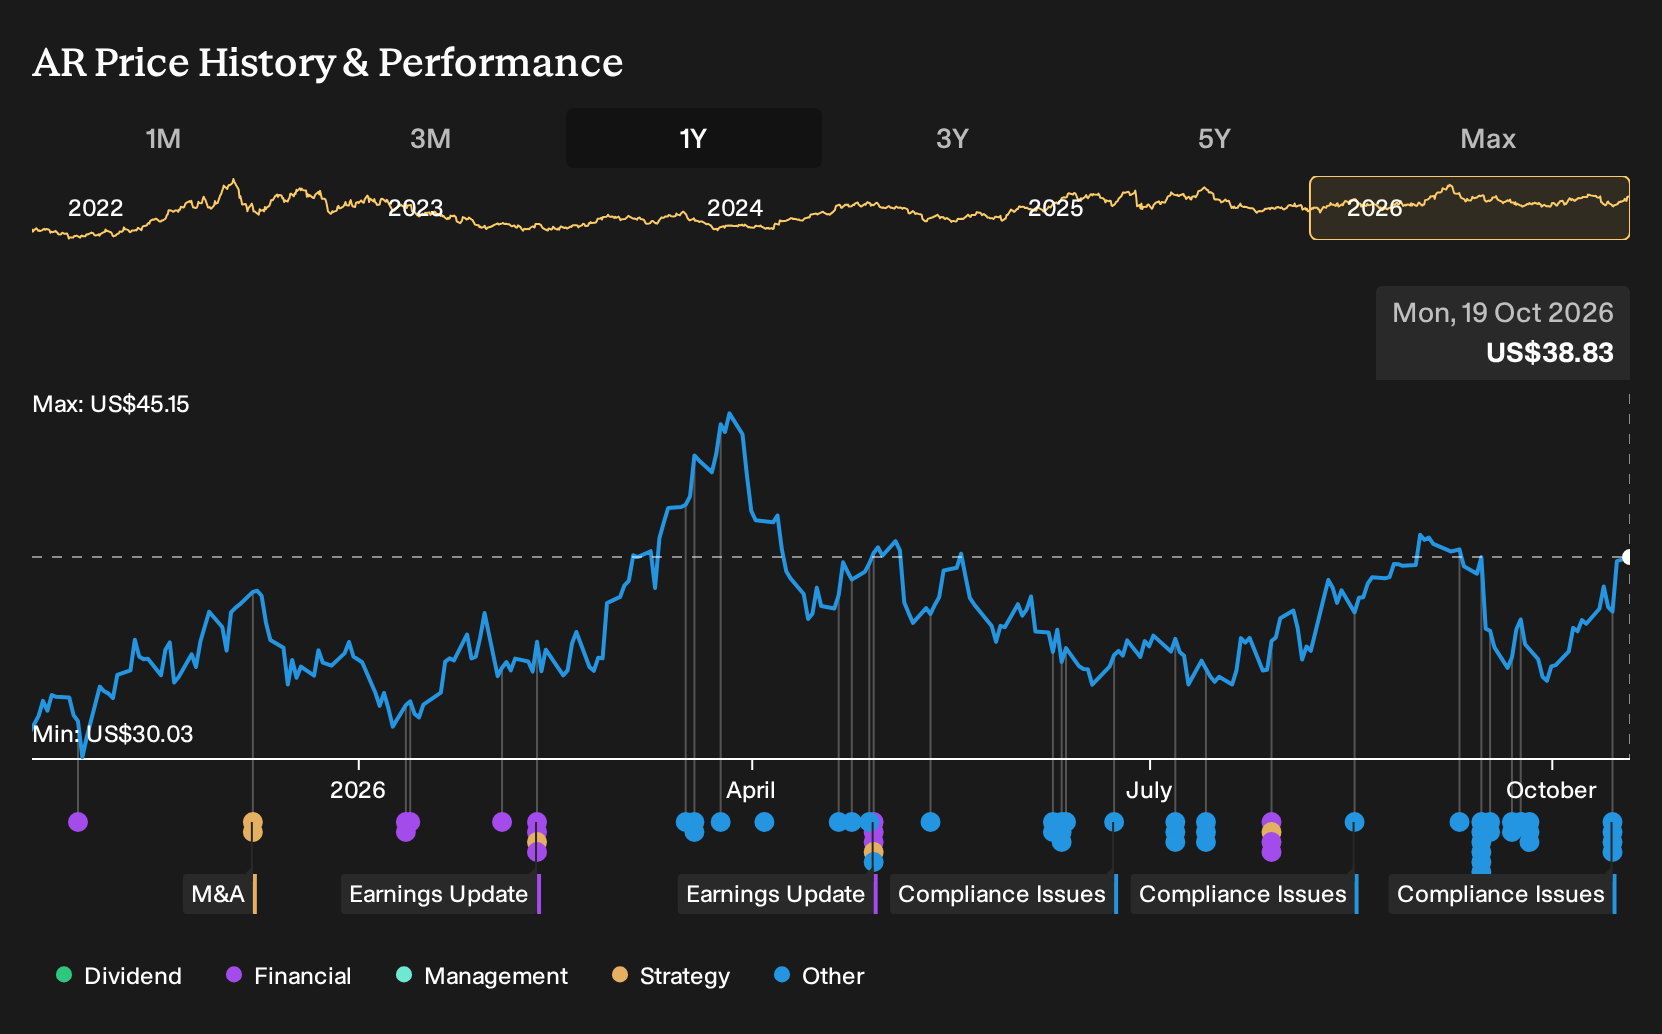
- Antero Resources recently filed multiple motions to intervene at the Federal Energy Regulatory Commission on pipeline tariff and project filings that affect its long term firm transportation used to move production to market.
- The filings highlight the extent to which Antero Resources relies on contracted pipeline access and tariff terms, which directly influence its cost structure and its ability to execute on transport optimization plans.
- We will now look at how the Antero Resources investment narrative could be influenced by these FERC interventions related to its transport arrangements.
Antero Resources Investment Narrative Recap
Owning Antero Resources means buying into a gas and NGL producer that relies on firm transport, cost discipline and access to premium markets. The key near term upside still rests on execution of its cash cost reduction plan and continued use of pipeline capacity to link volumes to export linked pricing where possible. The recent FERC motions look more like housekeeping around critical transport links than a shift in the operating playbook.
The biggest near term operational risk remains pressure on margins if transport costs or access terms change, or if previous profitability challenges reappear. These intervention filings are about staying close to tariff and project decisions that could influence delivered costs. Unless the commission outcomes materially alter existing long term firm service, the immediate impact on the core cost reduction and export exposure catalysts appears limited.
The most relevant item for this discussion is Antero Resources filing to intervene in Equitrans L.P’s tariff revision that removes contract 1992 when it expires on October 31, 2026. This involves a negotiated rate agreement tied directly to how Antero moves production. The filing underlines that firm service on this system is not a side issue for the business model.
For you as a shareholder or prospective investor, the link is simple. Transport terms feed straight into the attempt to cut total cash costs to about US$2.00 per Mcfe by year end 2028 and to keep more volumes reaching higher value outlets. Analyst sentiment around earnings and value can shift. The hard operational work happens in these tariff rooms, where Antero tries to keep its cost and access assumptions intact.
How Antero Resources’ FERC Focus Connects To Analyst Assumptions
The intervention around transport contracts sits alongside a fairly specific analyst story about where Antero Resources could be by the end of this decade. That narrative leans on the idea that keeping firm pipeline access on reasonable tariff terms can support the earnings path analysts are building into their models.
Analyst assumptions today sketch out a company that holds its cost work and transport access together with moderate top line expansion. Forecasts call for revenue to grow by 7.0% per year over the next three years, profit margins to move from 18.7% to 20.0%, and earnings to rise from US$1.1b today to US$1.4b by 2029, with some projections going as high as US$2.1b. For you, the key question is how much of that improvement depends on keeping long haul transport locked in on terms that do not unexpectedly lift unit costs.
Valuation expectations tie directly into those operating assumptions. Consensus work suggests that if Antero Resources reaches about US$7.1b in revenue and US$1.4b in earnings in 2029, the stock would need to trade on a P/E of 13.3x, compared with 9.7x today and an indicated 12.3x level for the wider US oil and gas sector. That multiple relies on investors still being comfortable that cash cost targets, export exposure and firm transport economics remain intact, which is why the FERC tariff process matters for anyone trying to line up these forecasts with reality.
Antero Resources' narrative projects forecast revenue of US$7.1b and earnings of US$1.4b by 2029. This is built on analysts assuming 7.0% yearly revenue growth and an earnings increase of about US$300m from current earnings of roughly US$1.1b.
Uncover why Antero Resources' fair value indicates a 29% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame these FERC motions as a potential catalyst. You see that in their pre news forecasts, which pencilled in revenue of about US$8.3b and earnings near US$2.1b by 2029. That view assumes Antero Resources can squeeze more value from transport contracts, although this new regulatory wrinkle might yet reshape those expectations.
Explore 3 other Antero Resources fair value estimates, including one that suggests as much as 278% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Antero Resources research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Antero Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Antero Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Antero Resources?
If the Antero Resources story has you thinking about risk, rewards and transport exposure, it can help to compare it with other companies that score well on quality, balance sheet strength or income potential. The Simply Wall St Screener lets you sort the broader market by exactly those traits so you can build a watchlist that matches your own priorities rather than relying only on consensus views.
- If capital preservation sits high on your list, you can start with a group of companies that our models score as more resilient and lower risk by checking out 32 resilient stocks with low risk scores.
- If income is the focus, you can look across stocks with higher yields that aim for more dependable payouts by reviewing 8 dividend fortresses.
- If you want a broad foundation of financial strength, you can filter for businesses with sturdier balance sheets and steadier fundamentals through our list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com