
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Glacier Bancorp (GBCI) Nears Earnings, Is The Stock Still Cheap?
Glacier Bancorp (GBCI) is back in focus as its next quarterly report approaches, with analysts expecting year-over-year increases in both earnings and revenue for the September 2026 period.
Recent trading shows mixed sentiment around Glacier Bancorp. The share price has slipped about 17% over the past 90 days and is down modestly year to date, even though the 1 year total shareholder return is positive and the 3 year total shareholder return is strong. This suggests that long term holders have still been rewarded despite the recent pullback.
Benchmark Glacier Bancorp against a hand picked 32 resilient stocks with low risk scores group that also rely on steady financial profiles and more resilient return patterns around earnings season.
Bulls point to Glacier Bancorp’s earnings and revenue growth, while bears focus on the recent 17% slide and softer EPS expectations. Which story does the current valuation actually support?
Most Popular Narrative: 22% Undervalued
Glacier Bancorp's most followed valuation story pegs fair value near $55.83, above the recent $43.60 close. This puts the current pullback in a very different light for investors weighing the next earnings print.
Continued repricing of Glacier Bancorp’s loan and securities books, combined with the removal of $440 million of higher cost Federal Home Loan Bank advances and lower total funding costs that moved from 1.52% in Q4 2025 to 1.33% in Q2 2026, is expected to keep widening net interest margin and support future earnings.
See why 4 investors see Glacier Bancorp as 22% undervalued.
Result: Fair Value of $55.83 (UNDERVALUED)
Still, the Glacier Bancorp story can break if net interest margin stalls after recent gains, or if loan and deposit mix shifts toward lower returning segments.
Find out about the key risks to this Glacier Bancorp narrative.
Another View: Glacier Bancorp On Earnings Multiples
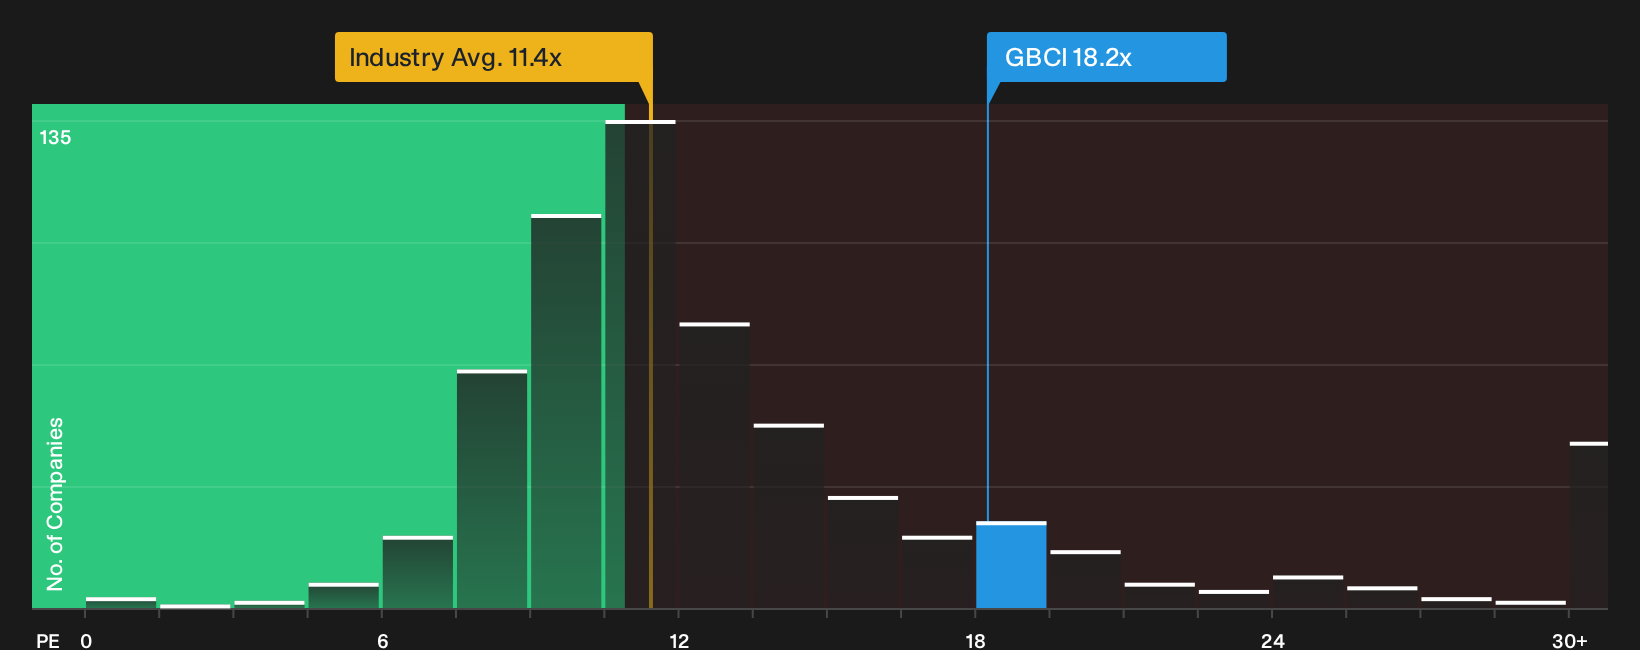
Glacier Bancorp may screen as undervalued on fair value estimates, yet the P/E ratio tells a tougher story. The stock trades on 18.2x earnings, while the US Banks group sits around 11.5x and the fair ratio points closer to 15.2x. This leaves less room for error if growth slows.
To see how that earnings multiple stacks up against the wider sector and the fair ratio glide path, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if they help you act. Consider Glacier Bancorp's pullback, its upside case, and its potential weak spots, then review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Glacier Bancorp?
If Glacier Bancorp sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas that share solid fundamentals and clear, data driven stories.
- Target resilient compounding potential by scanning a 35 high quality undervalued stocks list that combines strong fundamentals with prices that sit below fair value estimates.
- Strengthen your income stream by reviewing a curated 8 dividend fortresses that filters for higher yielding payouts supported by underlying financial metrics.
- Tighten your risk profile by focusing on a list of solid balance sheet and fundamentals (25 results) so you are not caught off guard when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com