
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Hongkong Land Holdings (SGX:H78) Orchard Road Property Talks
- Hongkong Land Holdings has reportedly been in advanced talks to acquire majority stakes in several Orchard Road properties in Singapore, a move that could reshape its income mix toward more recurring retail and office rental exposure.
- The potential Orchard Road transaction highlights how Hongkong Land Holdings may be reallocating capital toward established, high-traffic assets at a time when parts of its Mainland China portfolio face softer demand and execution risks.
- We will now look at how Hongkong Land Holdings' investment narrative could be influenced by the potential Orchard Road acquisition plan.
Scan Hongkong Land Holdings alongside other potential value opportunities by reviewing the 198 high quality undervalued stocks that offer a mix of solid fundamentals and attractive pricing.
Hongkong Land Holdings Investment Narrative Recap
To own Hongkong Land Holdings, you need to be comfortable with a property group shifting its earnings mix toward recurring income while managing pressure in its Mainland China build to sell activities and its Hong Kong office exposure. The key near term swing factor is how quickly new and repositioned assets reach steady occupancy at sensible rents.
The Orchard Road talks sit neatly in that context. If the deal proceeds on disciplined terms, the extra Singapore retail and office exposure could gradually support earnings stability rather than change the near term trajectory. The bigger immediate risk still sits in China project exits, possible divestments below book value, and oversupply in key office markets.
One of the more important recent developments around Hongkong Land Holdings is its continued focus on capital recycling, reinforced by transactions such as the HKEX Exchange Square sale at book value. That sort of outcome matters because it shows the group can turn mature assets into cash without taking an accounting hit to net asset value.
The potential Orchard Road acquisition would pull that capital back into another set of prime properties, alongside ongoing projects like Tomorrow's CENTRAL and West Bund Central. Your call is whether this recycling improves long term resilience faster than risks build up from softer Chinese property sentiment, low forecast returns on equity, and earnings that analysts expect to trend lower.
Hongkong Land Holdings is currently modeled on analyst numbers that point to revenues of $1.6b and earnings of $909.1m by 2029, based on 4.4% yearly revenue growth and an earnings decline of about $390m from the current $1.3b level.
Discover why Hongkong Land Holdings' fair value indicates a 23% potential upside to its current price that could close sooner than the market expects.
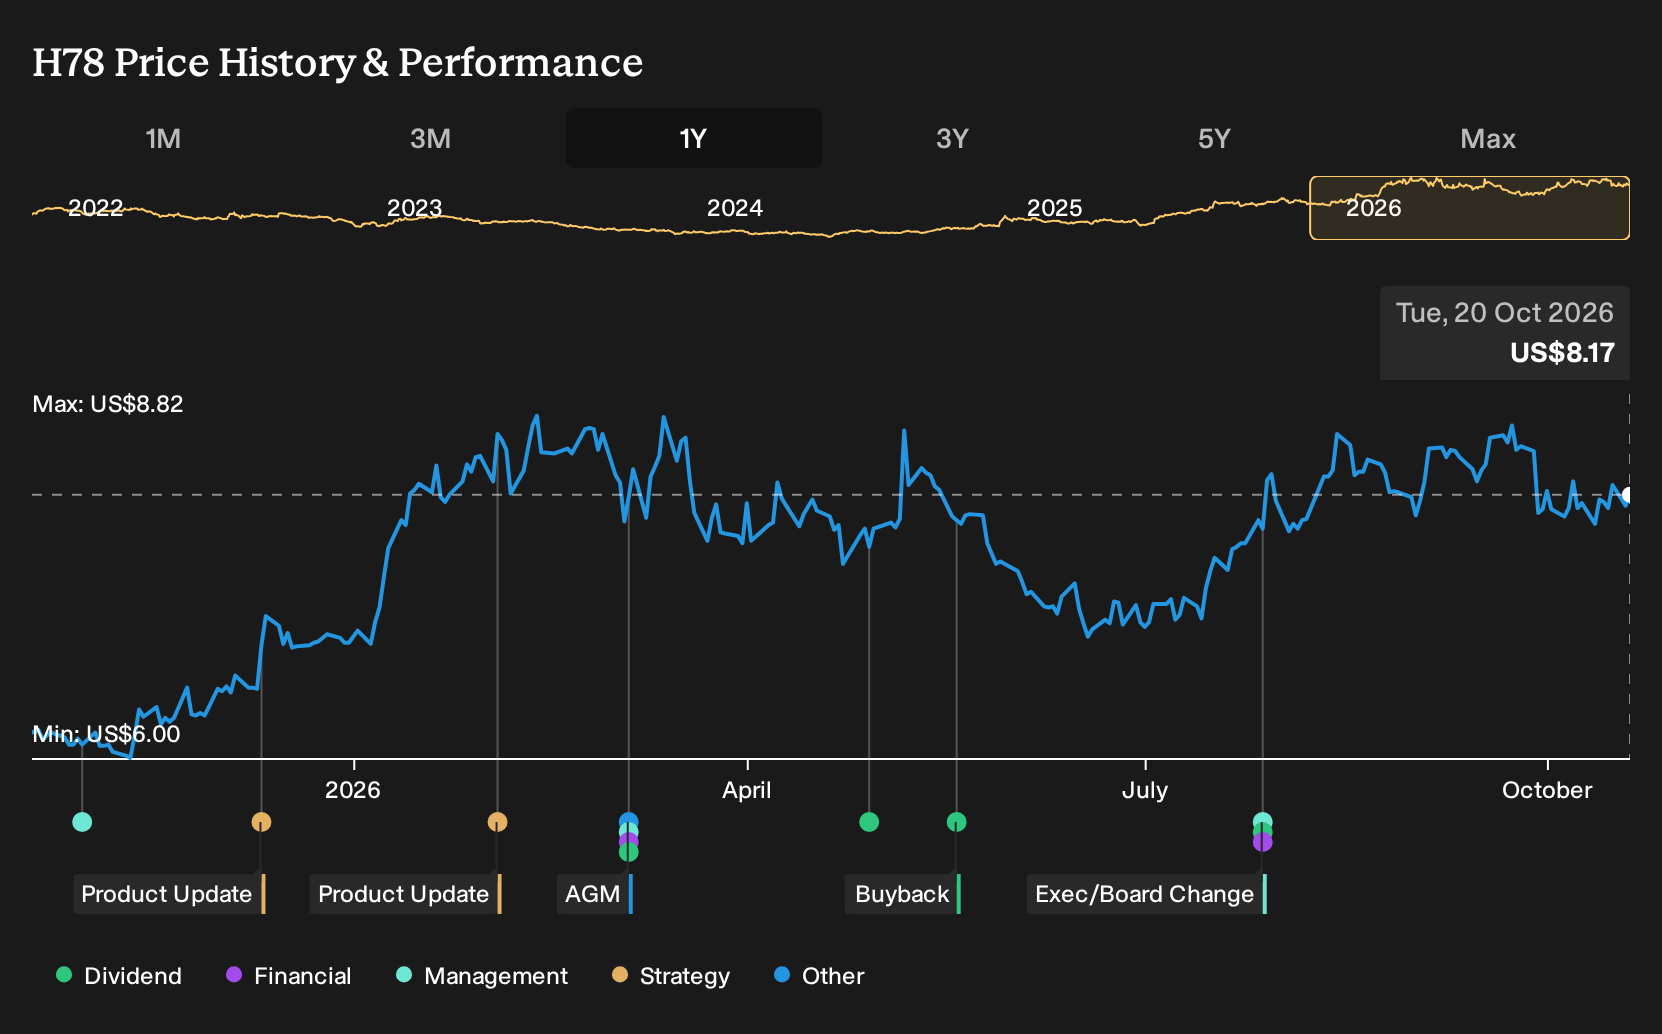
Exploring Other Perspectives
One alternate view on Hongkong Land Holdings puts long term office demand front and center. The most cautious analysts were pencilling in revenue of about $1.4b and earnings of $600.9m by 2029 before this Orchard Road news, far below consensus. This shows how sharply opinions differ and why exploring several viewpoints can really help you.
Explore 4 other Hongkong Land Holdings fair value estimates, including one that suggests as much as 61% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hongkong Land Holdings research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hongkong Land Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Hongkong Land Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Hongkong Land Holdings?
Once you have a view on Hongkong Land Holdings, it can help to widen the lens and compare it with a few other opportunities that share some of the characteristics you care about most.
The Simply Wall St Screener lets you filter for those traits directly, so you can build a shortlist that fits your own risk tolerance and income goals rather than relying on headlines.
- If you want lower volatility and steadier balance sheets, start with companies that score well on financial strength using this 230 resilient stocks with low risk scores.
- For investors focusing on income, compare Hongkong Land Holdings with other businesses that combine higher yields and resilience by reviewing this 221 dividend fortresses.
- If your priority is quality at a reasonable entry point, scan for stocks that pair solid fundamentals with attractive pricing through this 198 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com