
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Olympus (TSE:7733) Could Be 21% Undervalued Following FDA Warning Letter
Olympus (TSE:7733) is back in focus after a fresh FDA Warning Letter on its quality systems, landing just days before the U.S. debut of its new peripheral EBUS bronchoscope.
Investors have been reminded how quickly sentiment can shift around Olympus. The fresh FDA Warning Letter has landed just as the new peripheral EBUS bronchoscope hits the U.S. market, and the share price is now at ¥1,733 after a 7 day share price return decline of 14.74% and a year to date share price return decline of 14.82%.
Scan how other medical device stocks are reacting to regulatory pressure and product launches by lining up Olympus against a hand-picked 20 resilient stocks with low risk scores.
After a 14% slide leaves Olympus at ¥1,733, the question now is whether this reset has cleared space for meaningful upside or already pulled most of the future return into today’s price. Time to test the valuation.
Most Popular Narrative: 20.7% Undervalued
On Simply Wall St’s most followed view, Olympus screens as undervalued, with a narrative fair value of ¥2,184.62 versus the latest close at ¥1,733, which puts the recent selloff squarely against a thesis built on cost cuts, quality cleanup and China execution.
The structural reform program targeting about JPY 24 billion of run rate savings from roughly 2,000 net headcount reductions over FY26–27, most of which has already been provisioned, is designed to lower Olympus’ ongoing cost base and support higher operating margins and net income from FY27 onward.
See why 2 investors see Olympus as 21% undervalued.
Result: Fair Value of ¥2,184.62 (UNDERVALUED)
Still, the FDA Warning Letter and ongoing China policy risk leave real room for setbacks if quality remediation or localization efforts stall from this point.
Find out about the key risks to this Olympus narrative.
Another View: What Olympus Looks Like On Earnings
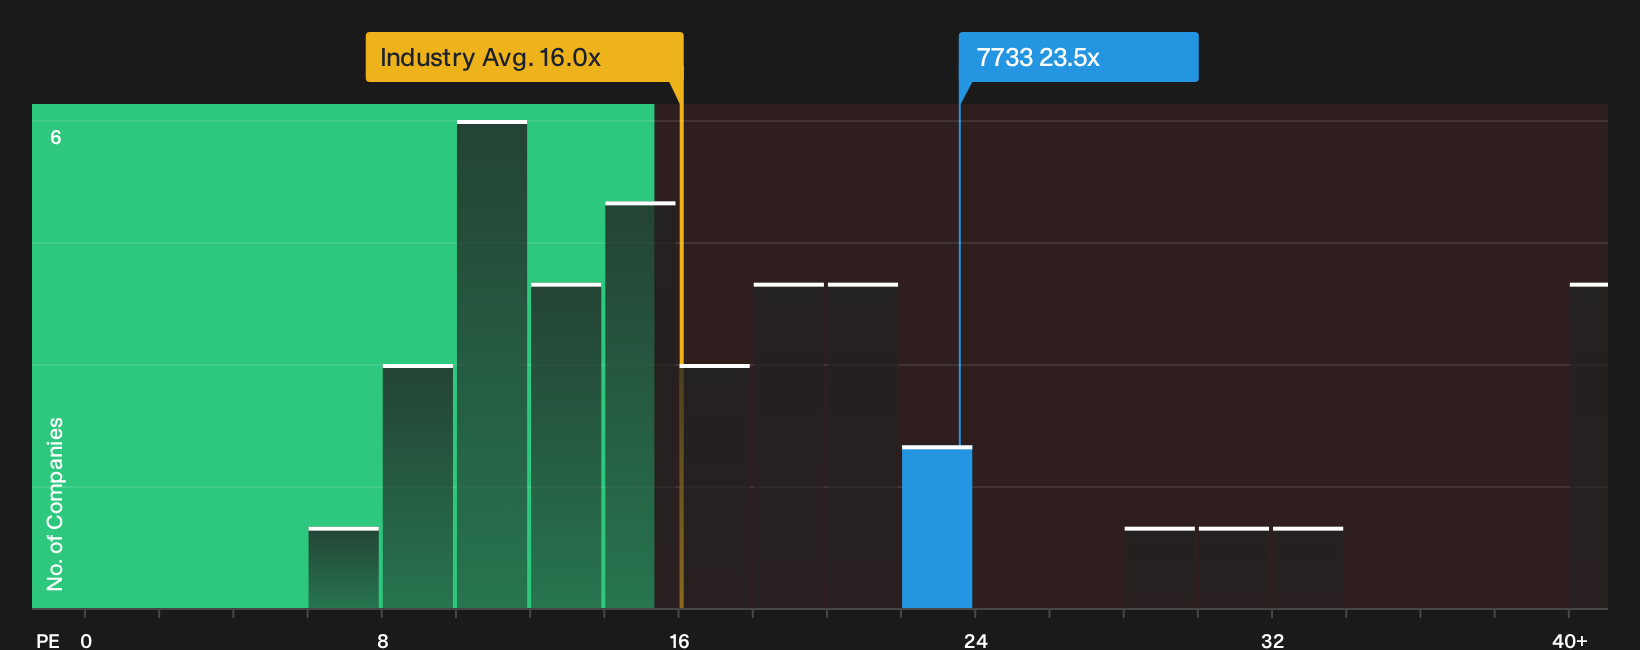
The SWS model flags Olympus as trading below an earnings based fair value, yet the raw P/E tells a more cautious story. The stock is on 23.5x earnings versus 16x for the wider JP Medical Equipment industry and 21.1x for peers, while the fair ratio is 26.4x. That premium to the sector, but discount to the fair ratio, suggests investors are paying up compared with rivals but not fully embracing the SWS earnings thesis. Which side of that gap do you want to lean toward?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This piece reflects both optimism and concern regarding Olympus, so consider acting promptly, review the underlying data, and carefully weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Olympus?
If Olympus raised fresh questions for your portfolio, do not stop here. Cast a wider net and pressure test your next moves with focused screeners.
- Target potential mispricings by scanning a curated 13 high quality undervalued stocks that combines quality fundamentals with pricing that may not fully reflect them.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (22 results) so you focus on businesses backed by healthier financial footing.
- Spot future contenders early by running through a 73 high quality undiscovered gems that highlights companies with strong metrics but limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com