
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Atkore (ATKR) Fully Valued On Its Prysmian Deal And Debt Reset?
Atkore (ATKR) has effectively reset its capital structure following the completed sale to Prysmian. The business repaid all credit facilities, redeemed US$400 million of 4.25% Senior Notes, and removed associated liens and guarantees.
Atkore’s recent refinancing sits against a backdrop of strong momentum, with the share price at US$94.96 and a 90 day share price return of 27.39%, a year-to-date share price gain of 47.38%, and a 3 year total shareholder return that is down 20.34%, highlighting how the current strength follows a much tougher earlier period.
Scan how the Atkore deal compares with other balance-sheet focused plays by reviewing our curated list of solid balance sheet and fundamentals (25 results) across the market.
Atkore’s rally into the Prysmian takeout price could signal investors reassessing the underlying wiring and infrastructure business, rather than just chasing a merger headline. Does that recent move still look reasonable on the numbers?
Most Popular Narrative: 2% Overvalued
Atkore’s most followed storyline pegs fair value at $93.50 using a 10.34% discount rate, which sits just below the last close at $94.96 and frames the Prysmian deal as a full pricing of that view.
Prysmian’s planned integration of Atkore with an all cash acquisition that targets US$150 million of annual synergies by 2029, with a mix of commercial and operational benefits, is intended to improve efficiency and pricing power and can influence future EBITDA margins and cash generation.
See why 28 investors see Atkore as 2% overvalued.
Result: Fair Value of $93.50 (OVERVALUED)
Still, falling average selling prices and legal expenses that reduced recent GAAP net income to about zero could quickly challenge the current Atkore fair value story.
Find out about the key risks to this Atkore narrative.
Another View: What Atkore’s P/S Ratio Signals
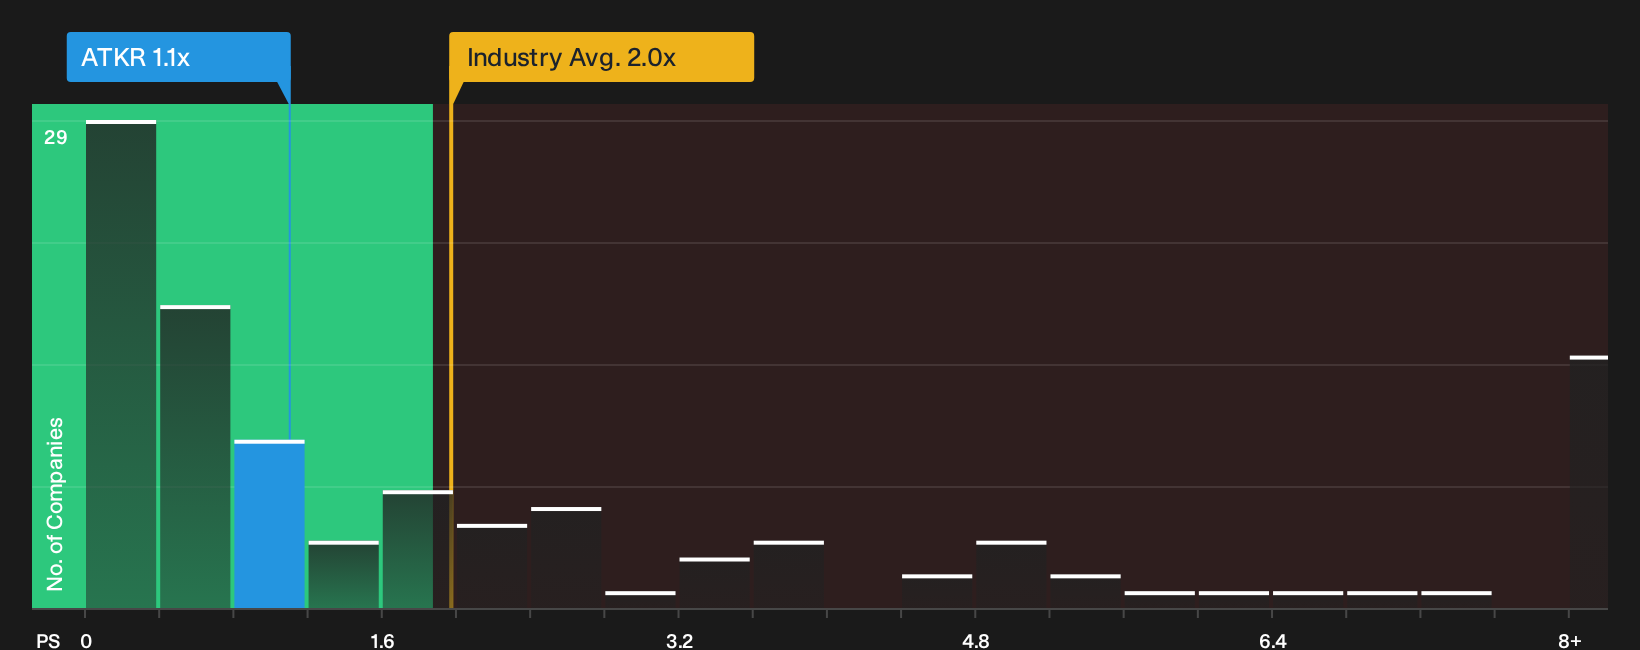
On the headline fair value, Atkore screens as only 0.1% below the model estimate and the narrative tags it as about 2% overvalued. Yet the P/S ratio tells a softer story, with ATKR at 1.1x vs 1.9x for the US Electrical industry and 2.2x for peers, compared with a fair ratio of 1x that the market could drift toward over time. Does that pricing gap point to a slim cushion or a cramped upside for anyone buying at today’s level?
To see how that sales multiple stacks up in more detail, run the numbers side by side in our valuation breakdown, then test whether it matches your own risk and return expectations for Atkore. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Atkore story today. Check the data, weigh the concerns and bright spots, then ground your own view in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Atkore?
If Atkore has sharpened your focus on valuations and balance sheets, do not stop here. Fresh ideas often come from scanning high quality companies side by side.
- Target resilient cash generators and stress test your downside profile using our 32 resilient stocks with low risk scores that surfaces businesses with lower risk scores.
- Hunt for quality at a discount by scanning the 35 high quality undervalued stocks that filters companies combining strong cash flows with robust financial positions.
- Spot potential future market leaders early with the 20 high quality undiscovered gems that highlights smaller, overlooked stocks backed by solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com