
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GOOGL Stock Earnings Preview: What to Expect From Alphabet’s Q3 2026 Report
Alphabet (GOOG) (GOOGL) will release its third-quarter 2026 financial results on Wednesday, October 28. Google's parent company has maintained strong financial momentum, recording double-digit revenue growth for 12 consecutive quarters. Growing demand for artificial intelligence (AI)-powered products and services has helped drive this performance, and investors will look for further evidence of that momentum in the September quarter.
However, sustaining this growth may not be straightforward. A tougher year-over-year comparison in Google Search could put pressure on revenue growth, while increased spending to expand AI infrastructure may weigh on profit margins.
For investors, the upcoming earnings report will offer important insights into Alphabet’s ability to balance AI-driven growth with profitability and capital expenditure. Let’s take a closer look at what to expect from Alphabet’s Q3 earnings report.
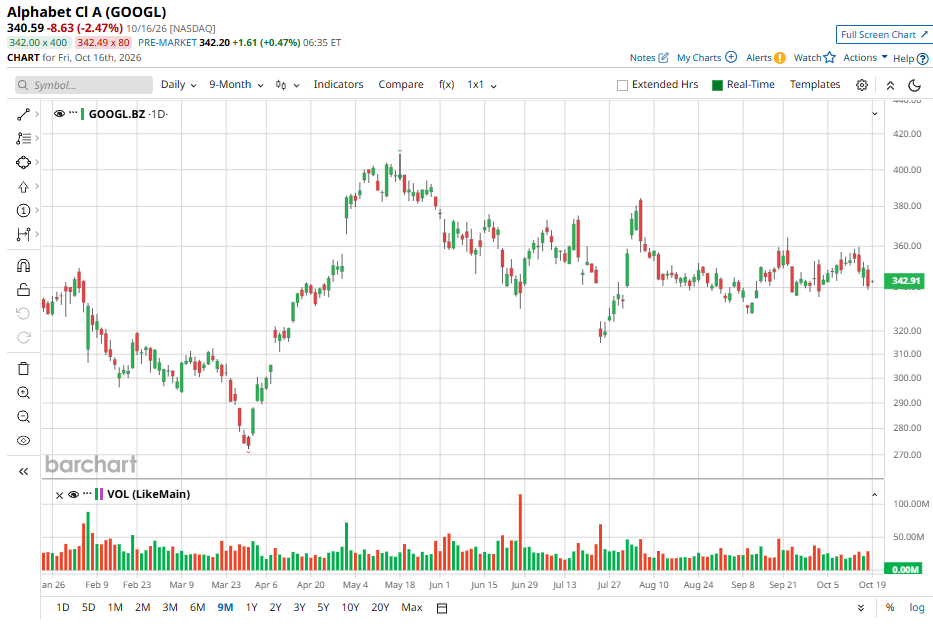
Here’s What to Expect in Q3
Alphabet’s diversified revenue base, expanding cloud business, and growing subscription ecosystem position it well to deliver solid Q3 growth, even as tougher year-over-year comparisons in Search create a potential headwind.
Google Search remains a key contributor to Alphabet’s revenue, but year-over-year growth could moderate because the prior year was stronger. Search growth began accelerating in the third quarter last year, making the upcoming quarter a tougher comparison.
Nevertheless, advertising revenue could remain resilient. Higher user engagement, supported by AI-powered search features and improvements in the overall advertising ecosystem, may help sustain demand.
Beyond advertising, Alphabet’s subscription business continues to provide an additional source of recurring revenue. Services such as YouTube Music, YouTube Premium, and Google One are expected to support third-quarter performance.
Moreover, Google Cloud remains one of Alphabet’s most important growth opportunities, driven by solid demand for its cloud infrastructure, AI computing capacity, and enterprise AI solutions.
The business delivered strong second-quarter results. Revenue surged 82% year over year to $24.8 billion, up from 63% growth in the first quarter, reflecting rising demand for Google Cloud Platform (GCP).
Profitability also improved significantly for the cloud business. Google Cloud generated $8.8 billion in operating income, more than tripling year over year. Its operating margin expanded to 35.6% from 20.7%, indicating that revenue growth is translating into stronger operating leverage.
Alphabet’s expanding cloud backlog further supports its growth prospects. The backlog rose more than $50 billion sequentially to $514 billion, reflecting strong demand for the company’s cloud services and infrastructure.
The company also began recognizing revenue from tensor processing unit (TPU) systems deployed in customers’ data centers during the second quarter. These custom-designed AI chips give Alphabet another way to monetize its AI infrastructure beyond traditional cloud computing services.
Management has indicated that demand for Google Cloud products and services remains significant, supporting expectations for continued strong growth in Q3.
Despite the favorable revenue growth outlook, Alphabet’s higher capital expenditures could weigh on earnings and free cash flow. Analysts expect Alphabet to report third-quarter earnings of $2.94 per share, up from $2.87 in the same period last year. That implies modest year-over-year earnings growth, despite the company’s strong cloud momentum. Alphabet has exceeded analyst earnings expectations in each of the past four quarters, including a notable beat in its most recently reported quarter.
Overall, Alphabet appears well positioned to sustain growth in Q3, supported by its advertising business, expanding subscription revenue, and rapidly growing cloud operations.
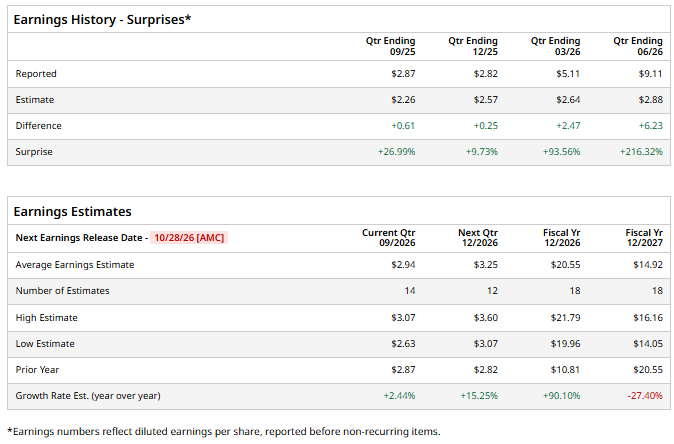
The Key Takeaways
Alphabet’s Q3 will reflect tougher Search comparisons. However, solid advertising growth, strong demand for Google Cloud and AI services, and subscription momentum will support growth. However, elevated AI infrastructure spending could restrict margins and cash flow.
Alphabet’s long-term growth outlook remains strong, and its stock appears attractively valued. Trading at around 17 times forward earnings, the stock looks reasonably priced compared with its large-cap technology peers. Analysts remain optimistic, maintaining a “Strong Buy” consensus rating ahead of its Q3 earnings release.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.