
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hexcel (HXL) Undervalued On Weak Full Year Guidance?
Hexcel (HXL) has been in focus after reporting quarterly revenue of $529.3 million, up 8% year on year. The company also issued full-year guidance that came in weaker than aerospace peers and triggered a sharp share-price reaction.
Hexcel shares have rebounded in the very short term, with a 7.84% 7 day share price return and a 3.93% 30 day share price gain, yet the stock is still down 15.70% over 90 days while the 1 year total shareholder return of 46.10% reflects longer term momentum that investors are weighing against the recent guidance reset.
Scan beyond Hexcel's reset guidance and compare how other aerospace and industrial suppliers with similar revenue profiles line up on fundamentals with the list of solid balance sheet and fundamentals (25 results).
Hexcel has already retraced part of its post guidance drop, yet the share price is still working off that reset. The key question now is how much of the potential recovery is already reflected in the valuation.
Most Popular Narrative: 16% Undervalued
Against Hexcel's last close of $91.61, the most followed narrative pegs fair value at about $108.50. The current reset already bakes in a discount that depends heavily on execution around revenue, margins and cash generation over the next few years.
The main condition is that Hexcel turns the planned roughly $700 million of incremental commercial and defense revenue and its existing capacity into the higher margin profile management is targeting, while containing inflation and start up costs.
The numbers now imply a bullish view on Hexcel. Current margins, cash generation targets and external valuation work together to suggest the share price does not fully reflect the projected earnings and free cash flow profile.
See why 6 investors see Hexcel as 16% undervalued.
Result: Fair Value of $108.50 (UNDERVALUED)
Still, Hexcel’s heavier hiring and restart costs, together with long term Airbus contracts signed before recent inflation, could restrain the margin improvement that this narrative anticipates.
Find out about the key risks to this Hexcel narrative.
Another View: Hexcel Through A Market Multiple Lens
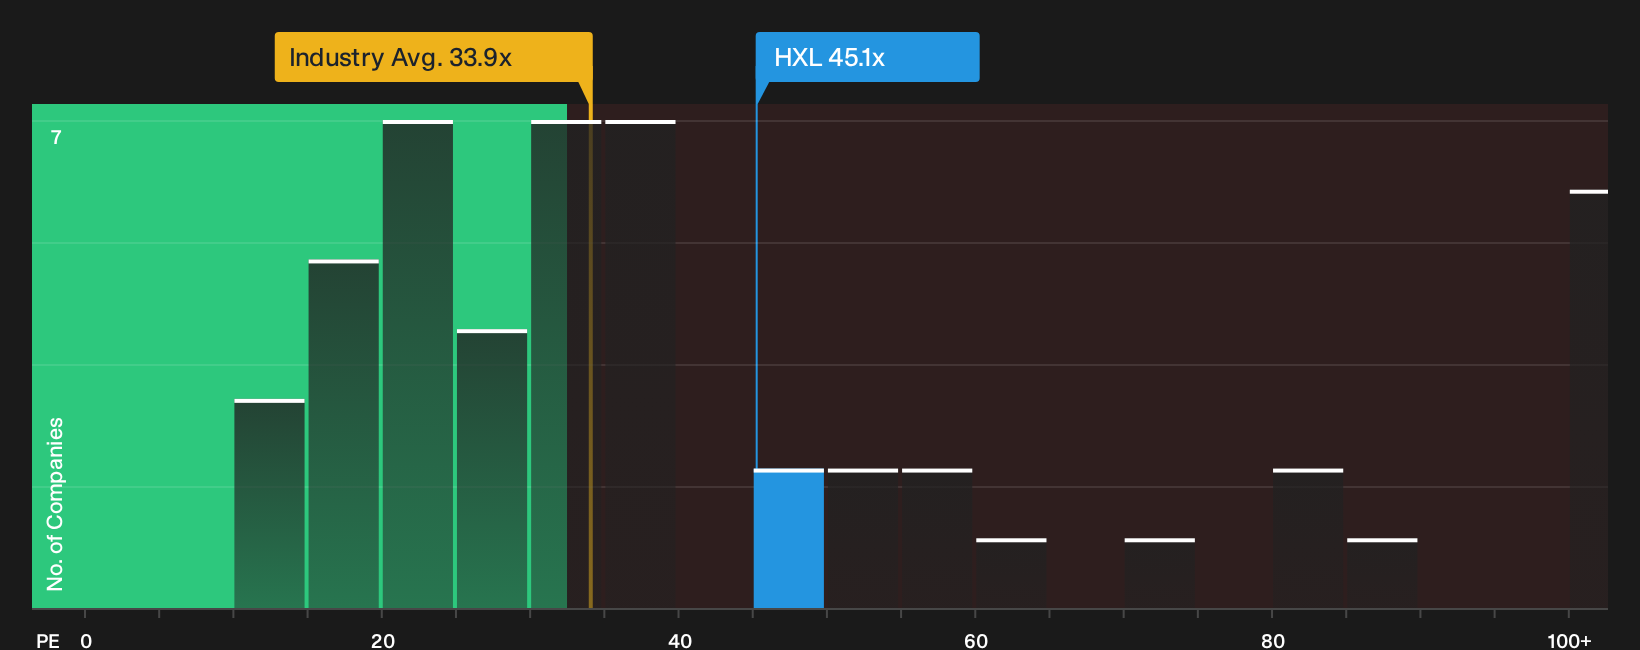
Hexcel looks inexpensive against the $108.50 fair value from the narrative, yet the P/E tells a tougher story. The shares trade on 45.1x earnings versus a 27.5x fair ratio and a 33.8x industry average, which points to richer expectations and more valuation risk if growth or margins underwhelm.
To see how that premium lines up with the underlying numbers and where the market could move if sentiment cools or improves, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Hexcel is mixed, so move quickly, review the full set of numbers and pressure test your own thesis against 3 key rewards and 1 important warning sign
Looking for more Hexcel-sized opportunities?
If Hexcel has sharpened your appetite for detailed research, do not stop here. Use focused screens to surface other ideas before the market prices them more fully.
- Target potential mispricings by running your filters through 35 high quality undervalued stocks that already score well on quality checks.
- Build a steadier core by scanning for income ideas in the 8 dividend fortresses that combine yield with resilience.
- Limit unpleasant surprises by zeroing in on companies in the 32 resilient stocks with low risk scores that pair financial strength with measured volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com