
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
As CRWV Stock Comes Under Pressure, Cantor Fitzgerald Gives CoreWeave a Thumbs Up
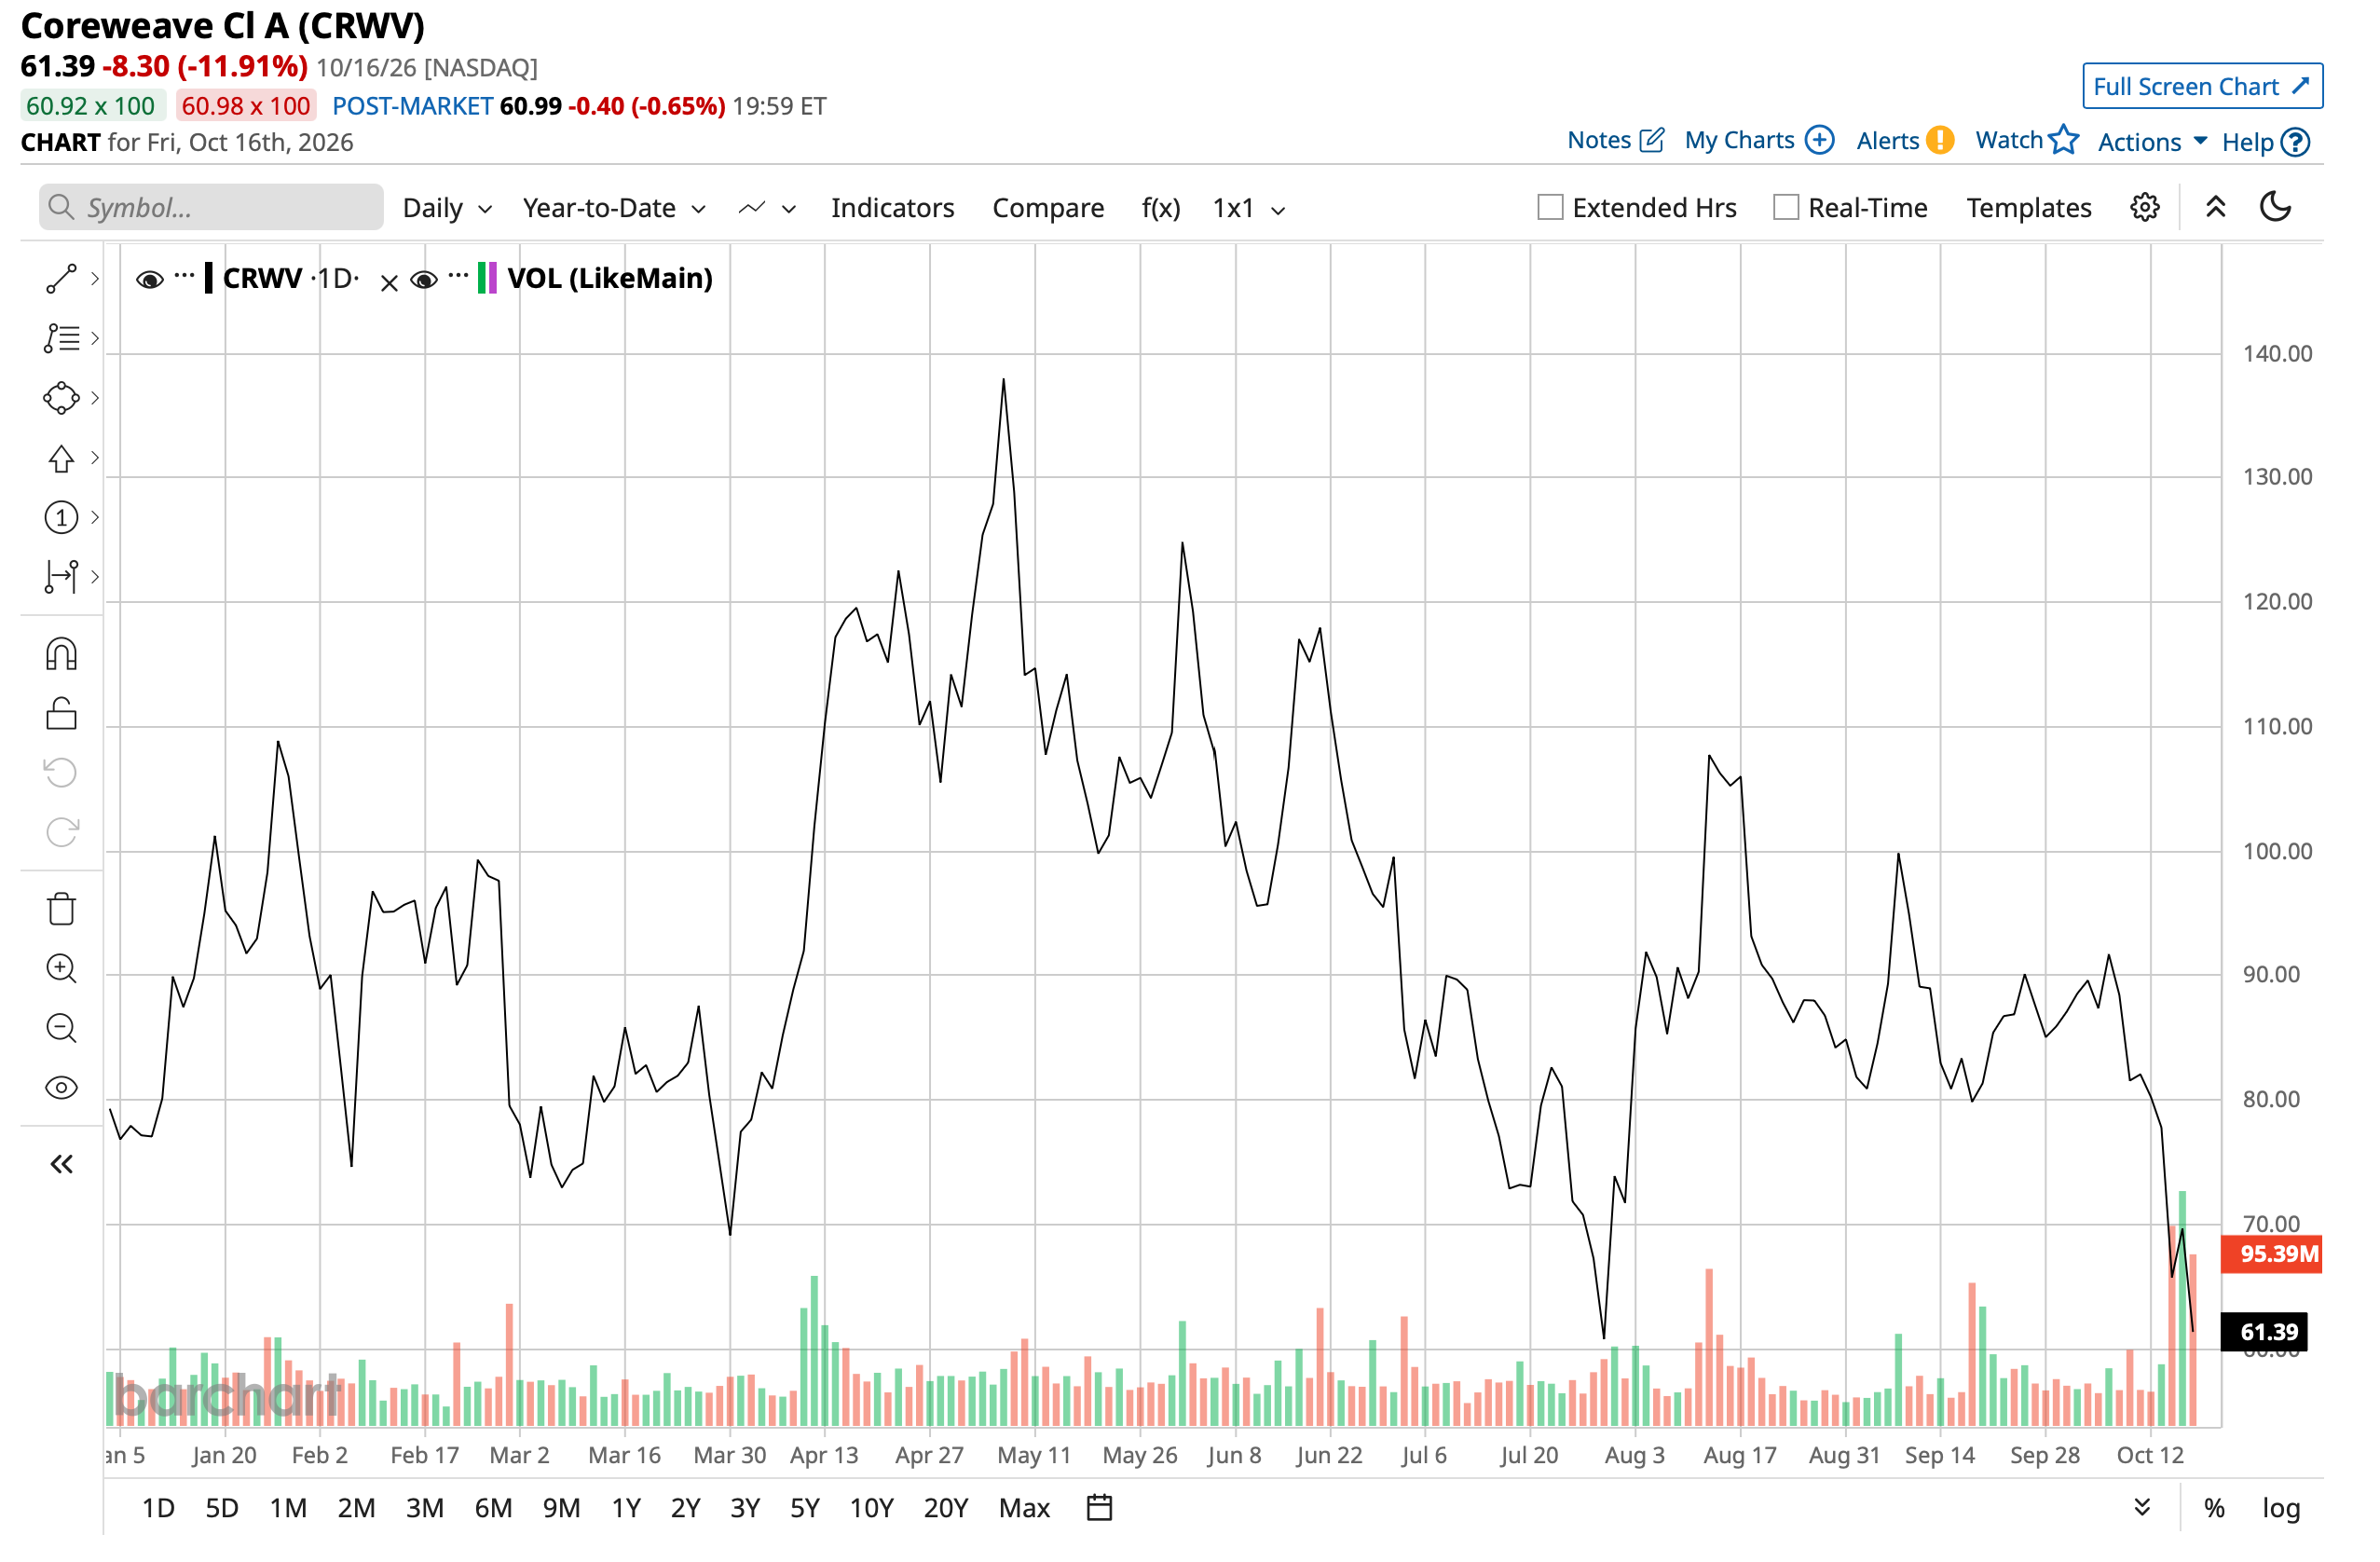
Shares of neocloud provider CoreWeave (CRWV) have come under pressure as the Federal Reserve raises interest rates and the company's capital expenditures increase. Investors are getting spooked by the specter of higher interest expenses on the company's significant debt burden. Moreover, the downward adjustment of a key customer's revenue to $50 billion from $70 billion did not help matters either. Thus, its shares are down more than 30% in less than a fortnight.
Yet, that has not deterred Wall Street firm Cantor Fitzgerald's bullishness about CoreWeave. Assigning an “Overweight” rating on the stock, analyst Brett Knoblauch said, “CRWV has the public support of NVDA — the most influential company when it comes to AI. CRWV also already sold out nearly all of the capacity coming online for 2027. NVDA also has an agreement to backstop any unsold capacity."
Knoblauch explained the market's reaction is not about whether CoreWeave has sufficient demand — it does, as its sold-out capacity illustrates — rather it's whether the neocloud can afford to pay for the growth necessary to meet that demand. He recommends investors view CoreWeave's position from where it came from to where it is today. Knoblauch says, “When CRWV went public, we estimate it was getting $10-11m/MW of revenue while generating ~15% contribution margins on those deals. Fast forward to today, we believe it is closer to $20m/MW, and it is generating 25-30% contribution margins. This results in chips, which is what capex is being spent on, paying for themselves in 2-2.5 years versus 4 years.”
By relying upon asset-backed facilities to fund its capex, CoreWeave repaying its debt is not an issue, so long as the demand is there. That's because as its chips generate cash flows, those facilities receive interest and principal.
The optimism is also reflected in the firm's price target of $176 for the stock, one of the highest on Wall Street. It implies a potential upside of about 187% from current levels.
About CoreWeave
Founded in 2017 as a cryptocurrency mining business, CoreWeave occupies the vaunted position of being one of the foremost AI infrastructure companies in the world. Now, CoreWeave provides enormous amounts of specialized computing power to companies developing and running AI. It operates data centers containing large clusters of Nvidia GPUs, with the overall objective of making thousands of GPUs behave like a single high-performance computing system. It is also concentrating on building a software stack, with its capabilities launching in 2026 to connect training, inference, observability, reinforcement learning, and autonomous agent improvement.
Valued at a market cap of $28.2 billion, CRWV stock is down 14.3% on a YTD basis.
So, does the company's financial position have the wherewithal to withstand this so-called debt burden? Let's find out.
With Growth At Its Core, Some Key Points Sore
CoreWeave's operations are marked by notably high growth rates that are rarely seen in the markets. However, the picture became less straightforward as the company remains a loss-making entity and saw interest expenses rise by 2.5 times in the most recent quarter.
In the second quarter of 2026, CoreWeave generated revenue of $2.6 billion. That figure marked a 116.7% rise from the year-earlier period and came in ahead of Street forecasts.
Operating income margins fell to 5% from 16% a year ago. The company reported a net loss of $1.14 per share. Although the result was better than the consensus loss of $1.47, it was nearly twice the $0.60 loss recorded in the prior year. Losses have now widened for three consecutive quarters.
Looking to the third quarter, CoreWeave projected revenue between $3.45 billion and $3.60 billion. The midpoint of the range would represent growth of 159.2% from the previous year. Analysts are currently modeling $3.54 billion. Full-year capital expenditure guidance was also lifted to $35 billion to $39 billion from the earlier range of $31 billion to $35 billion.
Meanwhile, the company's interest expenses jumped to $640 million from $267 million in the year-ago period, as long-term debt rose 48.4% to $46.1 billion. On the other hand, its closest competitor, Nebius Group (NBIS), saw its interest expenses soar at a much higher rate to reach $119.1 million from just $4.8 million in the year-ago period. However, CoreWeave's interest expense as a percentage of revenue at 24.6% was higher than Nebius's at 20.5%.
Backlog reached $104 billion as of June 30, 2026, nearly 3.5 times the level seen a year earlier. Management pointed out that the total excluded another $25 billion in newly secured customer commitments. Contracts signed during the quarter carried terms five to ten percentage points more favorable than those from the prior period. Together with the ongoing production ramp, this improvement is producing real operating leverage.
Cash flow trends were more constructive. Net cash from operating activities totaled $679 million compared with an outflow of $251 million in the year-ago quarter. CoreWeave closed the June 2026 period with $5.5 billion in cash, still below short-term debt of about $8.1 billion.
The company now expects to end the calendar year with active power capacity of 1.85 gigawatts, higher than the previous target of 1.70 gigawatts. CEO Michael Intrator said CoreWeave remains on track to reach at least 8 gigawatts by 2030. Active power capacity has risen 219.15% from the prior year while contracted power stands at 3.7 gigawatts, up 68.2%, and the number of data centers has increased 54.5% to 51.
On valuation, CRWV shares look reasonably valued. The forward P/S and P/CF of 2.63 and 3.28, respectively, are lower than the sector medians of 3.21 and 19.66, respectively.
Analyst Opinion
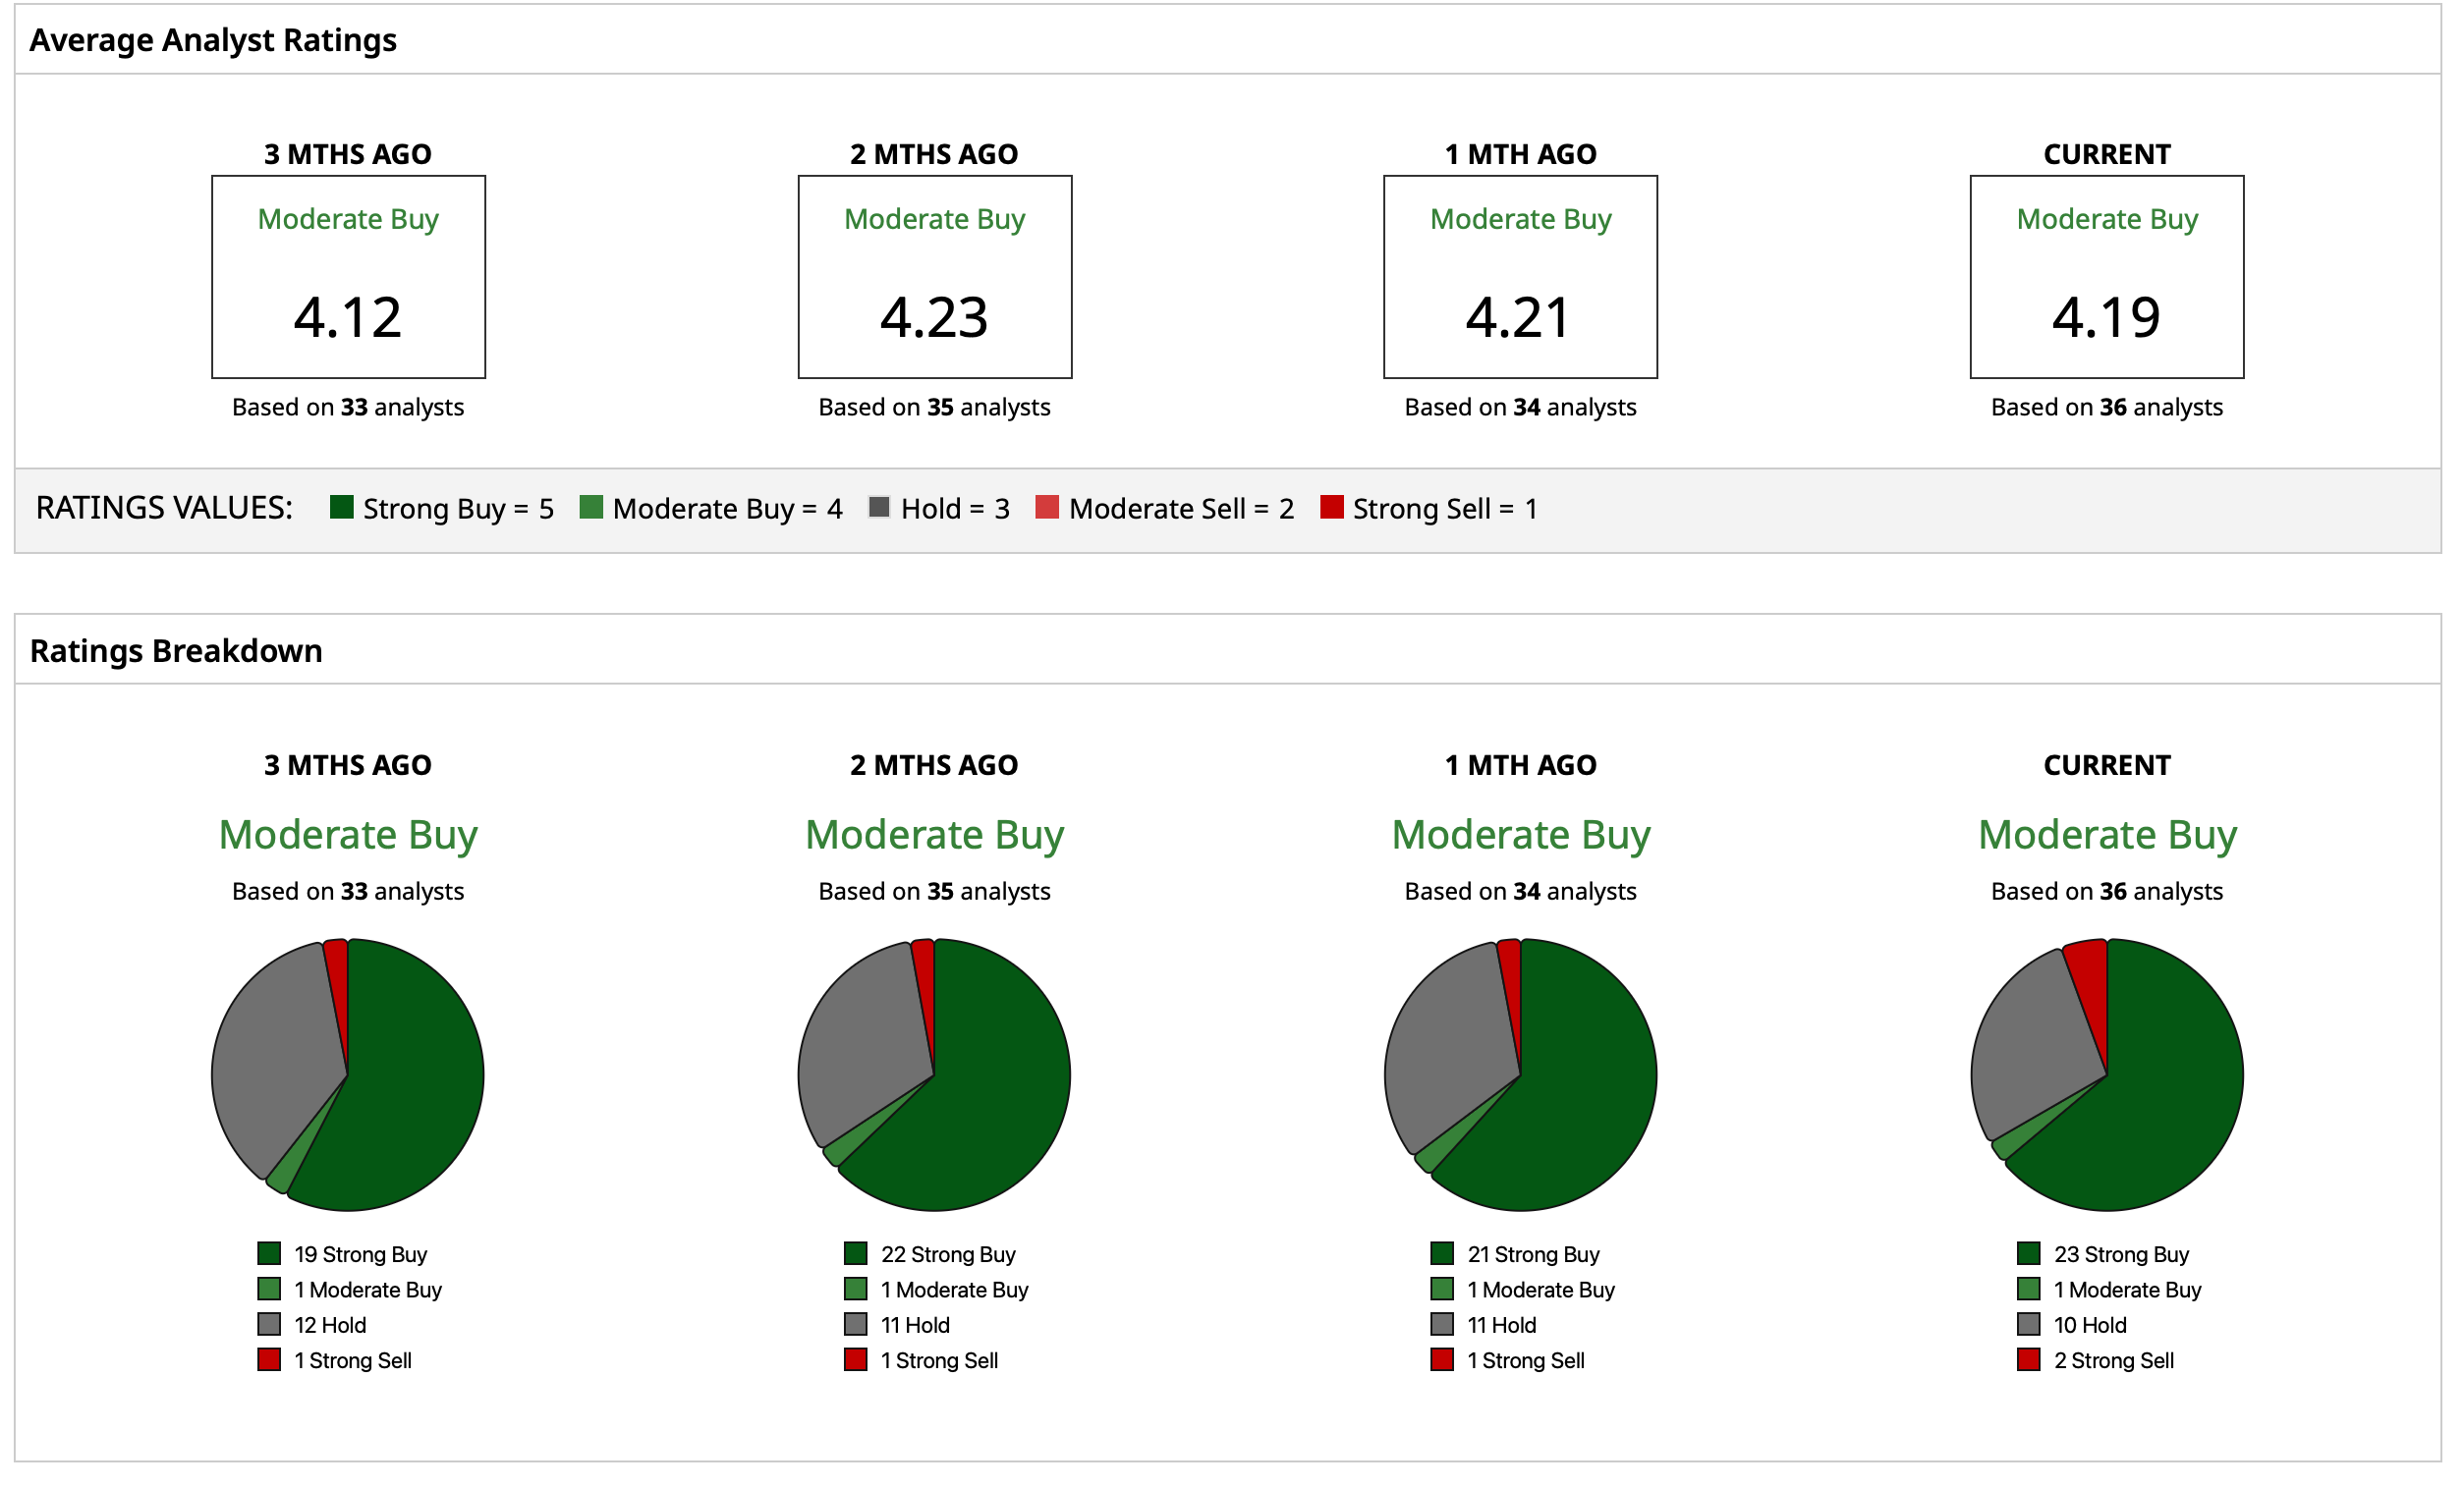
Thus, analysts have assigned an overall rating of “Moderate Buy” for CRWV stock and a mean target price of $136.23. This indicates a potential upside of 121.9% from current levels. Out of 36 analysts covering the stock, 23 have a “Strong Buy” rating, one has a “Moderate Buy” rating, 10 have a “Hold” rating, and two have a “Strong Sell” rating.
On the date of publication, Pathikrit Bose did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.