
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
US Stock Market Today: S&P 500 Futures Rise On Firm Factory And Growth Signals
The Morning Bull - US Market Morning Update Tuesday, Oct, 20 2026
US stocks are set for a constructive open, with index futures pointing higher as investors respond to stronger factory data. The main driver this morning is firmer US industrial activity that signals resilient real economy momentum.
US capacity utilization reached 76.9% in September 2026, the highest since December 2023. Industrial production rose 0.7% month on month, with manufacturing up 0.3%. Together, these numbers suggest steady output and underlying demand.
Stronger utilization and production can help keep pricing power intact and support revenue expectations for producers. At the same time, firmer activity can pressure inflation through import and export prices, which complicates the outlook for borrowing costs and equity valuations.
The open hinges on one question: Does this strength give policymakers room to stay firm on restrictive policy, or will upcoming US housing data and the next Atlanta Fed GDPNow update point to cooling that could soften that stance?
Stocks to Watch Before the Opening Bell
Amazon.com (AMZN)
Amazon is pushing harder into AI chips with TorchNeuron, a tool that lets PyTorch developers shift workloads to its Trainium hardware with minimal code changes. The company also struck a data center supply deal with 3M that includes a US$521.4m warrant tied to up to US$6b of product purchases. Investors may focus on the AWS impact and any disclosure around warrant usage.
Tradeweb Markets (TW)
Tradeweb agreed to buy Trumid Holdings for about US$2.0b, adding an electronic credit trading marketplace to its platform. The transaction links bond issuance and secondary trading across developed and emerging markets. Closing is targeted for the first half of 2027, and management has indicated that the deal is expected to lift adjusted earnings in the first full year after completion.
Southwest Airlines (LUV)
Southwest Airlines reports Q3 2026 results on October 22, with consensus pointing to earnings of US$0.57 per share on US$8.24b in revenue. Recent analyst commentary has turned more cautious around pricing power and cost inflation. The release is likely to provide a clearer read on unit revenue trends, expense control, and the trajectory of profit strength.
Top Movers
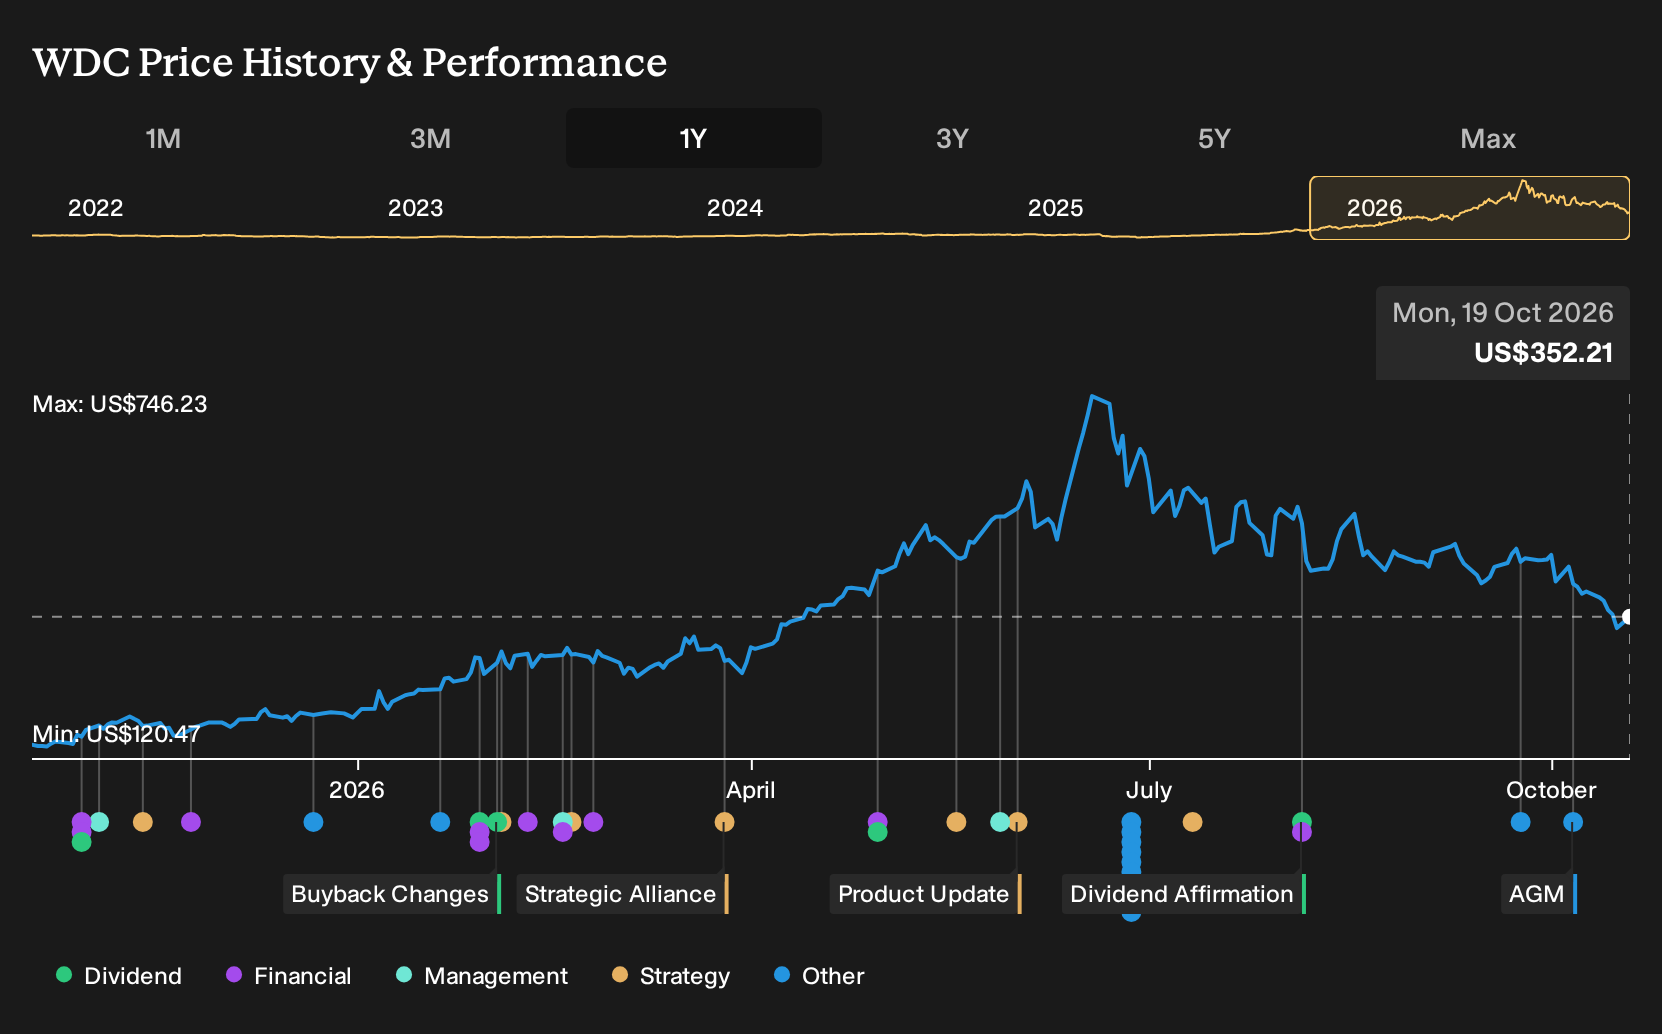
- Western Digital (WDC) climbed 6.09% after a broad chip rebound and easing borrowing costs lifted hardware suppliers.
- Datadog (DDOG) advanced 5.36% after a Bernstein upgrade highlighted stronger AI driven usage and a higher price target.
- Twilio (TWLO) gained 5.29% after BTIG raised its price target and highlighted expectations for inclusion in the S&P 500.
Top Losers
- Cerebras Systems (CBRS) fell 5.15% after objecting to plans for tokenized versions of its shares on OKXICE.
- NRG Energy (NRG) declined 4.21% following price target cuts from Jefferies and Seaport, despite a fresh dividend announcement.
- Ameriprise Financial (AMP) fell 4.07% after a BofA downgrade flagged advisor attrition, retention bonuses, and potential margin pressure.

On The Radar
US housing data and a heavy slate of mega cap earnings sit at the center of the next move for borrowing costs, the dollar, and key equity sectors.
- US Housing Starts and Building Permits, Tue 20 Oct. The market is looking for 1.31m housing starts and 1.40m permits annualized. Any weaker print would point to more pressure on builders and could ease expectations for higher US mortgage costs.
- US Pending Home Sales, Tue 20 Oct. Consensus sits at a 0.5% decline on the month and a 1.0% rise year on year. A stronger result would underline buyer demand and support construction related stocks even as rates stay elevated.
- Atlanta Fed GDPNow, Tue 20 Oct. The Q3 estimate was last at 3.6%. A clear move away from that mark would shift views on how restrictive current policy feels for US growth sensitive shares.
- Netflix (NFLX) Q3 results, Tue 20 Oct. Subscription trends and revenue guidance will give a direct read on streaming appetite and advertising budgets, which matters for how investors treat high multiple communication and media stocks.
- Tesla (TSLA) and Meta Platforms (META) Q3 earnings, Wed 21 Oct. Profit margins and any change in spending plans will help set the tone for how traders treat capital intensive tech and auto groups after the recent focus on higher funding costs.
Sector & Industry Watch
Tech: Strong year, shaky recent stretch
Tech has given back ground over the past week, with a 7 day return of about 4.7% in the red even though the year to date figure is still firmly positive. Investors are weighing big AI headlines, from Quantinuum’s quantum error work to Microsoft’s chip funding links, against higher rate expectations that make long dated earnings less comfortable.
If you own broad Tech ETFs or large US software and hardware stocks, keep an eye on today’s Atlanta Fed GDPNow update. A firmer growth read can lift Treasury yields, which often pressures sectors that rely heavily on future cash flows for their appeal.
Semiconductors: AI supply chain meets funding worries
Semiconductors have been hit harder than Tech overall, with the group off roughly 6.6% over 7 days while still showing very strong year to date and 1 year numbers. Stories around CoreWeave’s higher borrowing costs, Nvidia’s large data center chip deals and fresh equipment orders for companies like Lam Research and ACM Research underline how much current demand depends on financed AI buildouts.
If your portfolio leans on chip designers, materials or equipment makers, focus on this week’s earnings from AI hungry customers such as Tesla and the broader Big Tech group. Any change in tone on AI infrastructure plans or funding costs can quickly reset expectations for how steady chip orders feel over the next few quarters.
Energy & Oil and Gas: Higher fuel prices support sector earnings
Energy and Oil and Gas continue to trend the other way, with Energy up about 2.0% and Oil and Gas ahead roughly 2.4% over the last week on top of already large 1 year gains. Firm import price data for fuel and headlines around LNG shipping risk and Brent trading high keep attention on producers like Chord Energy and Centrus Energy that are tied to oil, gas and related infrastructure.
For anyone holding energy sector funds or individual oil and gas stocks, tonight’s API crude estimate and tomorrow’s EIA inventory report are the key milestones. Another sizeable draw in crude or gasoline stocks would fit the story of a tight market, which supports cash generation for the sector even as higher fuel bills squeeze households and travel linked industries.
Real Estate: Higher mortgage rates still a headwind
Real Estate has eased about 0.6% over the past 7 days and is also softer over 30 days, with only a small positive 1 year return. A US 30 year mortgage rate near 7.5% keeps financing expensive for buyers and developers, which can weigh on transaction volumes, new projects and refinancing terms for REITs even as deals like Newmark’s affordable housing financing show selective capital still flowing.
If you hold property ETFs or housing related stocks, today’s run of US Housing Starts, Building Permits and Pending Home Sales deserves attention. Weak readings would confirm that borrowing costs remain a brake on construction and sales, which matters for occupancy, rent trends and how easily property owners can roll debt in coming years.
Consumer Staples & Food, Beverage & Tobacco: Everyday spending offers relative steadiness
Consumer Staples and Food, Beverage & Tobacco have been more resilient, with 7 day gains of around 3.7% and 3.2% and positive 1 year performance. Companies from Walmart and Central Garden & Pet to Mondelēz and Dole are active with bond deals, acquisitions and new product launches, reflecting demand tied to day to day spending rather than big ticket items like homes or cars.
If you use these sectors as ballast alongside more volatile holdings such as Tech or Airlines, listen for how management talks about input costs and pricing in the coming earnings reports. September import and export price data showed fuel driven pressure, so any comments on freight, food commodities and packaging will help you judge how much pricing power remains without pushing shoppers to trade down or cut back.
Don't Wait For The Winners, Find Them
With US 30 year mortgage rates near 7.5% and pressure still showing in real estate and housing data, stress test your exposure against this list of 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com