
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mattel (MAT) Names A New CFO As Fair Value Debate Heats Up
Mattel (MAT) just reshuffled its top financial seat and boardroom at the same time, appointing Peter Griffith as chief financial officer and non independent director following the resignation of Adriana Cisneros.
Over the past month Mattel’s shares have rebounded sharply, with a 30 day share price return of 27.30% and a 90 day gain of 18.87%. However, the longer term picture remains softer, with the 1 year total shareholder return down 8.11% and the 5 year total shareholder return down 16.02%. This suggests that recent takeover speculation and fresh leadership headlines are building momentum on a still weak multi year record.
Scan how the Mattel story compares with other potential targets riding takeover talk and leadership shakeups by checking our hand picked 20 high quality undiscovered gems in similar situations.
Mattel has just surged on takeover talk and a fresh CFO, yet longer term returns are still in the red. Does it make more sense to lean into this spike now, or wait for a cooler entry based on the numbers?
Most Popular Narrative: 36.6% Undervalued
Mattel's most followed narrative pegs fair value at $26.61 against the last close of $16.88, which frames the recent rally as only part of the story.
Management’s decision to treat 2026 as an investment year, with about US$150 million of extra OpEx and heavier advertising to build capabilities in areas such as digital games, building sets, trading cards and first party data, creates room for a sharper operating income inflection in 2027 than simple linear models may assume.
See why 3 investors see Mattel as 37% undervalued.
Result: Fair Value of $26.61 (UNDERVALUED)
Still, the Mattel thesis can unravel quickly if earnings volatility keeps investors focused on recent misses or if the Infant, Toddler and Preschool drag lasts longer.
Find out about the key risks to this Mattel narrative.
Another View: Mattel Through A Cash Flow Lens
The bullish fair value of $26.61 leans on optimistic earnings paths and higher future P/E assumptions. A simpler check using our DCF model tells a different story. Mattel at $16.88 is slightly above the SWS DCF estimate of $16.51, which points to a stock that screens as mildly overvalued on cash flows today. So which story do you trust more, the narrative premium or the spreadsheet math?
To see how those cash flow assumptions are built into the model, and where they might feel either conservative or stretched for Mattel, Look into how the SWS DCF model arrives at its fair value..
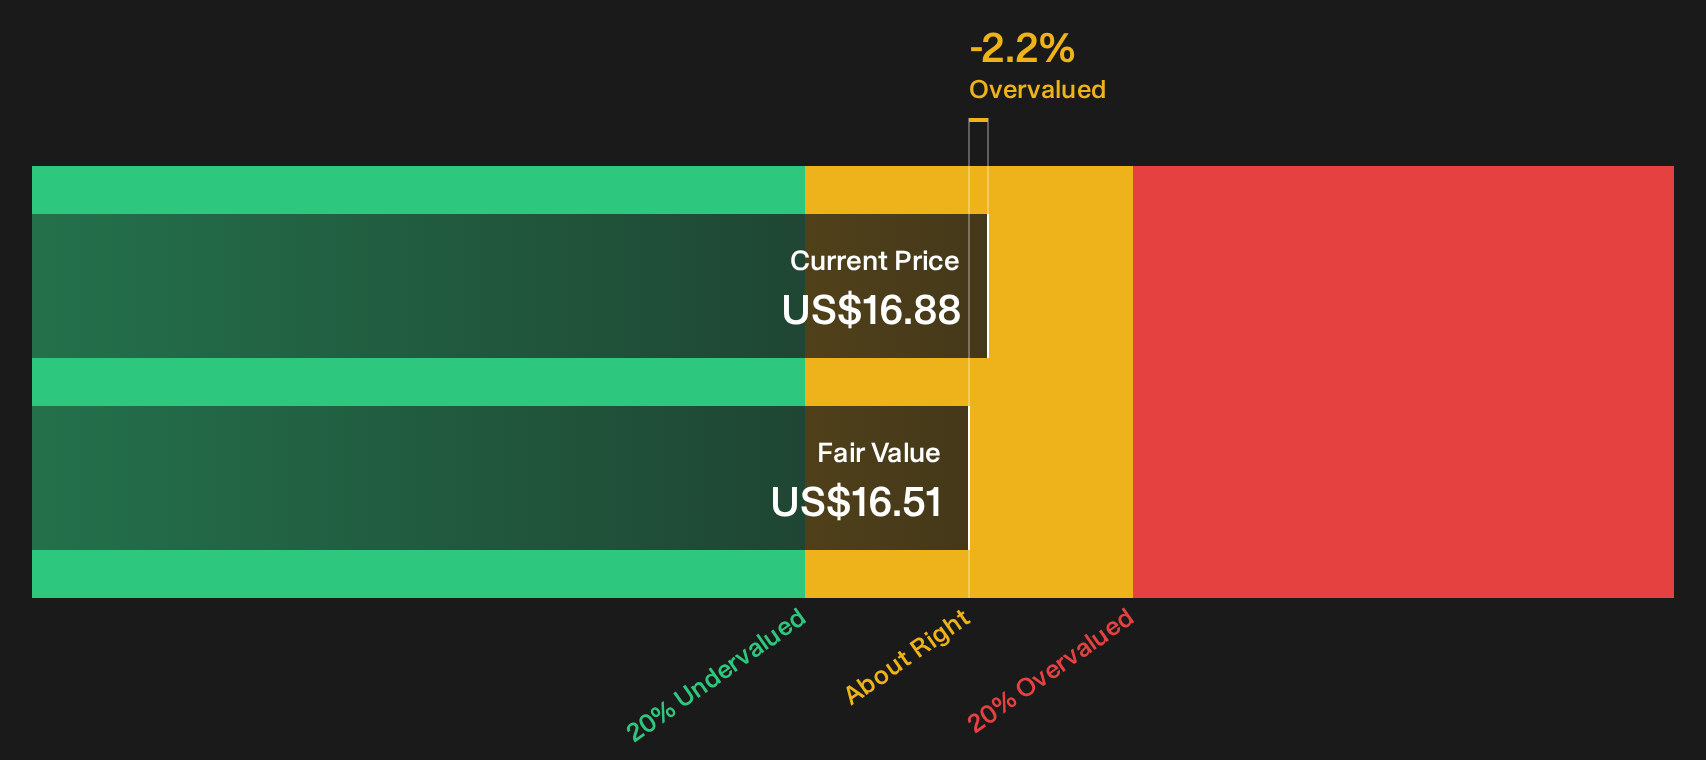
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mattel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mattel so far, with fresh leadership, takeover noise and a split between cash flow math and optimism around future rewards and risks. Act while the data is fresh and pressure test the story yourself by reviewing the 2 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Mattel?
Do not stop your work at Mattel. Round out your watchlist with a few targeted hunting grounds that surface different types of opportunities using the Simply Wall St screener.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that highlights businesses with robust financial footing and room to handle surprises.
- Hunt for mispriced potential through a 35 high quality undervalued stocks that brings together quality companies trading below their estimated worth.
- Prioritise staying power with a 32 resilient stocks with low risk scores that focuses on stocks scoring well on stability and downside control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com