
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bright Smart Securities & Commodities Group (SEHK:1428) Faces Earnings Quality Questions, Is Its P/E Fully Valued?
Recent scrutiny of Bright Smart Securities & Commodities Group (SEHK:1428) has focused on its earnings quality as the share price comes under pressure. Investors are weighing brokerage, margin lending, and commission income against a contested P/E valuation.
Over the past year, Bright Smart Securities & Commodities Group has seen its share price come under pressure, with a year to date share price return down 27.71% and a 30 day share price return down 13.78%, even though the 3 year total shareholder return is very large at more than 4x. That mix of weaker recent share price momentum alongside a significant multi year total shareholder return suggests some investors are reassessing the risk around its brokerage and margin lending earnings, while others are still anchored to the longer track record.
Scan how Bright Smart Securities & Commodities Group stacks up against other potential value ideas by comparing it with our hand picked 199 high quality undervalued stocks.
Bulls point to Bright Smart Securities & Commodities Group’s very large three year return and earnings profile, while bears focus on the sharp recent slide. Which side does the current P/E and profit mix appear to support at this stage?
Preferred P/E of 15.5x: Is it justified for Bright Smart Securities & Commodities Group?
On a simple P/E basis, Bright Smart Securities & Commodities Group trades at 15.5x earnings, which screens as cheaper than peers on one measure and richer on another. The shares last closed at HK$6.13, and investors are weighing whether that earnings multiple still lines up with the recent pressure on the stock.
The P/E ratio links the HK$6.13 share price to the company’s profit, essentially telling you how many Hong Kong dollars the market is willing to pay for each dollar of earnings. For a brokerage and margin lending focused group like Bright Smart Securities & Commodities Group, that metric often reflects how durable investors think commission, financing, and trading related income will be across a full cycle.
Relative to its directly selected peer group, the stock is described as good value, with a 15.5x P/E compared with a peer average of 20.3x. That implies the market is applying a lower price tag to each dollar of earnings than those peers, even though earnings have grown 0.1% per year over the past 5 years and rose 8.5% over the last year, and net profit margins of 58.4% are higher than the 54.1% level reported a year earlier.
The picture shifts when you set that same 15.5x P/E against the wider Hong Kong Capital Markets industry, where the average multiple is 8.8x. In that broader context, Bright Smart Securities & Commodities Group is described as expensive, which suggests the market is attaching a higher price to the earnings stream than for many other capital markets companies, possibly because of factors such as its very large three year total shareholder return, high reported Return on Equity of 30.86% that is affected by leverage, or the group’s revenue mix across securities, futures, and commodities broking.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 15.5x (ABOUT RIGHT)
Still, the reliance on brokerage and margin related income leaves Bright Smart Securities & Commodities Group exposed if trading activity or client appetite for leverage weakens.
Find out about the key risks to this Bright Smart Securities & Commodities Group narrative.
Another view on Bright Smart Securities & Commodities Group’s value
The earnings multiple presents Bright Smart Securities & Commodities Group as roughly fairly pitched, yet the SWS DCF model offers a different perspective. At HK$6.13, the stock is described as trading 50.5% below an estimated future cash flow value of HK$12.38. Which signal should carry more weight when profits wobble?
Look into how the SWS DCF model arrives at its fair value.
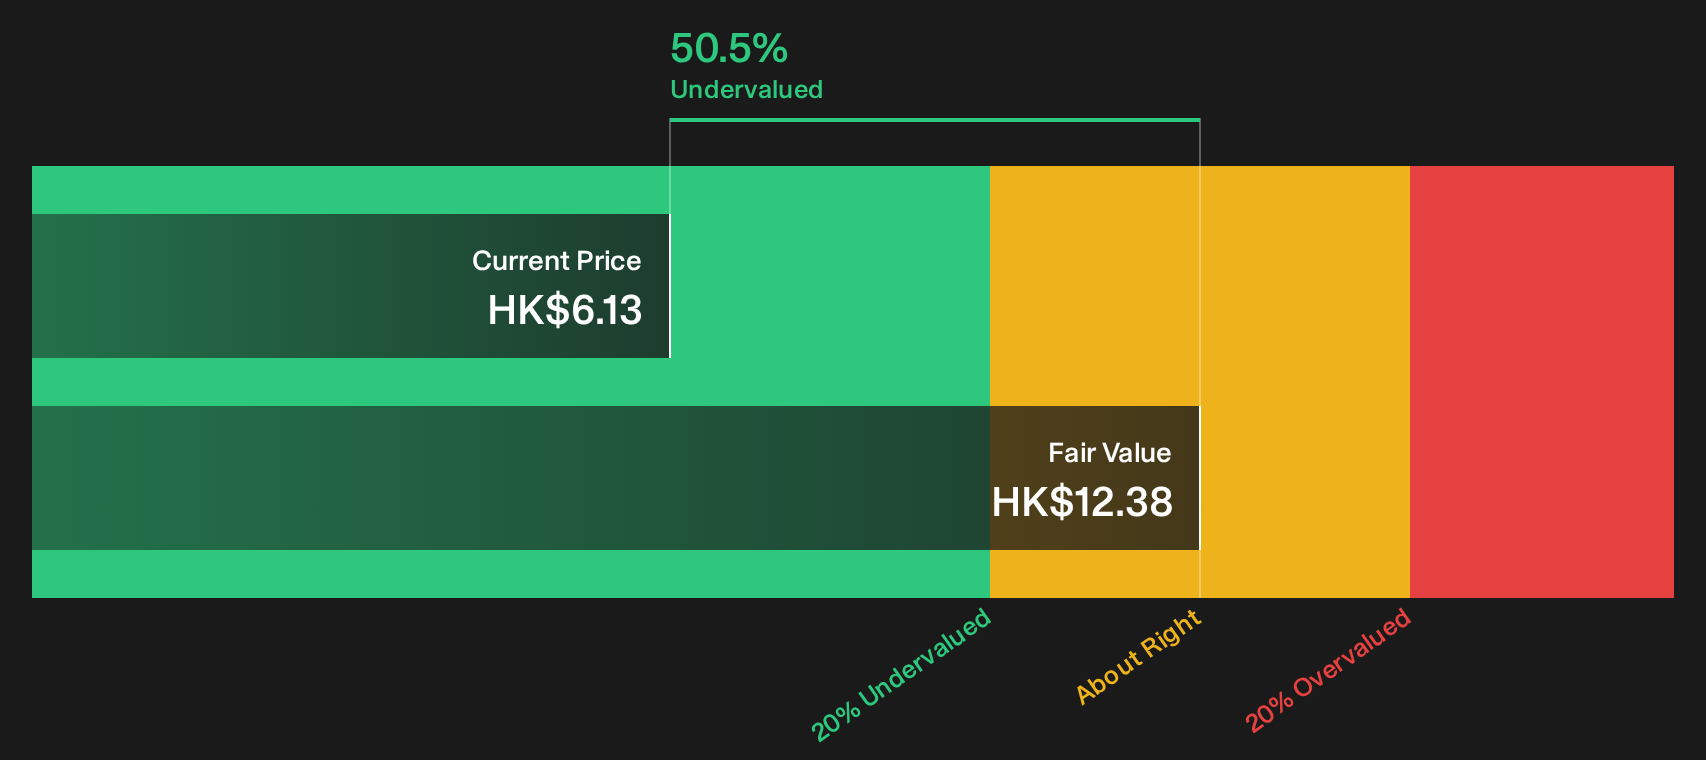
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bright Smart Securities & Commodities Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Bright Smart Securities & Commodities Group can easily push sentiment in either direction, so it helps to inspect the numbers and risk flags directly. If you want a clearer feel for both sides of the story, weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Bright Smart Securities & Commodities Group?
If you stop with Bright Smart Securities & Commodities Group alone, you might miss opportunities that better match your style, risk comfort, and income goals.
- Target punchy upside potential by scanning focused 132 elite penny stocks with strong financials that pair smaller size with stronger balance sheets than many investors expect.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (202 results) so you can tilt toward companies built to handle tougher conditions.
- Build a steadier income stream by reviewing a 220 dividend fortresses that filters for higher yields and financial resilience in one place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com