
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Lovelytics Deal Require Action From CDW (CDW) Investors?
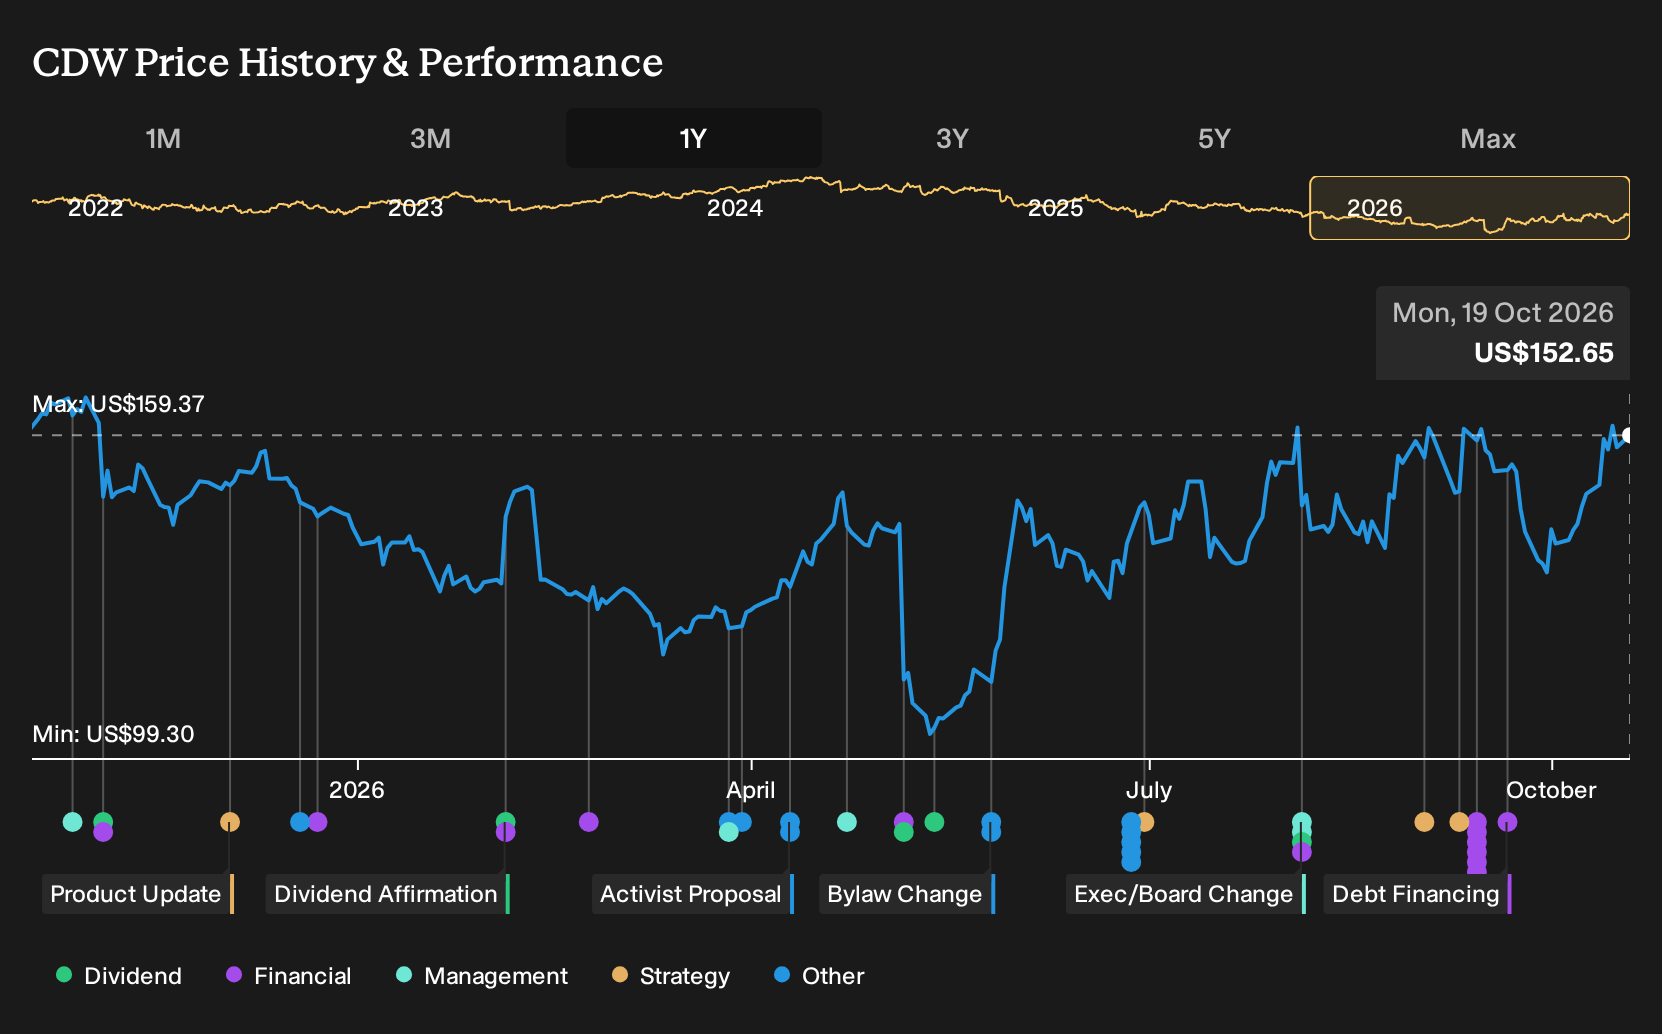
- CDW recently added former Deloitte Consulting & Advisory Global CEO Sam Balaji to its board and closed the Lovelytics acquisition, expanding its data, analytics, and AI capabilities ahead of the pending fiscal Q3 2026 earnings release.
- The Lovelytics deal gives CDW a larger bench in analytics and AI services, which speaks directly to customer demand for end to end digital transformation projects rather than one off hardware refreshes.
- We will now examine how CDW's investment narrative could shift as Lovelytics expands its AI and analytics services capabilities.
Scan how CDW's AI and analytics push compares with other potential breakouts by reviewing a curated group of 55 AI infrastructure stocks in the same technology buildout story.
CDW Investment Narrative Recap
To own CDW, you need to believe it can keep turning demand for AI, cloud and security projects into higher quality, services rich revenue while managing margin pressure from large infrastructure deals. The near term swing factor is how efficiently that written business converts from backlog into invoiced projects without further squeezing gross margin.
The biggest risk is that services growth and cash conversion stay muted. Gross margin already sat below last year and free cash flow trailed management’s target because of inventory build. The Lovelytics acquisition and internal AI focus may help over time, but the impact on mix and margins around the upcoming Q3 print still looks modest.
The Lovelytics deal is the clearest operational link to CDW’s current catalyst story. It adds hundreds of data and AI specialists, which gives the company more capacity to bid for end to end projects that include architecture, deployment and ongoing management, not just hardware rollouts. That matters if customers start prioritizing full solutions over one off refreshes.
Execution risk rises with this shift. Management has to convert that extra AI and analytics bench into recurring services, a better gross profit mix and eventually stronger free cash flow, while still supporting infrastructure heavy customers. Analyst expectations for earnings growth and higher future margins only hold up if this transition outpaces the drag from lower margin hardware and elevated debt.
CDW's current analyst narrative points to US$26.5b of revenue and US$1.4b of earnings by 2029, built on an annual revenue growth assumption of 4.0% and an earnings increase of about US$300m from the US$1.1b reported today.
Uncover why CDW's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest CDW forecasts lean heavily on the risk that AI projects stall at hardware, with consulting and managed work never fully kicking in. Those analysts were penciling in about US$25.8b of revenue and US$1.4b of earnings by 2029. With Sam Balaji and Lovelytics now in the mix, those views may be revisited.
Explore 4 other CDW fair value estimates, including one that suggests as much as 29% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CDW research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CDW. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CDW's overall financial health at a glance.
Looking for more CDW-sized investment ideas?
Once you have a view on CDW, it can help to line it up against other potential opportunities so your watchlist is built on clear trade offs rather than headlines.
- If you want a wider margin of safety baked into the story, scan a curated set of 35 high quality undervalued stocks that pair stronger fundamentals with more conservative pricing.
- For investors who care most about resilience, stress test your income stream against a 32 resilient stocks with low risk scores that focuses on businesses with sturdier financial risk profiles.
- When you prefer quality balance sheets first and everything else second, use the list of solid balance sheet and fundamentals (25 results) as a starting universe before doing your own deep work.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com