
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Adient (ADNT) Draws Value Attention, Is The Turnaround Already Priced In?
Recent market commentary has pushed Adient (ADNT) into focus, as analysts highlight what they view as comparatively attractive valuation metrics and a stronger earnings outlook compared with other automotive suppliers.
At around US$17.60 per share, Adient has seen the 90-day share price return fall 11.65%, while the year-to-date share price return is down 7.56% and the 1-year total shareholder return is down 24.20%. This points to fading momentum even as recent earnings expectations and valuation commentary have started to draw fresh attention to the stock.
Compare Adient's recent pullback with a curated set of value opportunities by scanning 35 high quality undervalued stocks, which share solid fundamentals and may be priced below what their businesses appear to justify.
So is Adient’s slide a verdict on the business itself, or more a case of sentiment resetting around an out of favor auto supplier, and what does that gap mean for valuation work from here?
Most Popular Narrative: 40.4% Undervalued
Adient’s most followed valuation storyline pegs fair value around $29.55, well above the recent $17.60 close. This puts the current slide against a much richer narrative about backlog, automation spending, and margin repair work.
Americas onshoring wins, including incremental volumes on Chevrolet Equinox and Volkswagen programs along with an estimated US$400 million backlog for FY27 and US$630 million for FY28, combined with the added Romulus foam plant, point to future revenue growth and a potential uplift in regional earnings as higher margin vertically integrated components scale.
See why 5 investors see Adient as 40% undervalued.
Result: Fair Value of $29.55 (UNDERVALUED)
Still, the Adient story hinges on EMEA restructuring and China mix not biting harder, since higher restructuring cash costs or deeper margin compression could quickly challenge that 40.4% undervalued narrative.
Find out about the key risks to this Adient narrative.
Another View: What Adient’s P/E Is Saying
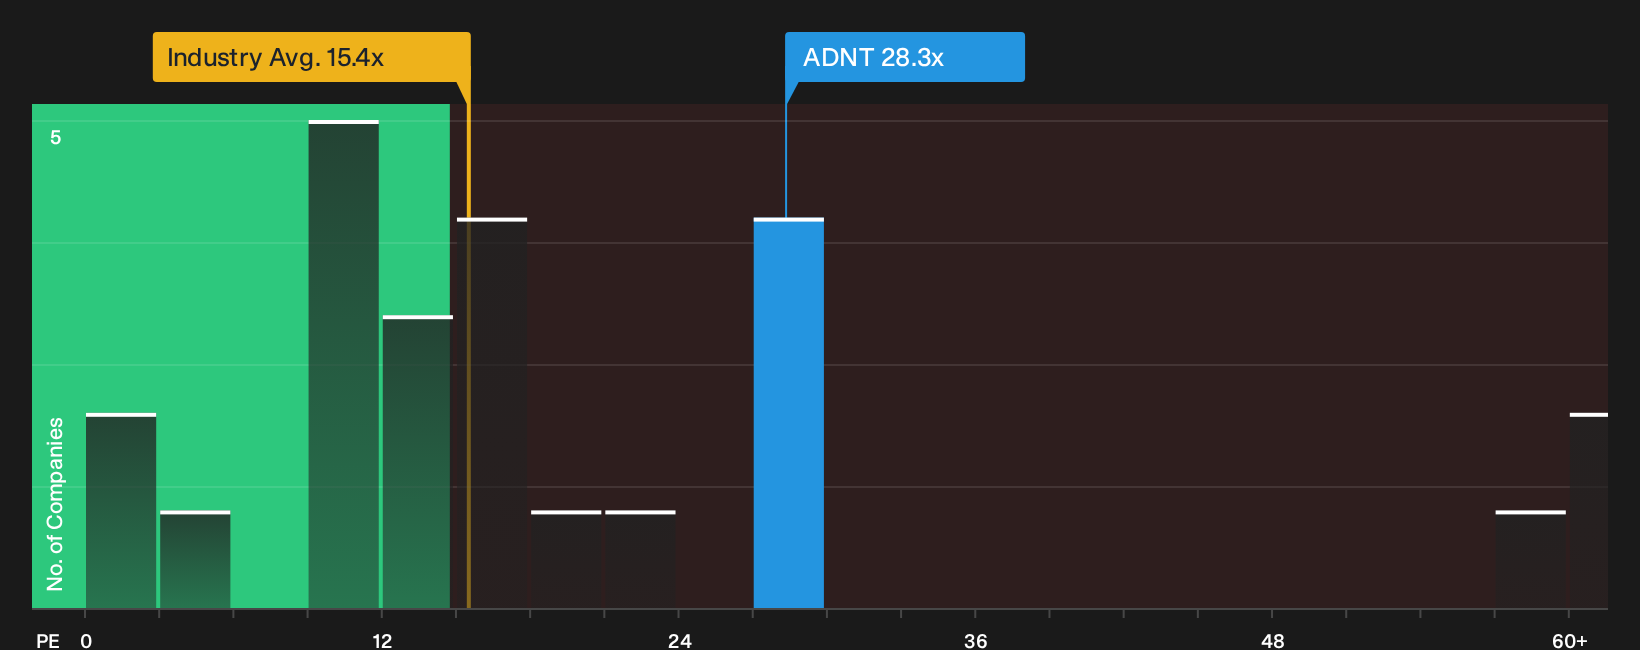
There is a very different message coming from Adient’s current earnings multiple. The stock trades on a P/E of 28.3x, which is higher than both the US Auto Components industry on 15.7x and a fair ratio estimate of 25.8x. That points to investors already paying up for the earnings that exist today, which raises the question of how much room is left if the margin story takes longer than expected.
For a closer look at how this valuation gap could matter for future returns, including peer comparisons and the fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Adient can feel messy, so it may be worth moving quickly, reviewing the underlying figures yourself and weighing up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Adient?
If Adient has caught your attention, use that momentum and line up a few more candidates so you are not relying on a single turnaround story.
- Scan for potential mispricings by reviewing the 35 high quality undervalued stocks that pair solid fundamentals with valuations that may not fully reflect their underlying businesses.
- Focus on stability and sleep-better-at-night balance sheets by checking the list of solid balance sheet and fundamentals (25 results) that can help anchor a more resilient portfolio.
- Hunt for less crowded opportunities by reviewing the 20 high quality undiscovered gems before the wider market starts paying closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com