
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vistra (VST) Could Be 15% Overvalued After AI Power Deals And Preferred Redemption
Vistra (VST) has moved into focus after media coverage linked its long-term AI power deals, including a 20 year nuclear agreement with Meta, to its recent redemption of $1b in Series A preferred stock.
Recent trading has cooled some of the enthusiasm around Vistra, with the share price down 5.33% over the past week and 9.40% year to date, even after a 6.42% 1 month share price return and a very large 5 year total shareholder return. Investors appear to be weighing the long dated AI related power contracts and the preferred stock redemption against shorter term volatility. This volatility can reflect shifting views on both growth potential from data center demand and changes in perceived risk around capital allocation and future cash flows.
Scan how Vistra fits into the broader AI power build out by comparing it with our hand picked 42 power grid technology and infrastructure stocks shaping tomorrow's electricity infrastructure.
Vistra now trades at a steep discount to both analyst targets and some intrinsic value estimates after redeeming its 8.0% preferred layer. Is that a bargain, or is the market correctly flagging risk in those long AI power deals?
Most Popular Narrative: 15% Overvalued
Against the last close of $149.70, the most followed narrative pegs Vistra’s fair value at about $130. This view treats today’s price as already baking in a big portion of the AI power story and long term electricity demand, even after the recent pullback.
My original $291.87 estimate gave too much value to growth without charging enough for the capital required to create it. So I corrected it. Then I discovered that global electricity demand may be entering a regime we have not seen in decades. So I corrected my thinking again.
See why 87 investors see Vistra as 15% overvalued.
According to John_Eric, the updated fair value of roughly $130 comes from treating growth as expensive, capital intensive work rather than a free byproduct of AI hype or data center demand. That means higher expected spending on nuclear uprates, gas capacity and grid connections plus more normal cash taxes and a return requirement that reflects Vistra’s sizeable debt load.
The same narrative also flags that this more cautious valuation sits in a noisy debate. Several analysts quote higher price targets, some large investors have built sizeable positions, and management has made insider purchases around the mid $130s. That mix leaves the market with a wide spread of outcomes, and puts extra weight on how future power prices and long dated contracts actually translate into free cash flow per share.
Result: Fair Value of $130 (OVERVALUED)
Still, the Vistra story can break if long term AI power demand underwhelms, or if heavy capital needs squeeze free cash flow harder than expected.
Find out about the key risks to this Vistra narrative.
Another View: What Vistra’s P/E Is Telling You
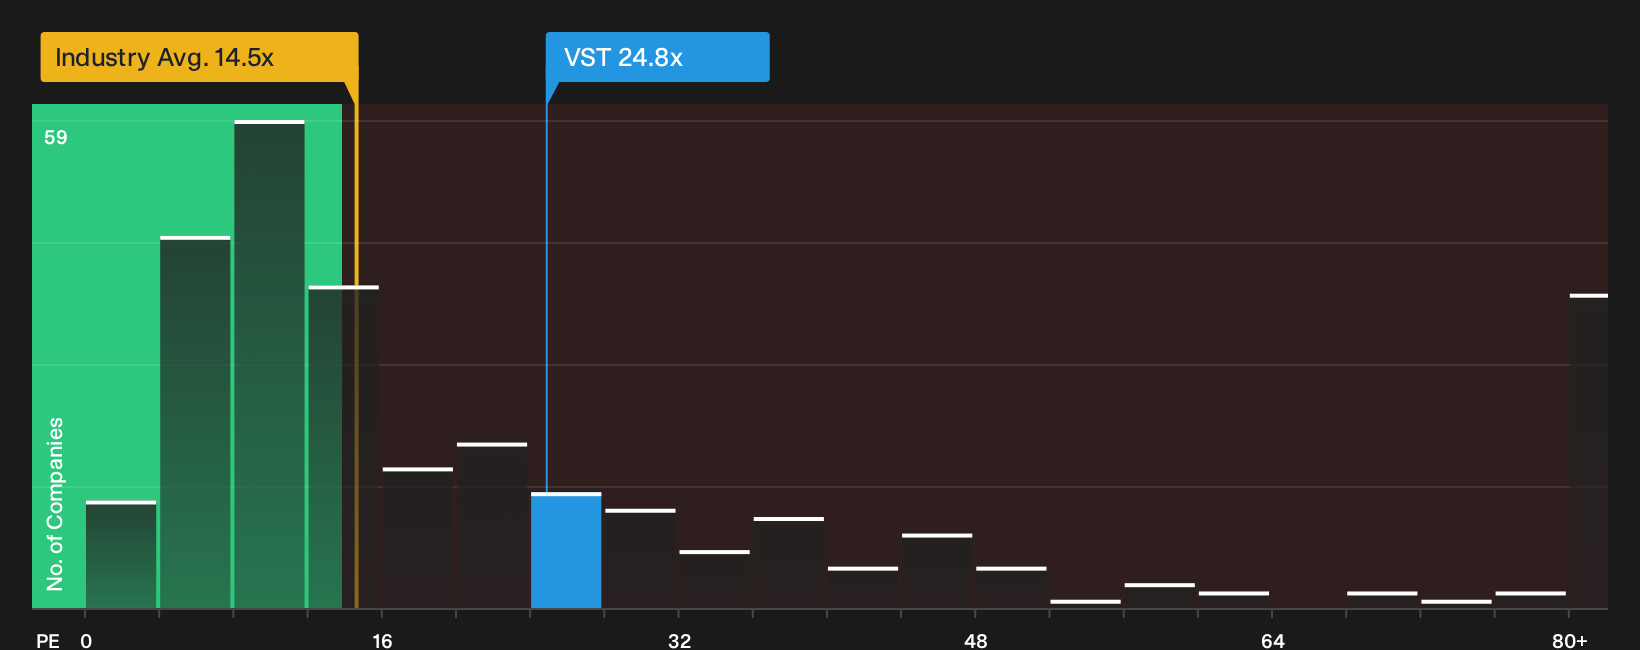
The SWS DCF work points to Vistra being deeply undervalued on future cash flows, yet the current P/E of 24.8x paints a different picture. That multiple is higher than both peer averages of 17.7x and the Global Renewable Energy group at 14.5x. It also sits below the fair ratio of 28.3x.
In other words, the stock appears inexpensive when evaluated against a cash flow model, but relatively expensive when compared with sector and peer earnings multiples. When real money is on the line, which reference point should carry more weight: the discounted cash flow view or the earnings-based comparison that the wider market often watches first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Vistra story today. Act quickly, stress test the bullish and cautious arguments against the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Vistra?
Vistra might be front of mind today, but your next strong idea could come from a very different corner of the market. Do not leave potential opportunities sitting on the sidelines when a few focused screens can broaden your watchlist fast.
- Target higher potential income streams by reviewing companies with resilient payouts and balance sheets through our 8 dividend fortresses.
- Hunt for quality at a discount by scanning financially robust businesses that trade below estimated worth using the 35 high quality undervalued stocks.
- Protect your downside first and look across companies with steadier risk profiles using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com