
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Gold.com (GOLD) Ahead Of Earnings
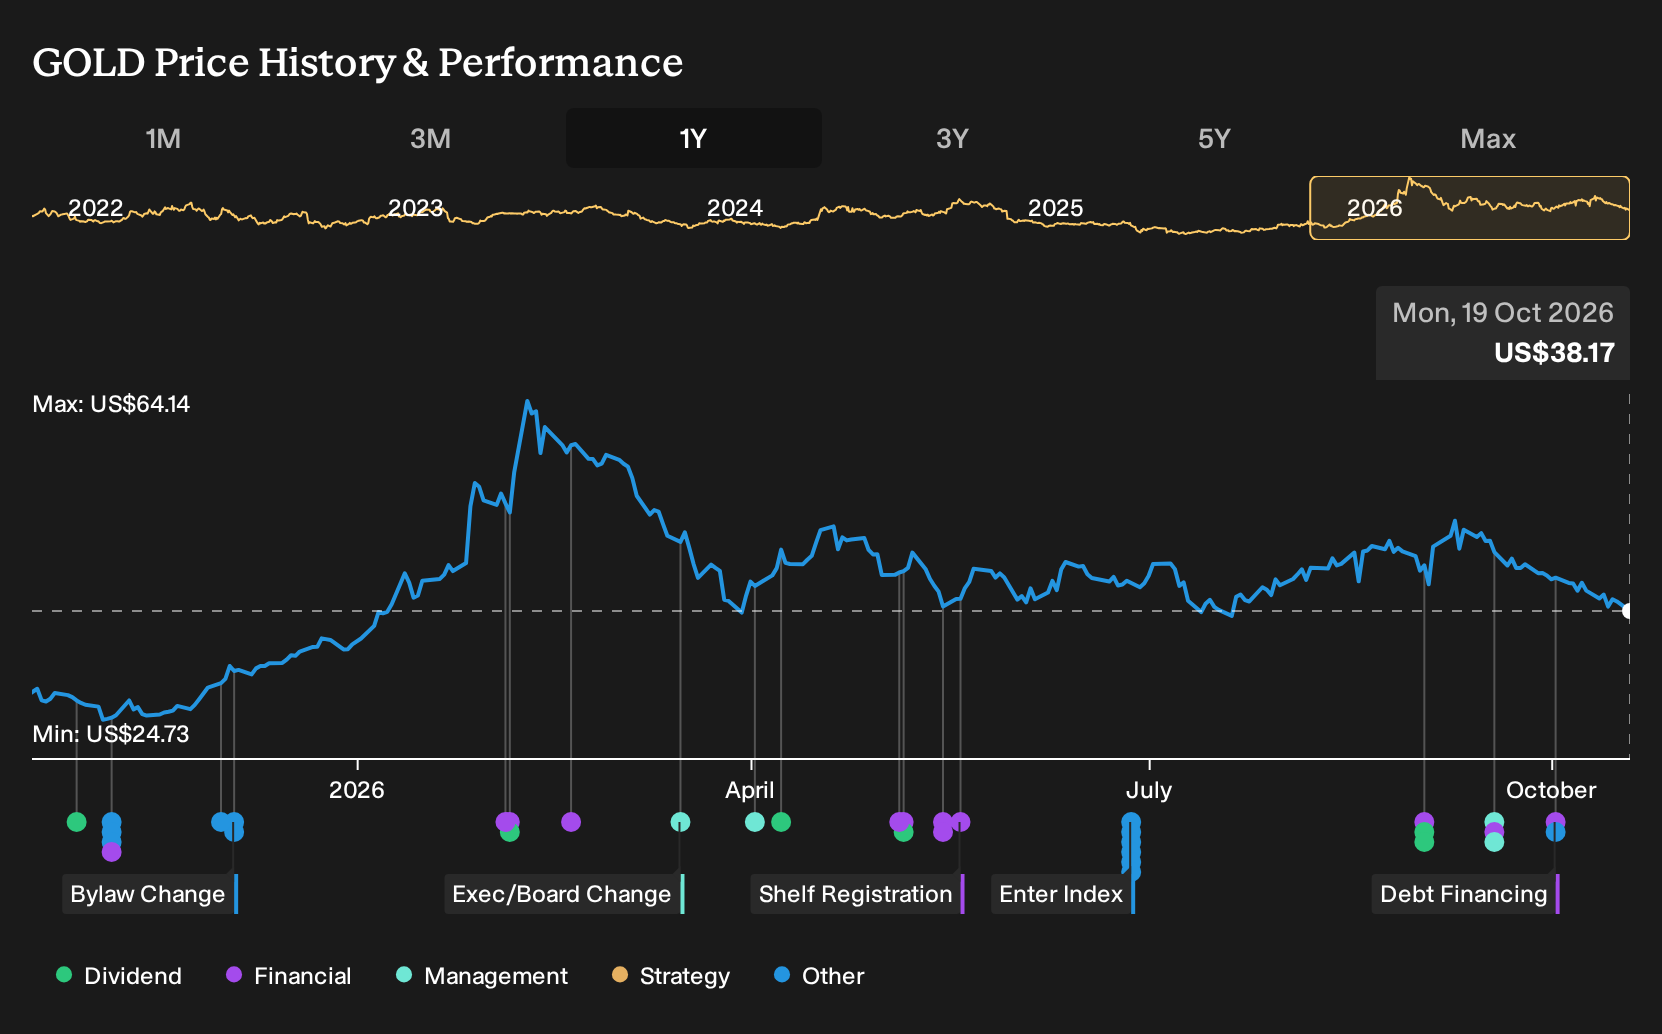
- Gold.com shares fell around 3% over the past week as investors focused on the upcoming earnings release that is expected to show higher EPS and revenue compared with last year.
- The pullback highlights how closely the market is watching Gold.com’s ability to translate its larger platform into stronger profitability at a time when analysts carry a favorable Zacks Rank #2 rating as supporting context.
- We will examine how Gold.com’s broader investment narrative is shaped by the upcoming earnings release and heightened focus on profitability.
Compare Gold.com’s setup ahead of earnings with a hand-picked group of peers using the 35 high quality undervalued stocks that already clear high bars on cash flows and balance sheets.
Gold.com Investment Narrative Recap
To own Gold.com, you need to be comfortable with a metals and collectibles platform that is already large on revenue but thin on net margin. The near term story hinges on whether this bigger footprint from acquisitions can show up in cleaner earnings. The recent 3% share price drop ahead of results does not change that core question. It just sharpens the market’s focus.
The key short term catalyst is the earnings print and any detail on gross margin, SG&A discipline and cross selling across acquired units. The biggest risk is that integration, mix shift and higher operating costs keep compressing margins. If that happens, even healthy trading volumes and customer activity may not translate into stronger profitability.
Recent acquisitions such as Sunshine Mint, SGI, Pinehurst, AMS and Monex already feed into Gold.com’s larger production capacity and revenue base. What matters now is how management talks about integration progress, cost systems and operational efficiencies in the upcoming release. You want to see evidence that this bigger platform is becoming easier, not harder, to run profitably.
Those deals, plus the deepening link with Tether, sit directly in the path of current catalysts around earnings quality and mix. The Tether stake, metal leasing and the XAUT position tie physical bullion to digital assets and can influence storage balances and trading flows. That creates both opportunity and execution risk, particularly if lending, gamified retail platforms and Costco bullion channels scale faster than internal controls and margin oversight.
Gold.com's current analyst storyline points to revenue of US$24.3b and earnings of US$171.3m by 2029, built on an assumed yearly top line decline of 1.6% and an earnings increase of about US$89m from US$82.3m today.
Uncover why Gold.com's fair value signals a 69% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
You might see Gold.com very differently if you focus on one optimistic twist: the shift toward fee and interest income. The most bullish analysts were penciling in revenue of US$27.0b and earnings of US$221.8m by 2029 before this 3% drop. That outlook could easily be revised once the new results land.
Explore 5 other Gold.com fair value estimates, including one that suggests as much as 136% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Gold.com research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gold.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Gold.com's overall financial health at a glance.
Looking for more investment ideas beyond Gold.com?
If the Gold.com story has you thinking about portfolio upgrades, it can help to line it up against other opportunities that already clear specific quality or income thresholds. The Simply Wall St Screener gives you a quick way to find stocks that fit the type of risk and reward profile you actually want to own.
- If capital preservation and a steadier ride matter most to you, start with a group of 32 resilient stocks with low risk scores that already screen well on resilience and lower risk scores.
- If you want income to do more of the heavy lifting, filter for companies in the 8 dividend fortresses that pair higher yields with an emphasis on durability.
- If you prefer to hunt for potential future leaders before the crowd pays attention, scan through the 20 high quality undiscovered gems and focus on businesses with fundamentals that already look solid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com