
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To United Therapeutics Stock FDA Trial Clearance
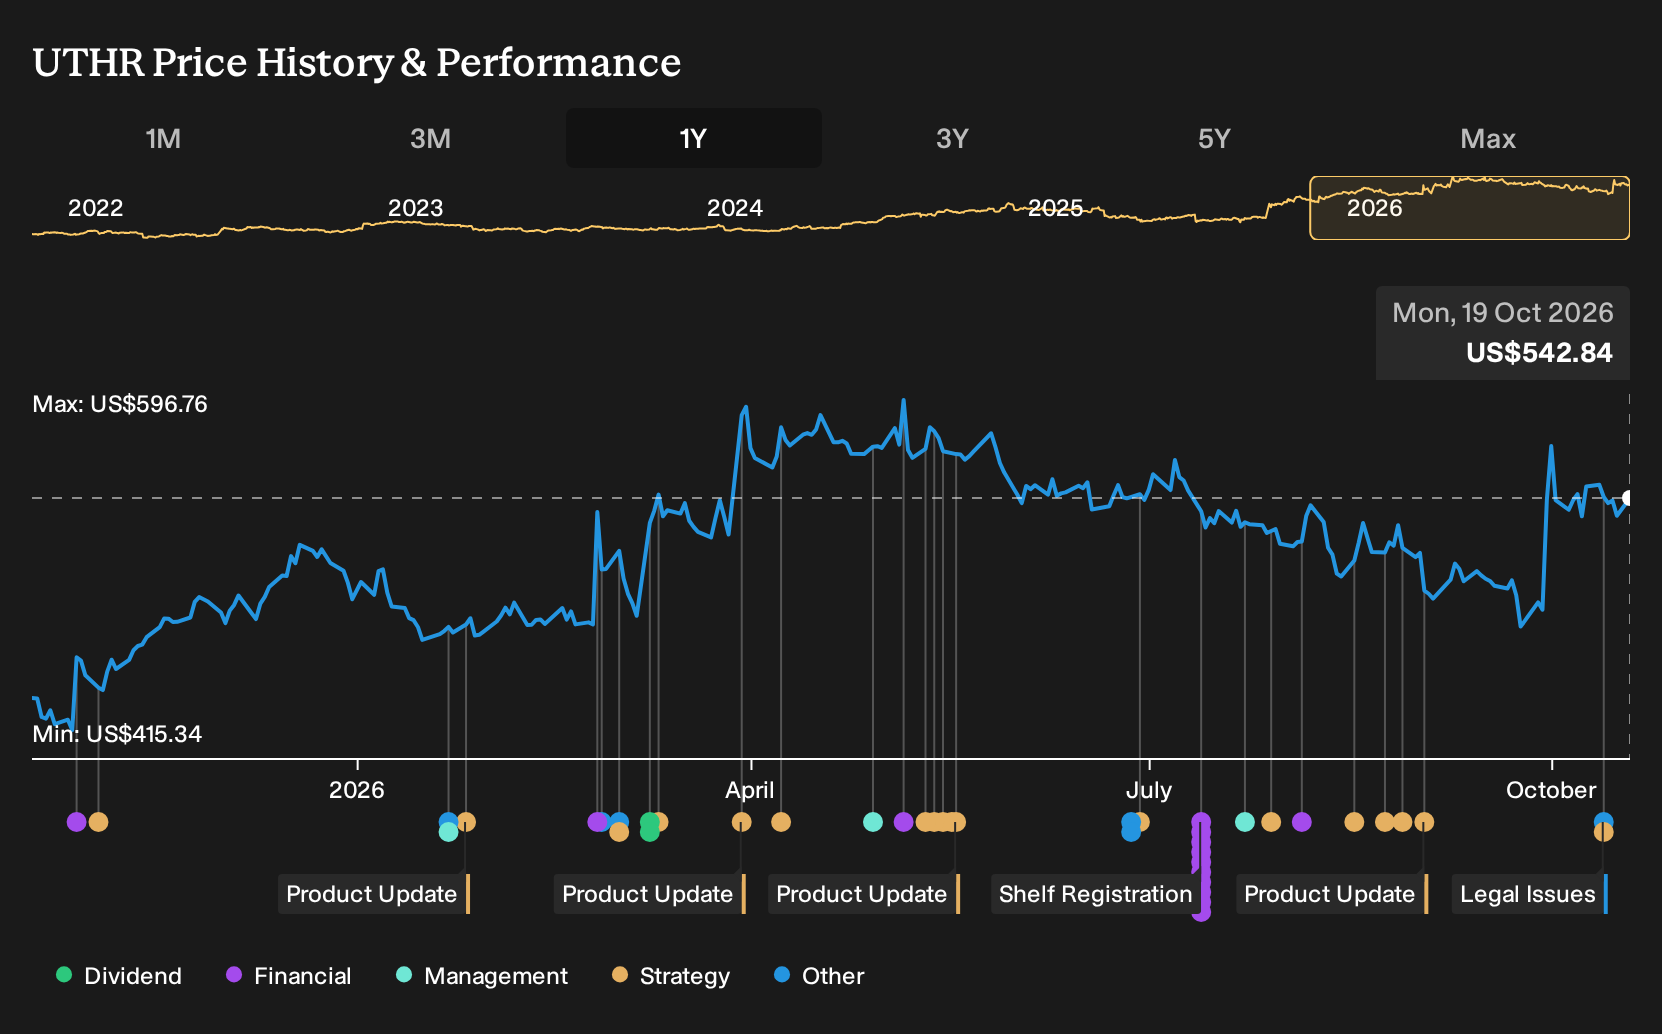
- United Therapeutics reported FDA clearance to begin the phase 2 SUMMIT trial of treprostinil SMI in PH-COPD and highlighted FDA review of ralinepag and nebulized treprostinil, underscoring active development across multiple pulmonary indications.
- The combination of a handheld soft mist treprostinil device, multiple dose strengths and long term extension data collection points to a push for more flexible, higher persistence treprostinil use in broader respiratory populations.
- The investment narrative around United Therapeutics’ push into larger pulmonary markets now aligns with concrete FDA progress on treprostinil SMI in PH-COPD.
United Therapeutics Investment Narrative Recap
To own United Therapeutics, you need to be comfortable with a story that leans heavily on expanding treprostinil and ralinepag into broader pulmonary fibrosis and COPD populations while defending the existing pulmonary arterial hypertension base. The SUMMIT phase 2 clearance fits that view but is early stage and does not change the near term dependence on Tyvaso, Remodulin and Orenitram.
In the short run, the key swing factor still looks like upcoming FDA decisions for nebulized Tyvaso in idiopathic pulmonary fibrosis and ralinepag in pulmonary arterial hypertension. The biggest risk remains that real world adoption across larger pulmonary populations, limited by dosing or tolerability, falls short of expectations.
The FDA clearance for the SUMMIT trial of treprostinil SMI in PH COPD is the announcement that aligns most directly with the current pulmonary pipeline narrative. A handheld, soft mist inhaler with multiple dose strengths aims at more tailored treprostinil use, and the 16 week blinded design plus open label extension focuses squarely on safety, tolerability and persistence.
For investors watching catalysts, SUMMIT progression now sits alongside the accepted FDA reviews for ralinepag and nebulized treprostinil. Together, these programs concentrate execution risk in clinical outcomes, regulatory decisions and physician uptake across several respiratory indications, while also providing multiple potential opportunities if any single study or indication underperforms expectations.
United Therapeutics' analyst narrative points to forecast revenue of US$4.4b and earnings of US$1.8b by 2029. This assumes revenue growth of 11.9% per year and an earnings increase of about US$500m from current earnings of US$1.3b.
Uncover how United Therapeutics' fair value indicates a 20% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate interpretation of United Therapeutics focuses less on pulmonary fibrosis launches and more on organ platforms and digital lung tools as the key swing factor. The most optimistic analysts were already modeling revenue of about US$5.1b and earnings around US$2.4b by 2029. That is a much more upbeat story. These views were set before this SUMMIT trial clearance, so use today’s news as a prompt to compare several scenarios and determine which version of the future you find more convincing.
Explore 3 other United Therapeutics fair value estimates, including one that suggests potential upside of as much as 273% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your United Therapeutics research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for United Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Therapeutics?
Once you have a view on United Therapeutics, it can help to compare that thesis with opportunities across other sectors and balance sheet profiles using the Simply Wall St Screener.
- If you prioritize resilience and lower volatility, start with a 32 resilient stocks with low risk scores that may better match a more conservative approach.
- For investors focused on balance sheet strength and solid fundamentals, scan a list of solid balance sheet and fundamentals (25 results) that can support long term business durability.
- Those hunting for underappreciated opportunities can review a 20 high quality undiscovered gems that are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com