
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Earnings Upgrade Just Shift Roper Technologies (ROP) Investment Narrative?
- Roper Technologies was recently upgraded to a Zacks Rank #2 after analysts raised earnings expectations, reflecting optimism around its underlying business performance.
- The more constructive view rests on expected strength across Roper Technologies’ Application Software, Technology Enabled Products and Network Software segments, where analysts view these operations as important contributors to future earnings power.
- We will now assess how this brighter multi segment earnings outlook for Roper Technologies could influence the broader investment narrative.
Roper Technologies Investment Narrative Recap
To own Roper Technologies, you need to be comfortable with a broad portfolio of vertical software and technology enabled products where recurring income and cash generation matter more than headline growth. The recent earnings optimism speaks directly to that. It points to healthier demand in Application Software, Network Software and Technology Enabled Products, which supports the near term case that core franchises are holding up.
The key short term swing factor remains execution in those software platforms and the ability to keep organic activity solid while integrating acquisitions. The biggest risk is still that acquired assets or weaker pockets like government related software or freight exposed tools drag on group performance. The latest news does not eliminate those issues, but it tilts the near term balance a bit more positively.
The most relevant update is the expectation for quarterly earnings of US$5.79 per share, with analysts looking for a 12.7% year on year rise. That estimate has held steady over the past month, which suggests the new optimism is more about confidence around existing numbers than a reset higher. For a complex portfolio like Roper Technologies, that kind of consistency is useful.
That forecast leans heavily on Application Software, Technology Enabled Products and Network Software continuing to do the work. It aligns with the broader catalyst story that recurring software, AI enabled tools and data rich verticals are still pulling their weight. The risk side is that earnings forecasts more broadly point to declines over the next three years, so any miss against this near term EPS mark would quickly refocus attention on integration quality, acquisition pricing and exposure to softer end markets.
What The Long Range Roper Technologies Forecast Really Implies
Roper Technologies' narrative projects US$10.0b revenue and US$2.1b earnings by 2029. This assumes 6.5% yearly revenue growth and an earnings decline of US$0.4b from US$2.5b today.
Analysts are effectively sketching out a picture where top line expansion continues at a mid single digit clip while profitability steps down. The spread between 30.2% profit margins today and the 20.8% margin assumption in three years signals a view that mix, investment intensity or pricing power could compress earnings relative to sales. For you as an investor, the story is less about rapid expansion and more about what you are willing to pay for a business that might be bigger in revenue terms yet lighter in profit per dollar of sales.
On the earnings side, the gap matters. Forecasts point to US$2.1b of profit by 2029 compared with US$2.5b today, even as revenue is assumed to climb to US$10.0b. That combination means the market debate turns to whether Roper Technologies can use its software and data franchises to offset margin pressure through efficiency, product upgrades or portfolio reshaping. It also means any surprise, positive or negative, around profitability can have an outsized effect on how the stock trades relative to these consensus anchors.
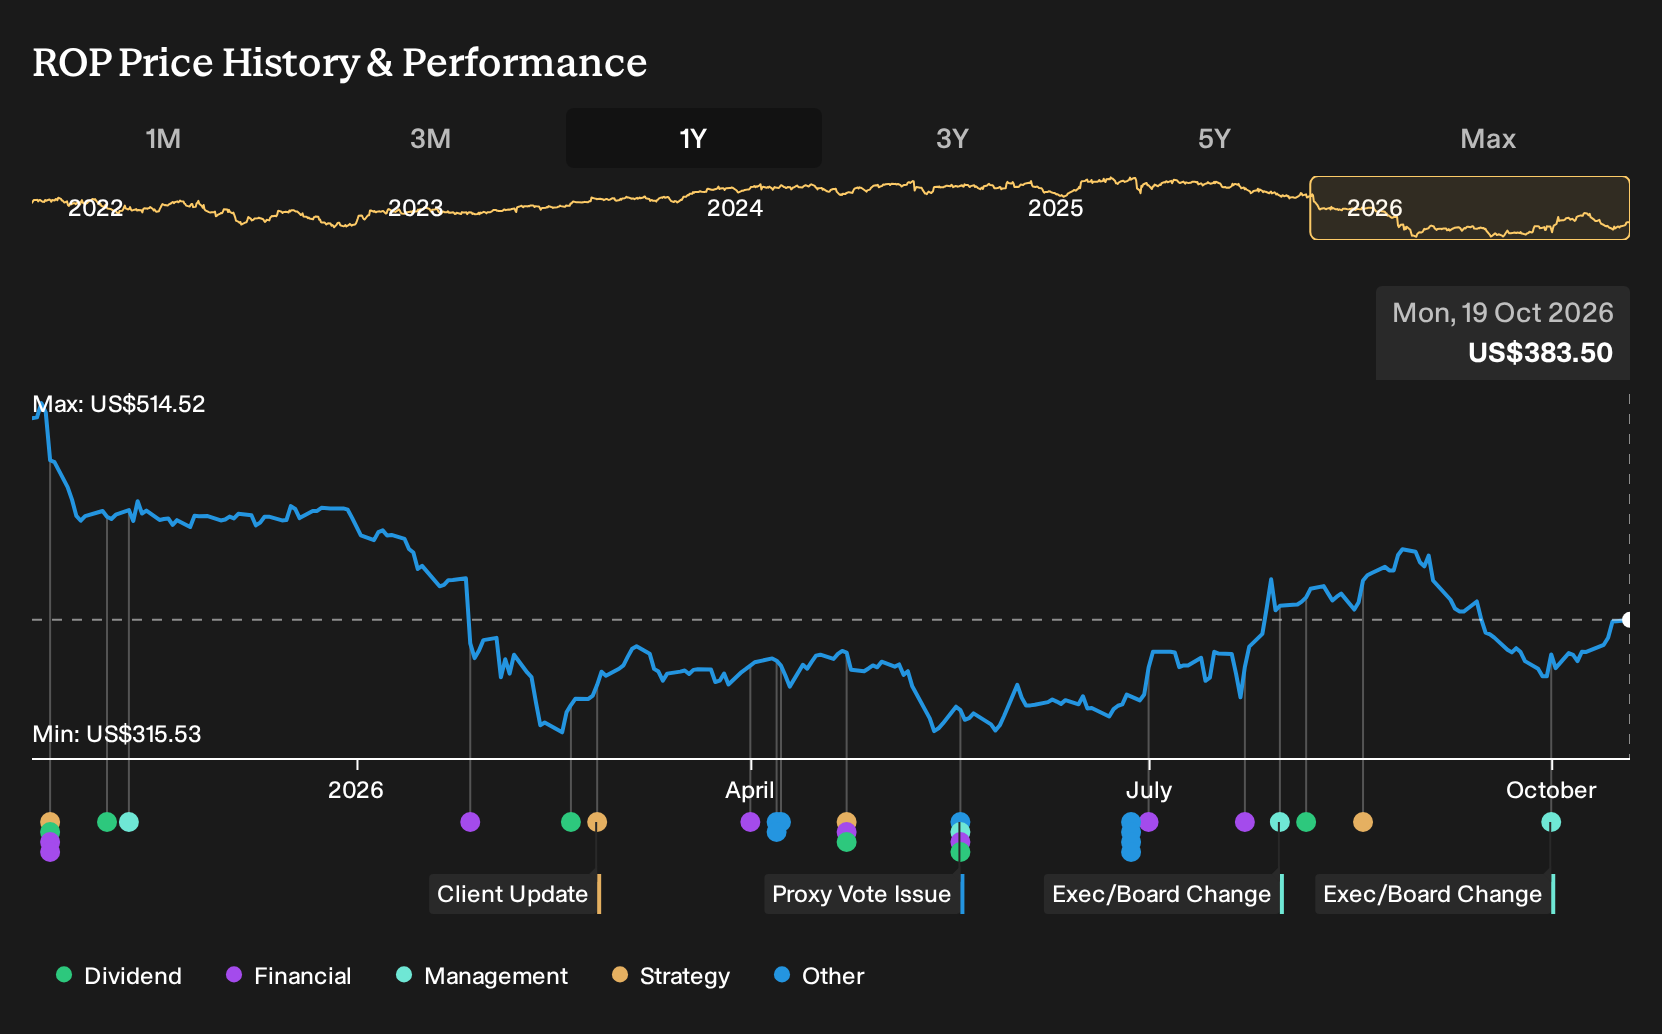
Uncover why Roper Technologies' fair value indicates a 16% potential upside to its current price, which could materialize sooner than many investors expect.
Exploring Other Perspectives
One alternate view around Roper Technologies focuses on slower AI adoption. The most pessimistic analysts were penciling in revenue of about US$9.8b and earnings near US$1.8b by 2029 before this upgrade, with margins compressing faster than consensus. That gap shows how sharply expectations can differ and why it helps to compare several narratives as fresh news lands.
Explore 2 other Roper Technologies fair value estimates, including one that suggests it could be worth just $439.43.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Roper Technologies research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Roper Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roper Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Roper Technologies?
If the Roper Technologies story has sharpened your view on quality and earnings power, it can help to line it up against other opportunities using the Simply Wall St Screener. You can filter for balance sheet strength, income focus or potential mispricing and build a shortlist that actually matches your risk tolerance and time horizon.
- If capital preservation and financial resilience sit high on your list, start with a list of solid balance sheet and fundamentals (25 results) that have the strength to handle tougher conditions.
- For readers hunting for mispriced opportunities with quality fundamentals, scan the 35 high quality undervalued stocks that fit your style before you commit fresh capital.
- If you care about income reliability as much as price appreciation, focus on a 8 dividend fortresses that aim to combine yield with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com