
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Pursuit Attractions and Hospitality Shares Buyback Means For Shareholders
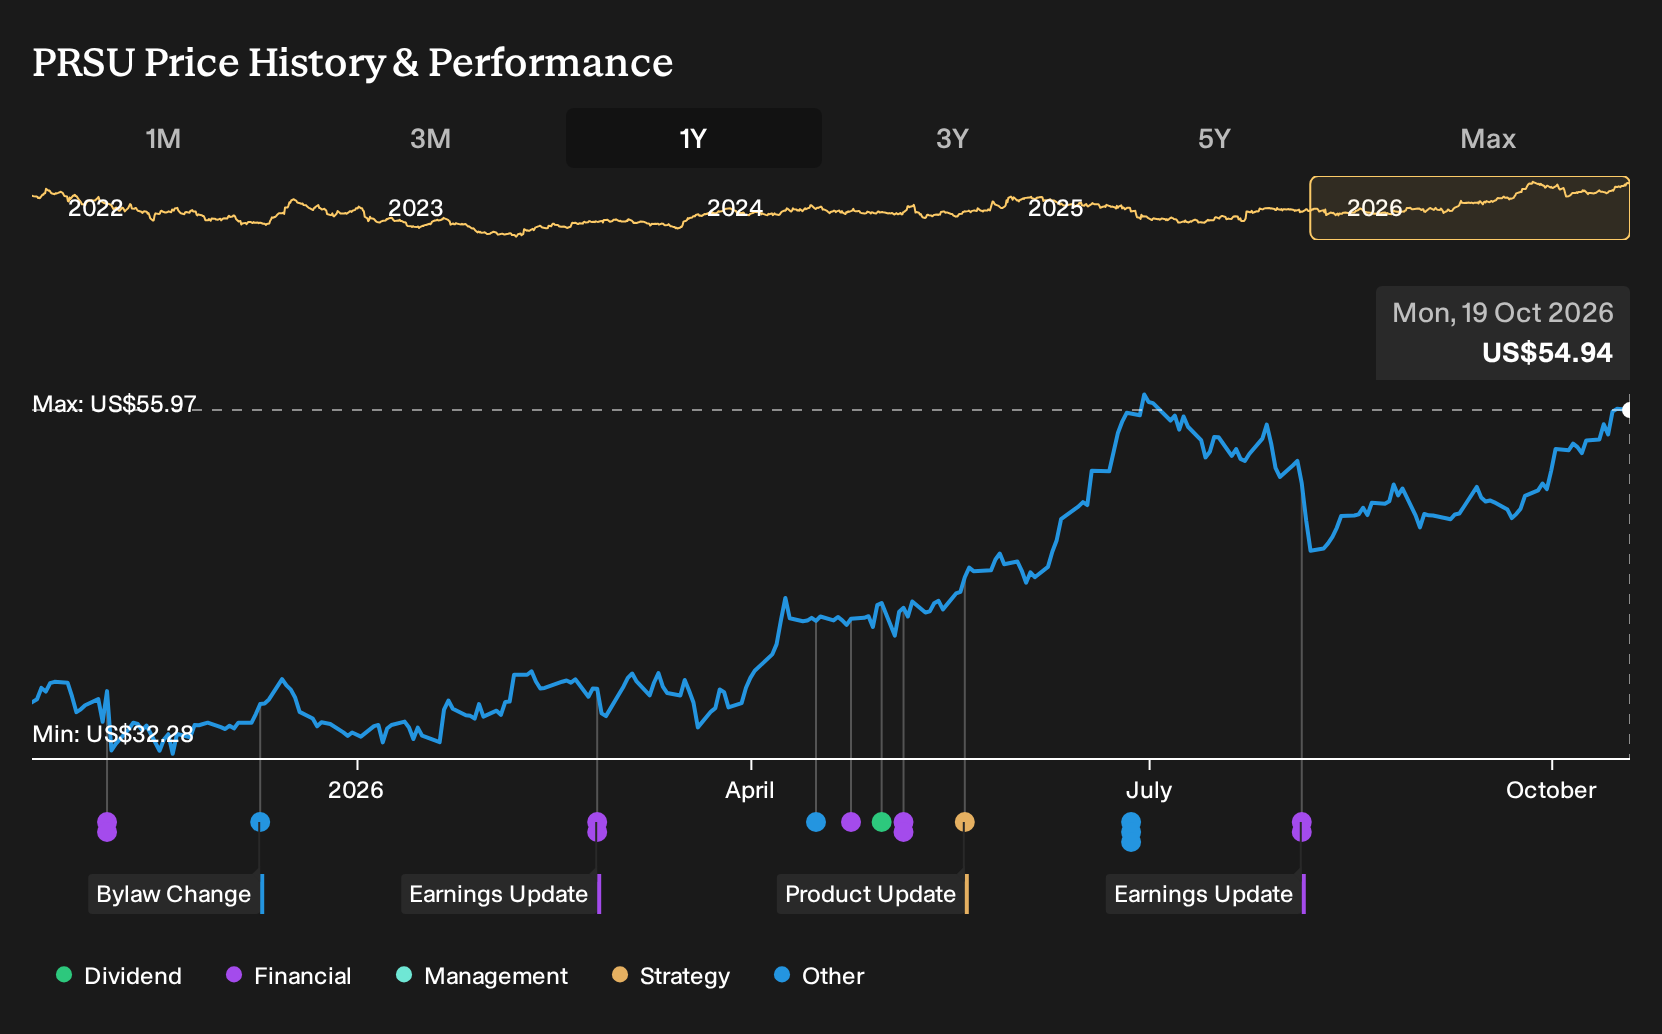
- Pursuit Attractions and Hospitality recently authorized a new US$50 million share repurchase program, which signals management’s willingness to allocate capital to buy back its own shares alongside an already elevated P/E relative to the wider hospitality group.
- The combination of a richer valuation multiple and fresh buyback capacity highlights how Pursuit Attractions and Hospitality is relying on balance sheet flexibility to support its long-term plan of high-end destinations, premium experiences, and yield-focused operations.
- This review will examine how Pursuit Attractions and Hospitality's investment narrative is shaped by management's new US$50 million share repurchase authorization.
Contrast Pursuit Attractions and Hospitality’s premium P/E and fresh US$50 million buyback firepower with other potential opportunities by scanning our hand picked 35 high quality undervalued stocks.
Pursuit Attractions and Hospitality Investment Narrative Recap
To own Pursuit Attractions and Hospitality, you need to believe its focus on premium, experience-led destinations can keep filling rooms and attractions even as travel tastes evolve. The key near term driver is still operational execution at its core sites in the US, Canada, Iceland, and Costa Rica, especially how effectively it manages pricing and guest spend per visit.
The biggest near term risk remains concentration in a handful of marquee locations that are exposed to weather, wildfires, and local regulation, alongside high capital needs for "Refresh, Build, Buy" projects. The new US$50 million buyback does not materially change those operational risks, but it may tighten liquidity if trading conditions weaken.
The fresh US$50 million share repurchase authorization is the announcement that matters most here. It sits alongside a P/E that already screens as expensive compared with both the US hospitality group and peers. For you as a shareholder, this ties the short term story more closely to earnings delivery and cash generation, because buybacks rely on both.
That repurchase capacity could support metrics like earnings per share if Pursuit Attractions and Hospitality keeps generating sufficient profit and cash from its attractions and eco-luxury resorts. It also raises the bar on execution of the investment pipeline above US$200 million. Any setback in visitation, pricing power, or cost control would not only pressure results but also limit how fully that authorization can realistically be used.
Pursuit Attractions and Hospitality Analyst Expectations In Context
Pursuit Attractions and Hospitality's repurchase plan now sits alongside a detailed analyst model that leans on modest top line expansion and firmer profitability rather than breakneck growth. Revenue is assumed to rise by 2.7% a year over the next three years while profit margins are expected to move from 8.7% today to 13.4% by 2029. That is a meaningful uplift in efficiency, and it is being projected at the same time analysts foresee ongoing capital commitments into new attractions and upgrades.
On the earnings line, the consensus view is that Pursuit Attractions and Hospitality could move from US$41.9 million in profit today to US$70.4 million by 2029. That is roughly a US$28.5 million step up in net income in exchange for a multiyear build out of the current project pipeline and continued emphasis on premium pricing and bundled experiences. For you as an investor, that gap between today's profit and the 2029 estimate is effectively the scoreboard analysts are using to judge whether management's investment and buyback decisions are paying off.
The share count assumption matters here as well. Analysts are baking in a 3.57% annual decline in shares outstanding over the next three years. That lines up directionally with the new US$50 million authorization and suggests the model expects buybacks to be a recurring use of cash rather than a one off headline. If the business cannot consistently generate enough free cash after "Refresh, Build, Buy" spending, either the repurchases or the project slate would eventually need to give.
Valuation expectations are tightly linked to those earnings forecasts. The consensus price target of US$62.0 is built on Pursuit Attractions and Hospitality reaching US$523.7 million in revenue and US$70.4 million in earnings by 2029 while trading on a P/E of 27.9x. That multiple is lower than the current 29.7x but higher than the broader US hospitality group at 23.2x, so the current thesis relies on the market continuing to treat Pursuit as a premium story even as its P/E drifts closer to sector levels.
The target range also shows there is nothing monolithic about analyst conviction. The most optimistic forecast points to US$70.0 per share while the most cautious sits at US$58.0, with the midpoint at US$62.0 representing around 26.3% upside from the recent US$45.67 share price. Rather than taking those figures at face value, it is worth asking whether the combination of 2.7% annual revenue growth, margin expansion to 13.4%, and consistent buybacks fits with your own view of how the attractions and eco-luxury resort model might play out through 2029.
Pursuit Attractions and Hospitality's narrative projects US$523.7 million in revenue and US$70.4 million in earnings by 2029. This assumes 2.7% yearly revenue growth and about US$28.5 million earnings increase from US$41.9 million today.
Uncover how Pursuit Attractions and Hospitality's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The most optimistic analysts focus on one big swing for Pursuit Attractions and Hospitality: the roughly US$300 million growth program through 2030. Before this new US$50 million buyback, that bullish camp was already banking on revenue reaching about US$523.9 million and earnings of US$65.4 million by 2029, which is far more upbeat than consensus. You can treat this fresh repurchase news as a prompt to compare that higher growth story with your own expectations and explore how those projections might shift from here.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A starting point for your Pursuit Attractions and Hospitality research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Pursuit Attractions and Hospitality. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easier to evaluate Pursuit Attractions and Hospitality's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pursuit Attractions and Hospitality?
If the Pursuit Attractions and Hospitality story has sharpened your view on quality, price, and risk, it can be useful to line that up against a wider set of companies using the Simply Wall St Screener.
- For investors who want mispriced quality, scan a curated group of businesses that combine strong fundamentals with room for a better entry point through our 35 high quality undervalued stocks.
- If resilience matters most to you, filter for companies that pair robust balance sheets with solid financial profiles by reviewing the list of solid balance sheet and fundamentals (25 results).
- For those who care about smoother ride potential, focus on businesses with lower overall risk profiles by checking the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com