
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Regency Centers (REG) Pulls Back, Is The Valuation Discount Still Enough?
Regency Centers (REG) has drawn fresh attention after recent trading left the stock modestly down over the past 3 months, even as its year to date return remains in positive territory. Investors are reassessing what that mixed pattern implies.
Recent trading suggests that momentum in Regency Centers is fading in the short term, with the share price down about 12% over three months, even though the year-to-date share price return of 6.6% sits alongside a three-year total shareholder return of 38%.
Scan a curated short list of real estate investment trusts that have resilient return profiles similar to Regency Centers through the 32 resilient stocks with low risk scores.
That combination of a recent pullback and still positive longer term returns leaves Regency Centers in an awkward middle ground. Has most of the easier potential upside already played out, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 15% Undervalued
At a last close of $72.41 versus a narrative fair value of $84.83, Regency Centers screens as modestly discounted, which puts more weight on how its longer term projects and funding capacity play out from here.
Regency Centers' in-process development and redevelopment pipeline of about US$680 to US$700 million at blended returns of roughly 9%, along with an expected US$400 million of new starts in 2026, gives the company a visible source of incremental rent and fee income that can add to revenue and earnings beyond what existing centers already produce.
See why 7 investors see Regency Centers as 15% undervalued.
Result: Fair Value of $84.83 (UNDERVALUED)
Still, Regency Centers’ story can fray if higher interest costs reduce funding flexibility or if key grocery and specialty tenants start closing stores faster than expected.
Find out about the key risks to this Regency Centers narrative.
Another View On Regency Centers Valuation
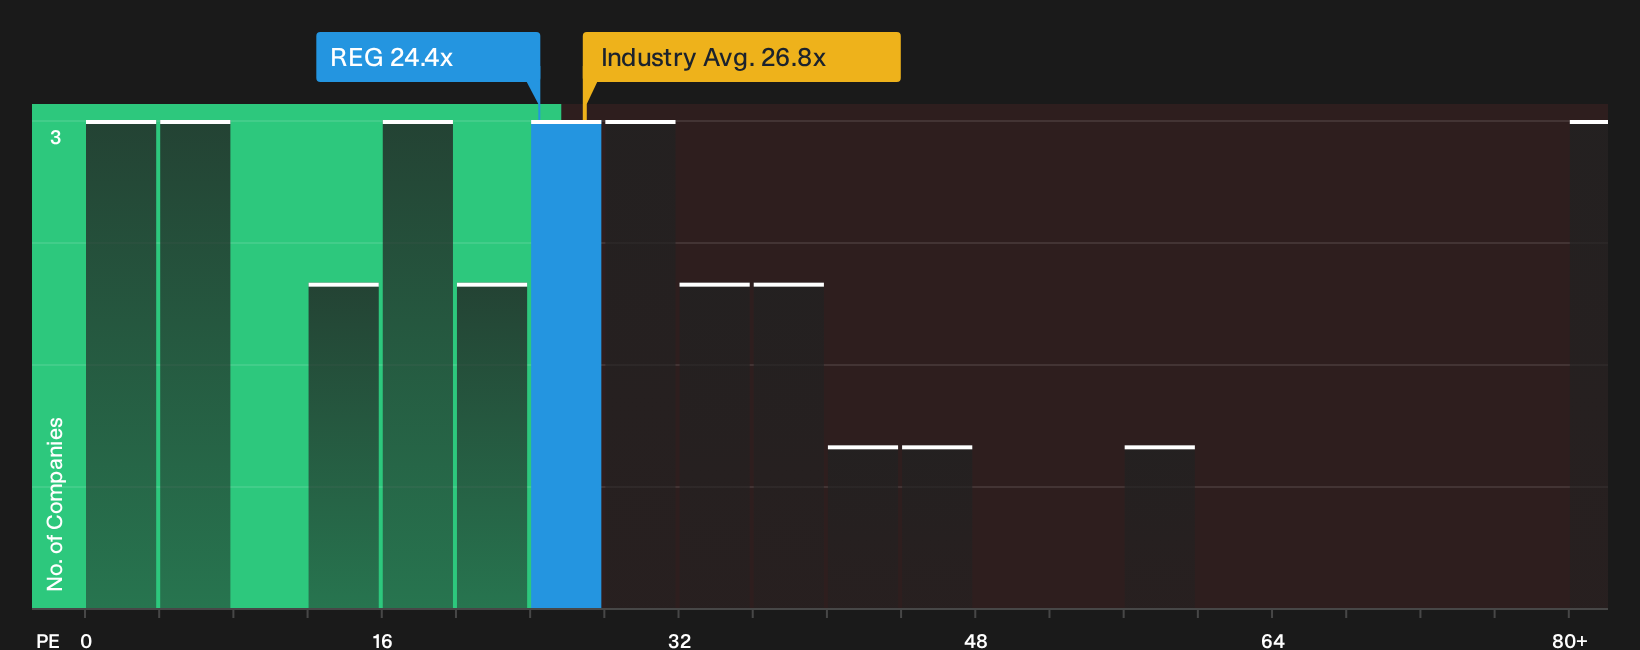
While the earlier narrative leans on analyst targets and earnings assumptions, the market multiple tells a different story. Regency Centers trades on a P/E of 24.4x, richer than the peer average of 21.9x, yet below a fair ratio of 30.3x that the data suggests the market could move toward. That mix of slight premium to peers but discount to the fair ratio raises a practical question for you: is this a cushion against disappointment or a smaller margin of safety if the story softens?
See what the numbers say about this price in our valuation breakdown through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Regency Centers can either feel like noise or a genuine fork in the road. Consider taking action while sentiment is split and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Regency Centers?
If Regency Centers has you thinking about portfolio upgrades, do not stop here. Fresh ideas now can matter more than small timing differences later.
- Chase potential mispricing by scanning a tight shortlist of quality opportunities through the 35 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on companies with durable finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-the-radar opportunities with strong fundamentals by reviewing the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com