
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shanghai Conant Optical (SEHK:2276) Could Be 21% Undervalued On DCF Commentary
Fresh interest in Shanghai Conant Optical (SEHK:2276) has been stirred by commentary suggesting the share price may not yet fully reflect anticipated future cash flow growth. This has put its DCF valuation assumptions under the spotlight for investors.
Recent trading in Shanghai Conant Optical has been choppy, with the share price gaining 3.17% over the last day but down 13.36% over 30 days and 35.01% year to date. The 3-year total shareholder return of more than 5x suggests longer term momentum that contrasts with the softer short term share price performance investors are reacting to now.
Compare Shanghai Conant Optical's cash flow driven story with a curated group of companies that also screen as potential mispriced opportunities in our 197 high quality undervalued stocks.
Shanghai Conant Optical now trades well below both its recent peak and published fair value estimates. How wide is the gap between the current HK$35.16 price and a reasonable valuation range?
Price-to-Earnings of 24.7x: Is it justified?
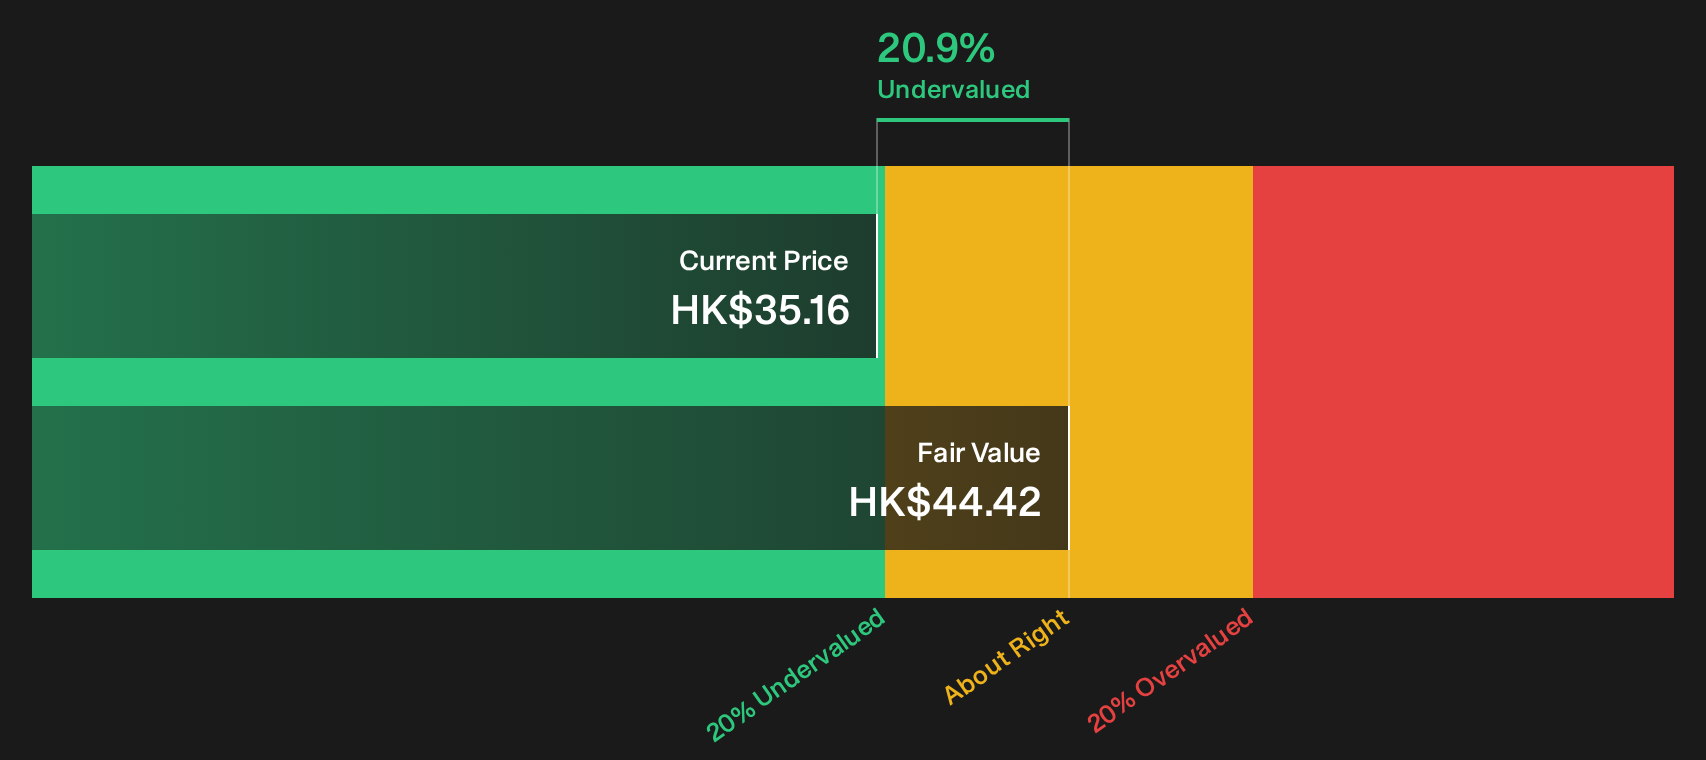
On simple valuation math, Shanghai Conant Optical screens as undervalued on a DCF basis, with an estimated future cash flow value of HK$44.42 against the HK$35.16 share price. However, its P/E ratio of 24.7x tells a different story when compared with peers and a fair-value multiple.
The P/E ratio compares what you pay today for each unit of earnings that Shanghai Conant Optical generates. For a medical equipment manufacturer with positive earnings and growth forecasts, P/E often acts as a quick check on how much optimism is already in the price.
At 24.7x earnings, the stock trades at a clear premium to the Hong Kong Medical Equipment industry average of 18.4x and the estimated fair P/E ratio of 19.4x. The market is effectively assigning a richer tag than both peers and the level the fair ratio analysis suggests it could move towards.
Explore the SWS fair ratio for Shanghai Conant Optical.
Result: Price-to-Earnings of 24.7x (OVERVALUED)
Still, Shanghai Conant Optical faces clear risks if earnings stumble or sector sentiment cools, since a 24.7x P/E could quickly appear stretched.
Find out about the key risks to this Shanghai Conant Optical narrative.
Another View on Shanghai Conant Optical’s Value
The SWS DCF model points a different way for Shanghai Conant Optical. On that cash flow based lens, the HK$35.16 share price sits about 20.9% below an estimated value of HK$44.42. One method flags overvaluation; the other signals a discount. Which signal do you trust more right now?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Conant Optical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Shanghai Conant Optical is clearly mixed, with both caution and optimism in play. Consider reviewing the key data for yourself and weighing up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Shanghai Conant Optical?
If Shanghai Conant Optical has your attention, do not stop there. Broaden your watchlist now so you are not late to the next opportunity.
- Hunt for potentially mispriced quality by scanning our carefully filtered list of 197 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- Reinforce your portfolio’s staying power by checking companies with robust finances through the list of solid balance sheet and fundamentals (202 results).
- Get ahead of the crowd by tracking underfollowed businesses surfaced in the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com