
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Energy Stocks With Cash Returns Back In Focus
Inflation in Canada just pushed back above 3%, and energy is doing a lot of the heavy lifting. That mix of pricier fuel, rate hike risk and geopolitical shocks is quietly reshuffling where risk and reward sit in the market. Investors who ignore it may miss chances or hold the wrong exposure. This article breaks down how that backdrop hits Canadian producers and reveals 3 stocks directly exposed to the story.
The three Canadian energy producers covered below are just a starter pack, and the full screen surfaced 14 more listed businesses with equally compelling stories that are not included here. To go deeper, head straight into the Canadian Energy Producers screener to identify, analyze, and focus on the ideas that best fit your energy thesis.
InPlay Oil (TSX:IPO)
Overview: InPlay Oil is a Calgary based producer that acquires, drills and develops light oil and gas assets in West Central Alberta.
Operations: InPlay Oil generates all of its CA$317.9 million revenue from Canadian oil and gas exploration and production activities.
Market Cap: CA$548.1 million
InPlay Oil provides pure Canadian upstream exposure, with every dollar of revenue tied to domestic oil and gas prices and producer margins. The stock combines that direct pricing link with a meaningful dividend and ongoing buybacks. As a result, the overall focus is on cash returns that depend heavily on how one unseen pressure on those margins is resolved.
Those cash returns hinge on that pressure, so check the 4 key rewards and 3 important warning signs (2 are major!) to see how InPlay Oil’s payout story compares with its risk profile.

Pine Cliff Energy (TSX:PNE)
Overview: Pine Cliff Energy is a Calgary based producer of natural gas and crude oil across the Western Canadian Sedimentary Basin, giving investors focused Canadian upstream exposure.
Operations: Pine Cliff Energy generates its CA$161.3 million revenue entirely in Canada, tightly linking its cash flows to domestic commodity pricing.
Market Cap: CA$190.2 million
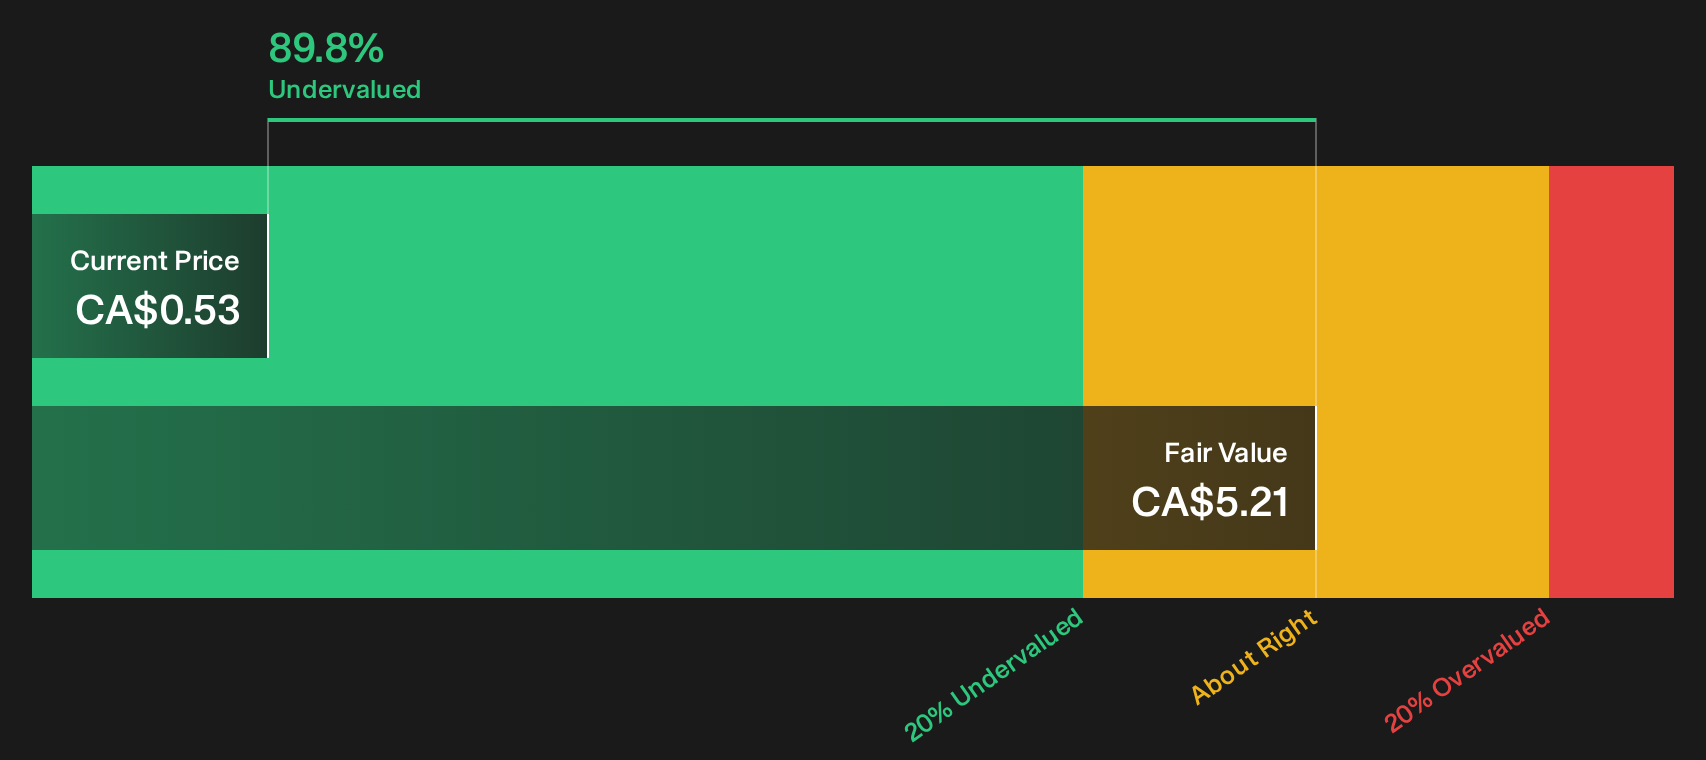
For investors zeroing in on Canadian Energy Producers, Pine Cliff Energy offers pure-play exposure to domestic gas and oil pricing, a visible monthly dividend and a stock trading well below estimated fair value. However, it remains loss making, so the payoff from this inflation driven energy backdrop depends heavily on how one key earnings swing factor ultimately changes.
That swing factor is exactly what the 3 key rewards and 1 important major warning sign unpacks, so you can see where Pine Cliff Energy’s income story could accelerate or stall next.
CES Energy Solutions (TSX:CEU)
Overview: CES Energy Solutions supplies drilling fluids, production chemicals and related services that support oil and gas producers across Canada and the United States.
Operations: CES Energy Solutions generates CA$2.68b from oil and gas contract drilling related products and services, with CA$904 million in Canada and CA$1.78b in the United States.
Market Cap: CA$4.24b
CES Energy Solutions plugs into the Canadian Energy Producers theme as a picks and shovels business, because its chemicals and fluids move largely in step with drilling budgets rather than consumer demand or interest rates.
"The company's ongoing bids for large production chemical contracts, primarily representing new customers, could significantly expand market share and provide higher-margin, recurring revenues. This would enhance both top-line growth and EBITDA margins if awarded."
What ultimately happens to those margins and cash returns hinges on how one unresolved cost and pricing pressure plays out.
If that pressure does start to ease, the full narrative for CES Energy Solutions walks you through how CES Energy Solutions’ contract wins, pricing power and risks could be getting misread.

Seeking Fresh Alternatives Before They Fly?
Fresh opportunities do not sit still. While money chases headlines, quieter ideas can build momentum under the radar for now. Before the best entry points get caught, act now.
- Spot potential turnaround stories early and scan the 10 high quality undiscovered gems before others start talking about them and valuations move away from you.
- Target resilient payers while yields still look appealing by working through the 3 dividend fortresses before prices move and the income math weakens.
- Ride structural demand shifts by reviewing the 42 power grid technology and infrastructure stocks while grid and electrification themes are still dropping fresh opportunities into small and mid caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com