
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Austevoll Seafood (OB:AUSS) Could Be 22% Undervalued On Supply Tightness
Recent commentary around Austevoll Seafood (OB:AUSS) has focused on two key points: a valuation that appears below some industry peers on earnings, and tight global supply for fishmeal and fish oil that supports its competitive position.
At a latest share price of NOK82.6, Austevoll Seafood has seen short term share price returns that are broadly flat, while the year to date share price has fallen 16.4%. The three year total shareholder return of 40.6% shows a much stronger longer run outcome.
Scan beyond Austevoll Seafood and compare it with a curated 197 high quality undervalued stocks list that appears priced for a potential rerating based on earnings strength and balance sheet quality.
Austevoll Seafood now pairs a softer year to date share price with earnings and asset metrics that some investors view as supportive. Does that mix still tilt the risk reward in favour of new buyers at this valuation?
Most Popular Narrative: 22% Undervalued
Austevoll Seafood's most followed valuation storyline pins fair value at NOK106 per share, compared with the latest NOK82.6 price in the market. That gap frames a thesis built around steady demand for seafood, disciplined capital allocation, and an earnings profile that some investors view as improving from a low margin base.
Some investors point to global consumption trends shifting toward higher-protein, health-oriented diets. Austevoll is already the largest whitefish producer in Norway and is expanding higher-value product volumes (such as ready-to-eat and specialty seafood), which they view as positioning the company to participate in long-term demand growth and potentially support both revenue and margin improvement if selling prices rise.
See why 35 investors see Austevoll Seafood as 22% undervalued.
Result: Fair Value of NOK106 (UNDERVALUED)
Still, the Austevoll Seafood story can unravel quickly if prolonged price pressure in salmon, fishmeal or fish oil persists, or if new Chilean quota rules bite harder than expected.
Find out about the key risks to this Austevoll Seafood narrative.
Another View: Austevoll Seafood On Earnings Multiples
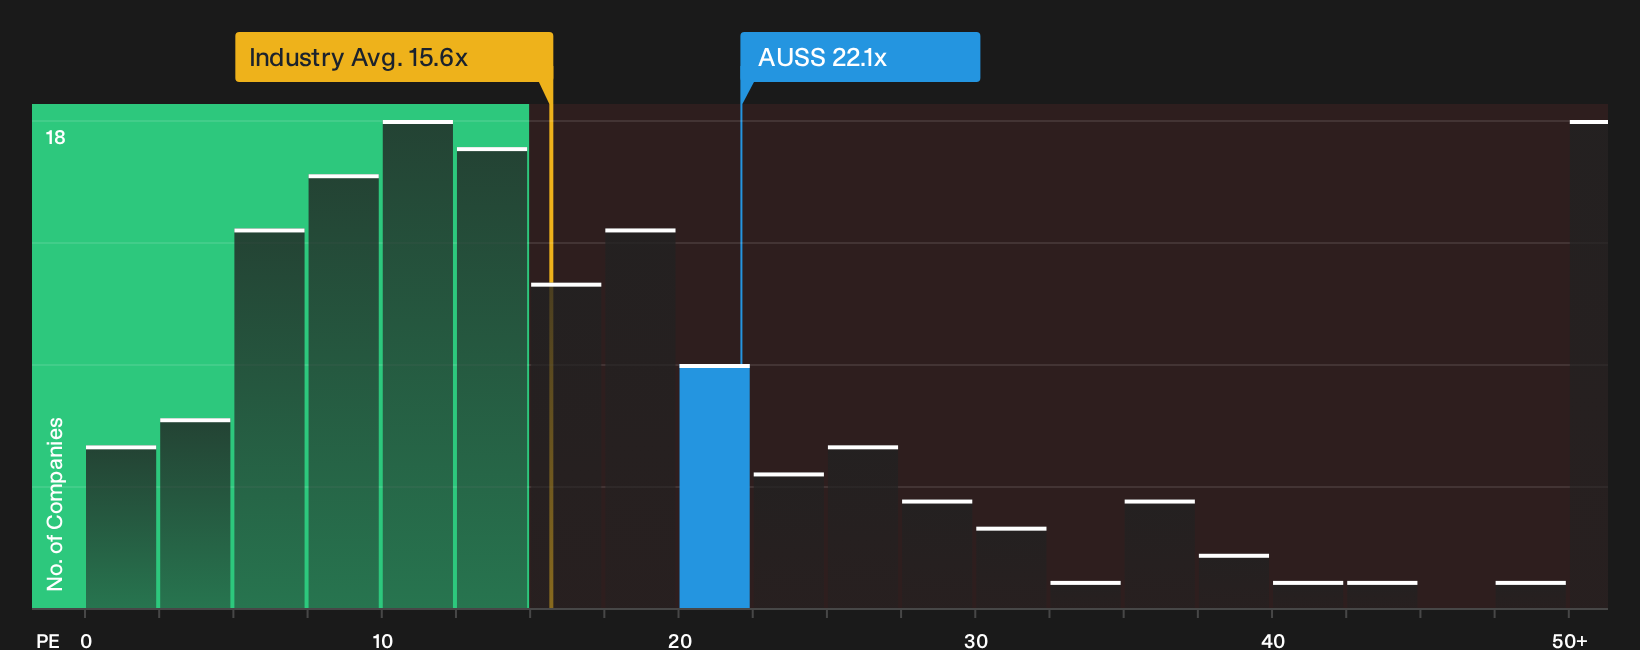
On a pure earnings lens, Austevoll Seafood looks less clear cut. The shares trade on a P/E of 22.1x, which is higher than the European Food sector at 15.6x, yet below both its peer average of 26.9x and a fair ratio of 27.5x that the market could move toward.
That mix of premium versus the wider industry, but discount versus peers and the fair ratio, points to a trade off between valuation risk and upside potential that each investor needs to weigh carefully.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on Austevoll Seafood leave you on the fence, move quickly to review the full picture of risks and rewards. Start by weighing the 3 key rewards and 2 important warning signs.
Looking for more Austevoll Seafood sized ideas?
If Austevoll Seafood has sharpened your focus on valuation and quality, do not stop here. Use the screener to surface fresh opportunities tailored to your approach.
- Target potential mispricing by scanning a 197 high quality undervalued stocks that filters for solid fundamentals alongside attractive P/E and balance sheet profiles.
- Build a steadier income foundation by reviewing a 217 dividend fortresses that zeroes in on higher yield payouts backed by stronger financials.
- Limit downside shocks by hunting through a 231 resilient stocks with low risk scores that highlights businesses scoring well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com