
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is MedinCell (ENXTPA:MEDCL) A Bargain On Its €41.8 Million Non Dilutive Funding?
MedinCell (ENXTPA:MEDCL) is back in focus after securing €41.8 million in non dilutive financing since July 2026, while reshaping its debt profile and reinforcing cash resources without issuing new shares.
MedinCell’s latest non dilutive funding and debt reshaping come after a mixed run in the market, with a 30 day share price return of 20.86% and a 1 year total shareholder return that declined 25.16%. However, the 3 year total shareholder return is very large at about 4.3x, and the 5 year total shareholder return is also strong.
Scan MedinCell’s financing story against peers by weighing it up alongside 231 resilient stocks with low risk scores, which also prioritize balance sheet strength and non dilutive funding.
So is MedinCell’s sharp recent rebound a simple mood swing after a tough year for shareholders, or is it a case of a cleaner balance sheet finally forcing the valuation to catch up with the business?
Most Popular Narrative: 25% Undervalued
MedinCell’s most followed valuation story places fair value at about €35.07, which sits meaningfully above the latest close at €26.30 and frames the recent rally as only a partial catch up.
U.S. patent extensions for UZEDY (to 2042) and Olanzapine LAI (to 2044) significantly prolong periods of exclusivity, protecting pricing power and supporting higher net margins and long-term earnings visibility than may be reflected in the current stock price. MedinCell's ability to secure large-scale partnerships (recent AbbVie deal, high ongoing partner interest) and expansion into emerging global markets for long-acting injectable therapies position it to capture rising demand fueled by broader healthcare access and aging populations, directly supporting future revenue expansion potential.
See why 6 investors see MedinCell as 25% undervalued.
Result: Fair Value of €35.07 (UNDERVALUED)
Still, MedinCell’s reliance on just UZEDY and Olanzapine LAI, along with the need for smooth regulatory approvals, could quickly weaken that undervaluation argument.
Find out about the key risks to this MedinCell narrative.
Another View: Multiples Paint a Tougher Picture for MedinCell
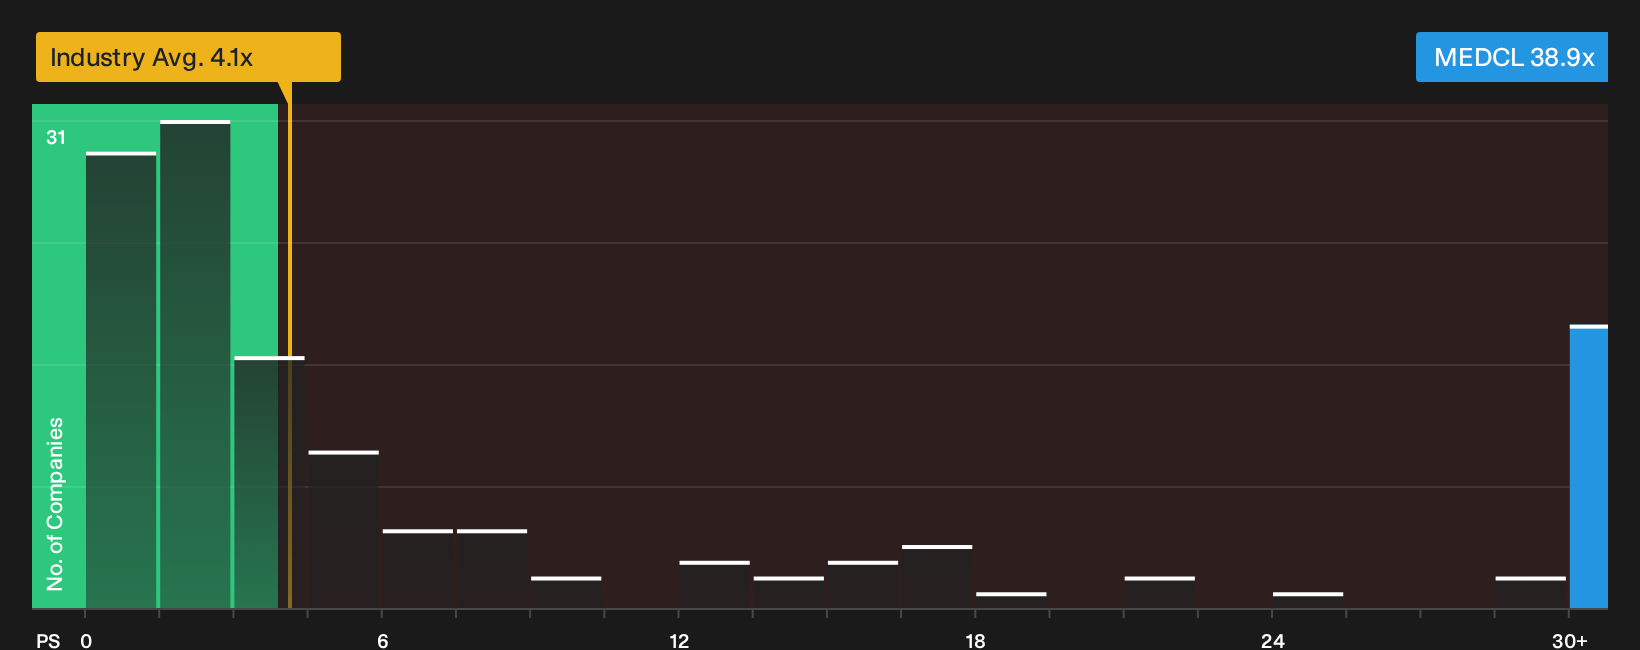
The 25% undervalued story for MedinCell runs into a very different message when you look at simple sales multiples. The shares trade on a P/S of 38.9x, while the European pharmaceuticals group sits around 4.1x and direct peers average 4.6x.
The fair ratio is 8.6x, which is far closer to the peer pack than to the current valuation. For you as an investor, that gap means the market already bakes in a lot of future success, so the key consideration is whether you are comfortable paying so much upfront for that narrative to play out.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on MedinCell so far. Now is the moment to pull up the full data, test the bullish and bearish angles, and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond MedinCell?
Do not stop with a single stock. Give yourself options by lining up a few clear, data backed themes that match the way you prefer to invest.
- Target potential value opportunities by scanning companies that combine quality fundamentals with attractive pricing through the 197 high quality undervalued stocks.
- Strengthen your income game by reviewing companies with heavier yield profiles using the 217 dividend fortresses.
- Sharpen your quality filter by focusing on balance sheets and fundamentals through the list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com