
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Server Orders Could Be A Big Test For Dell (DELL)
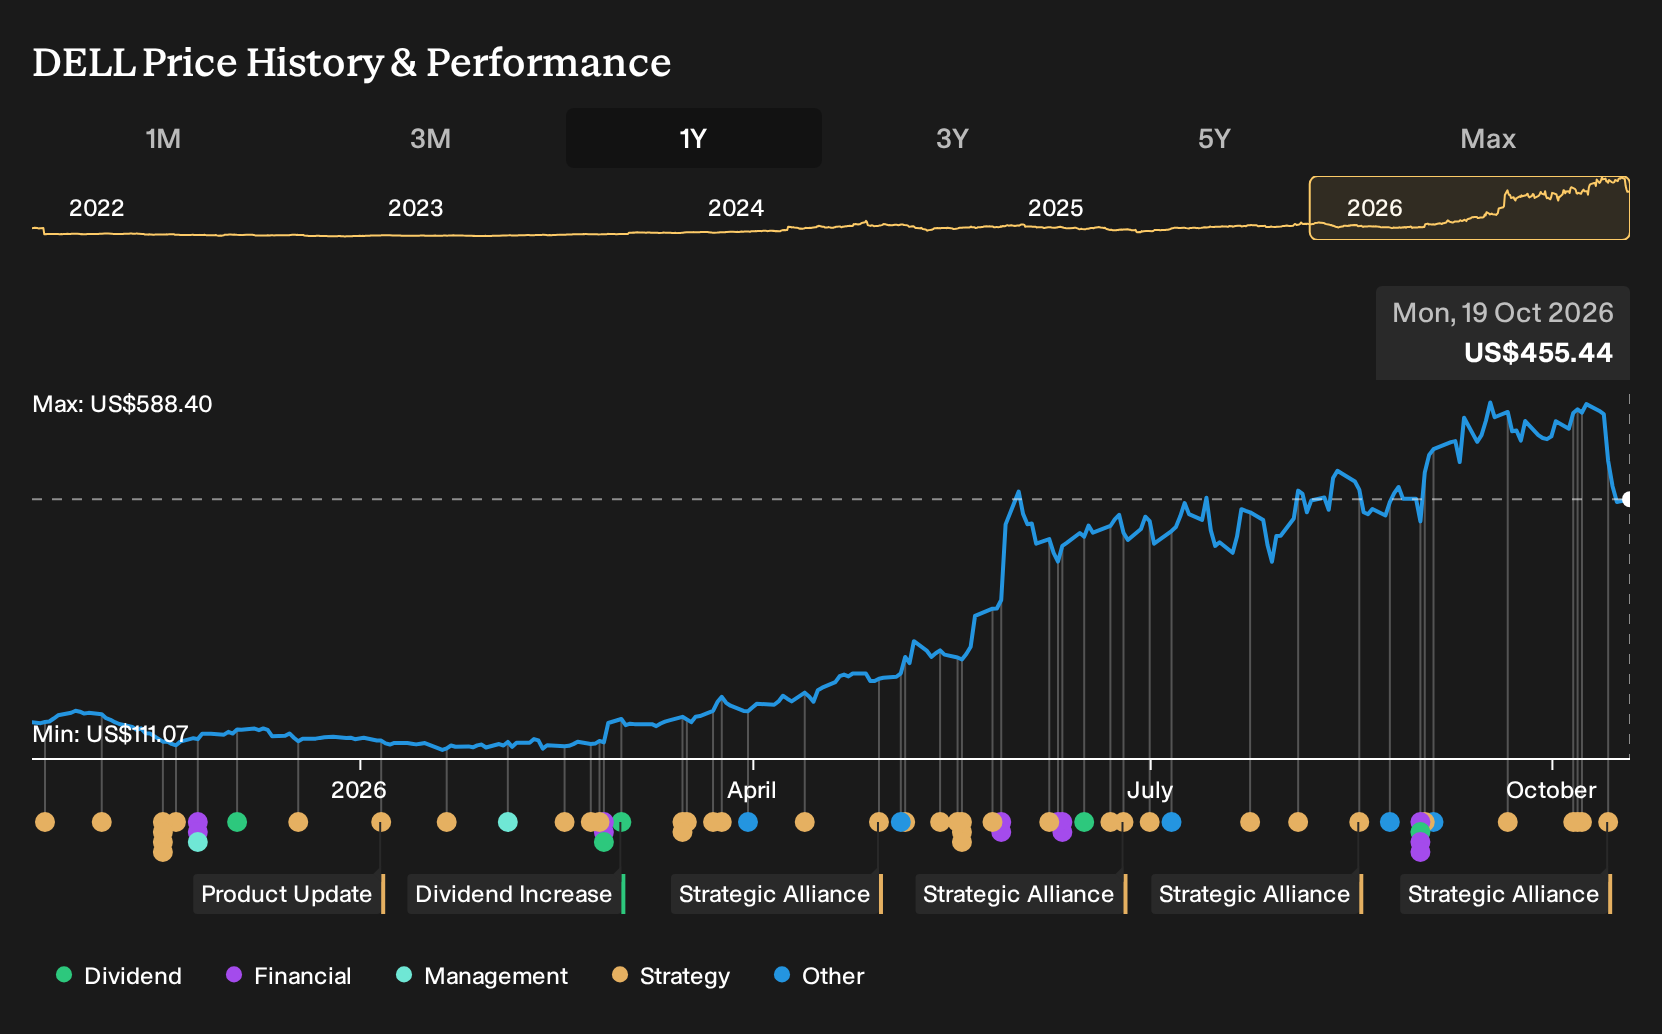
- Dell Technologies has been central to a series of AI focused announcements in October 2026, including Honeywell’s Forge Cognition rollout, new Windows agentic AI PCs and workstations with NVIDIA and Microsoft, and extensions to the Dell AI Data Platform built to support AI agents from data center to edge.
- Across these updates, Dell Technologies is positioning its infrastructure, PCs and services as the practical plumbing for enterprise AI factories, backed by more than US$130b of AI server orders and a sizeable backlog that ties directly to future deployment work.
- We will look at how Dell Technologies’ investment narrative is affected by this surge in AI infrastructure demand anchored by US$130b server orders.
Scan how Dell Technologies fits into the broader AI build out, then size up hand picked peers using our screener of 55 AI infrastructure stocks as the next place to focus your research.
Dell Technologies Investment Narrative Recap
To own Dell Technologies, you need to believe the AI build out can offset pressure in more traditional servers, storage and PCs, while tight execution keeps that US$130b AI server order book converting into revenue. The key near term catalyst is how quickly Dell can turn its US$95b backlog and related pipeline into shipped systems without sacrificing pricing.
The biggest operational risk sits in component supply and mix. Hardware constraints in GPUs, memory and optics, as well as the lower margin profile of AI servers, could cap earnings quality if storage and services do not keep pace. Recent announcements reinforce demand signals but do not eliminate these margin and supply bottleneck concerns.
Among the recent moves, the expanded Accenture Dell Business Group is particularly relevant for the AI backlog story. It is aimed at helping enterprises deploy private AI factories on Dell infrastructure, which speaks directly to converting that large order book into broader, multi year projects rather than one off hardware deals.
If execution inside this joint group is strong, it can support higher value storage, data platform and services pull through on top of AI servers, which matters for profitability. It also gives Dell another route into highly regulated sectors that require on premises AI, adding practical support to the thesis that AI demand can endure short term hardware cycle swings.
Dell Technologies' analyst narrative points to forecast revenues of US$266.7b and earnings of US$20.8b by 2029, built on an assumed 20.8% yearly revenue growth rate and an increase in earnings of about US$9.4b from US$11.4b today.
Uncover why Dell Technologies' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on the risk that Dell Technologies stays stuck selling mostly mid single digit margin AI servers, while partners like Honeywell’s Forge Cognition keep more of the software and services upside. The most cautious analysts were only penciling in about US$215.6b of revenue and US$16.4b of earnings for 2029, which is far below the consensus path. That gap shows how widely opinions can differ. Use it as a prompt to explore several narratives before deciding how this latest AI alliance might reshape your own expectations.
Explore 4 other Dell Technologies fair value estimates, including one that suggests it could be worth just $480.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Dell Technologies research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dell Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dell Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dell Technologies?
Once you have a view on Dell Technologies, it can help to compare that thesis with other opportunities filtered by balance sheet strength, income potential and mispricing. The Simply Wall St Screener is built for exactly that kind of targeted search.
- For investors who want staying power over spectacle, start with a list of solid balance sheet and fundamentals (25 results) that can better support long projects and capital returns through different business cycles.
- If your focus is on finding potential mispricings, use the 35 high quality undervalued stocks that pair robust fundamentals with prices that screen below their underlying metrics.
- Income focused readers can zero in on a 8 dividend fortresses that match a 5%+ yield with balance sheets built to support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com