
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Prediction: Here's What a $5,000 Investment in Joby Aviation Will Be Worth in 10 Years
Key Points
Joby Aviation is aiming to produce 500 eVTOLs per year.
With a fleet of 2,500 eVTOLs by 2036, Joby could generate $1 billion or more in passenger service revenue.
Imagine it's 2036. You're standing on a rooftop in the heart of New York City, waiting for a ride to the airport. Suddenly, there's a sound like a giant electric fan overhead, and a small helicopter-like aircraft descends. A few seconds later, you step inside, and the aircraft takes off, flying above the traffic below.
Sound futuristic? Well, if Joby Aviation (NYSE: JOBY) has its way, scenes like that could become pretty ordinary over the next 10 years.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That aircraft in the imagined scenario above is an electric vertical takeoff and landing (eVTOL) aircraft, the very aircraft that Joby is developing. And if it can bring eVTOLs into widespread commercial use, then a $5,000 investment in Joby stock today could be worth considerably more in a decade. How much more? Let's take a look.
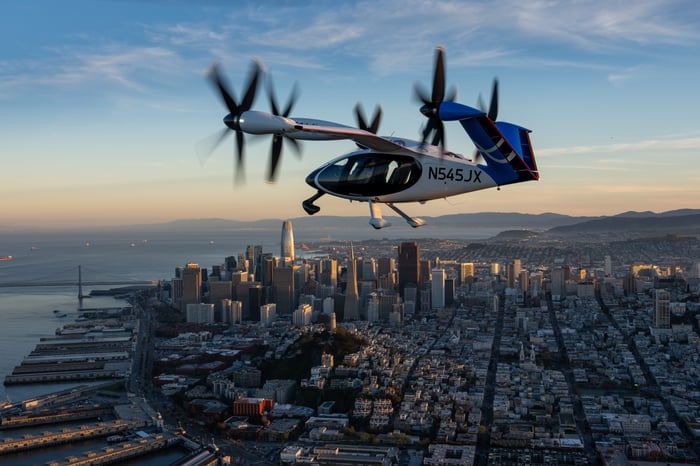
Image source: Joby Aviation.
How much could Joby be worth in 2036?
Joby is, as I said, developing an eVTOL aircraft for commercial passenger services. This aircraft will carry four passengers plus a pilot on short hops between cities, airports, and other urban destinations.
Currently, Joby has produced five of these eVTOLs, and it is targeting four aircraft per month in 2027. With support from its manufacturing partners Toyota (NYSE: TM), it wants to grow production to 500 aircraft a year. If it can achieve that kind of scale, Joby stock will look very different in 10 years.
So let's do some hypothesizing.
Let's imagine Joby has produced and is operating 2,500 eVTOLs in 2036. Let's also assume that the average flight will generate about $200 in revenue. Flying 24 times a day and 300 days a year, each eVTOL would generate about $1.5 million annually. With 2,500 of these in operation, Joby would generate about $3.6 billion annually from its passenger business.
If we assume a price-to-sales multiple of 3 (currently the average for aerospace and defense), then $3.6 billion in revenue could support a market cap of about $10.8 billion -- or roughly 125% higher than today's valuation. That would more than double your $5,000 investment to $11,250.
But will Joby more than double in 10 years?
That's an example of how Joby could grow substantially if its eVTOL business succeeds. Indeed, its passenger eVTOL service could become very lucrative, especially with a fleet of aircraft in the thousands.
But let's be real: Getting 2,500 aircraft into operation is no small feat. And there's no guarantee that its aircraft will complete 24 flights per day, nor that they will fly 300 days per year. And while Joby recently told Fox News it would charge $200 for trips between Manhattan and JFK, in reality, it might have to charge much less than that to attract consumers.
Still, I think Joby has a credible shot at becoming a much larger company over the next 10 years. Risks remain -- and getting the right certification is one -- but for aggressive investors with a long time horizon, shares of Joby could be worth buying today, at least before its eVTOLs become a familiar sight.
Steven Porrello has positions in Joby Aviation. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.