
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
We're Hopeful That MedPacto (KOSDAQ:235980) Will Use Its Cash Wisely
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
Given this risk, we thought we'd take a look at whether MedPacto (KOSDAQ:235980) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
How Long Is MedPacto's Cash Runway?
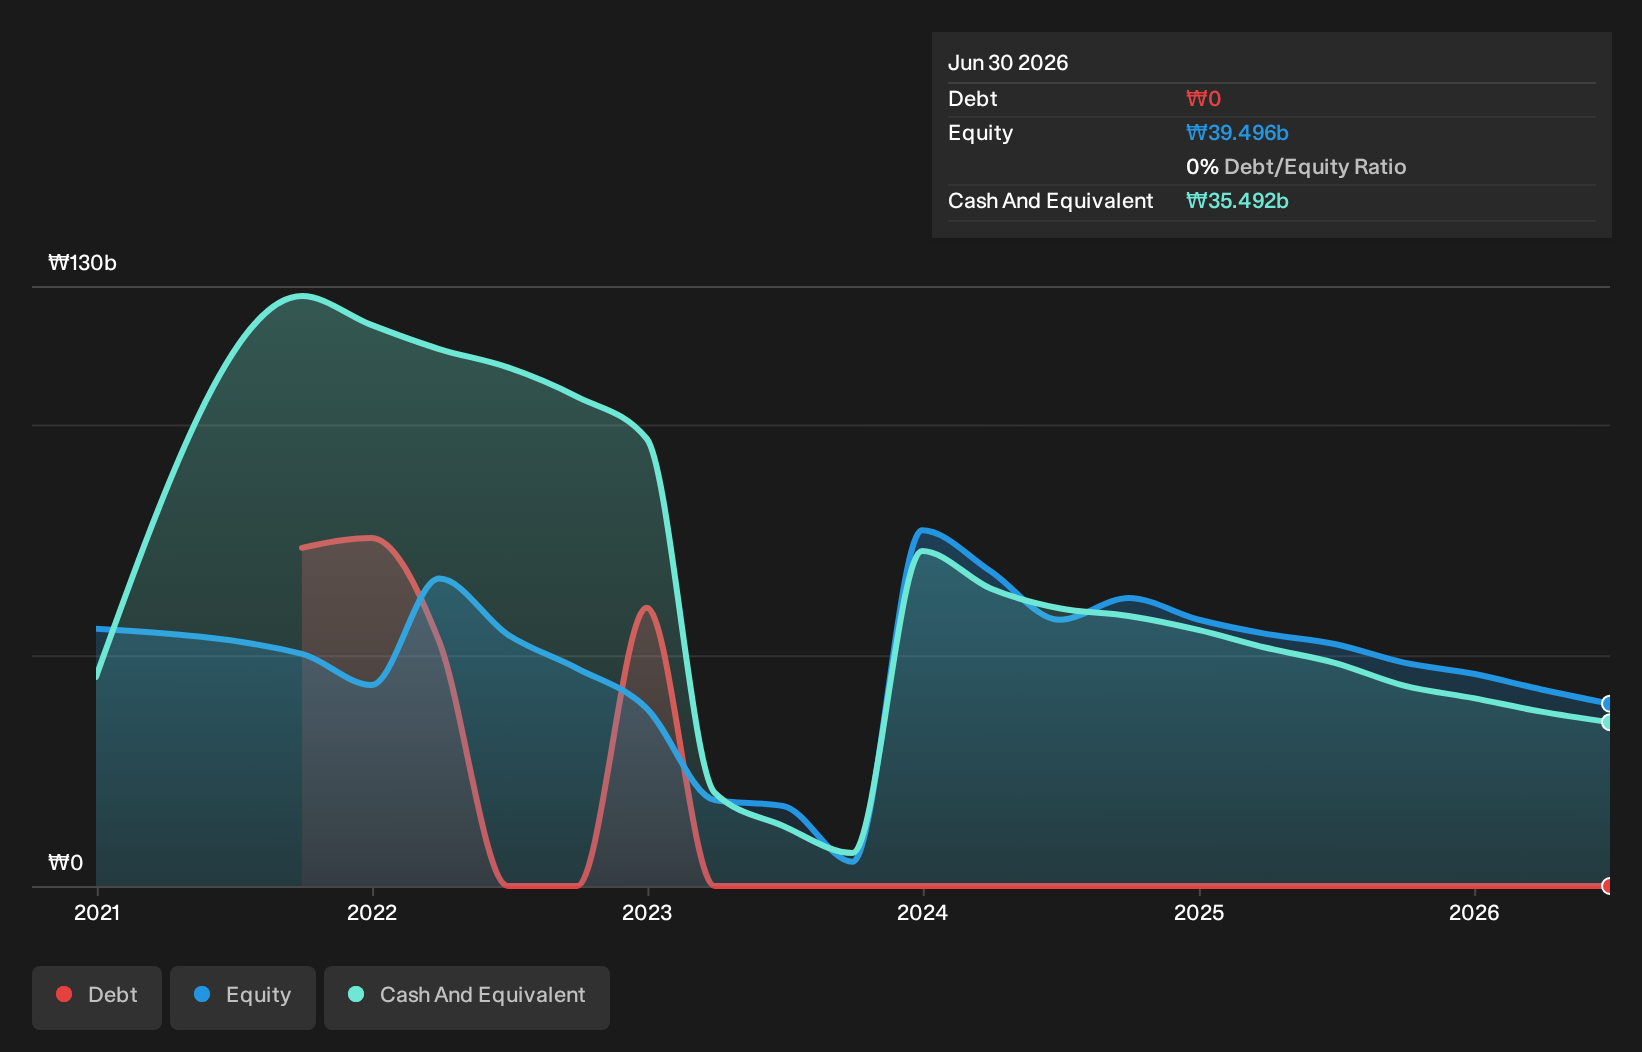
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, MedPacto had ₩35b in cash, and was debt-free. In the last year, its cash burn was ₩12b. That means it had a cash runway of about 2.9 years as of June 2026. That's decent, giving the company a couple years to develop its business. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for MedPacto
How Is MedPacto's Cash Burn Changing Over Time?
In our view, MedPacto doesn't yet produce significant amounts of operating revenue, since it reported just ₩5.0b in the last twelve months. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. With the cash burn rate up 12% in the last year, it seems that the company is ratcheting up investment in the business over time. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. In reality, this article only makes a short study of the company's growth data. This graph of historic revenue growth shows how MedPacto is building its business over time.
Can MedPacto Raise More Cash Easily?
While MedPacto does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Companies can raise capital through either debt or equity. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
MedPacto's cash burn of ₩12b is about 12% of its ₩108b market capitalisation. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
How Risky Is MedPacto's Cash Burn Situation?
As you can probably tell by now, we're not too worried about MedPacto's cash burn. For example, we think its cash runway suggests that the company is on a good path. Although its increasing cash burn does give us reason for pause, the other metrics we discussed in this article form a positive picture overall. Based on the factors mentioned in this article, we think its cash burn situation warrants some attention from shareholders, but we don't think they should be worried. An in-depth examination of risks revealed 3 warning signs for MedPacto that readers should think about before committing capital to this stock.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.