
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Aeon (TSE:8267) Undervalued As Half Year Earnings Reshape Its Dividend Plan?
Aeon (TSE:8267) just paired its half year earnings update with a reshaped dividend plan, including a stock split adjusted payout and a small commemorative dividend that reframes how shareholder returns are structured.
The recent dividend reshuffle comes after a difficult stretch for Aeon shareholders, with the share price down 53.7% year to date and 15.8% over 90 days. However, the 5-year total shareholder return of 40.06% still reflects gains built over a longer horizon.
Scan beyond Aeon and compare this dividend reset with other retailers by checking a hand picked group of list of solid balance sheet and fundamentals (22 results) that may handle shareholder returns differently.
Aeon still runs a broad retail and finance ecosystem across Japan and Asia, yet the reshaped dividend and sharp share price drop put a different question in front of you. Does the current valuation fairly reflect that platform today?
Most Popular Narrative: 17% Undervalued
Aeon last closed at ¥1,150.5, while the most followed narrative pegs fair value at ¥1,384.44. The debate shifts to whether its long term profit mix and execution can close that gap.
Expansion of Aeon private brands such as Topvalu toward a higher sales mix and larger absolute scale is intended to capture more gross profit per unit sold and support earnings resilience through a wider price and quality ladder.
Group wide joint procurement targeting a larger share of national brand volume and exceeding JPY 1 trillion in purchasing is designed to lift buying power, which can support both gross margin and operating profit if scale benefits flow through.
See why 6 investors see Aeon as 17% undervalued.
The prevailing storyline rests on a discounted cash flow view that uses a 6.67% discount rate and produces a fair value estimate of ¥1,384.44 for Aeon. Relative to that anchor, the current market capitalization of about ¥3.10t and the recent share price move leave the stock trading at roughly a 17% discount to this narrative fair value.
Support for that conclusion comes from analyst expectations that revenue grows modestly, profit margins edge toward 1.0%, and earnings move from ¥82.0b toward ¥125.9b by around 2029, although there is wide dispersion between the most optimistic and most cautious forecasts. To align with the ¥1,384.44 target, the narrative also assumes Aeon trades on a P/E of 37.0x those future earnings, which is materially higher than the 13.1x currently seen across the JP Consumer Retailing group.
The gap between the story and the quoted price leaves you with a clear task: decide whether Aeon can translate private brands, joint procurement, Health & Wellness formats, ASEAN growth, and data or AI projects into the revenue, earnings, and capital efficiency targets implied by that 6.67% discounted cash flow path.
Result: Fair Value of ¥1,384.44 (UNDERVALUED)
Still, the bullish Aeon storyline leans heavily on cost savings from digital projects and private brands, which could disappoint if execution proves slower or more expensive than expected.
Find out about the key risks to this Aeon narrative.
Another View: Market Ratio Signals For Aeon
The SWS DCF model flags a very different picture for Aeon. At ¥1,150.5, the shares are well above an estimated future cash flow value of ¥327.01, which screens as expensive on this framework and suggests limited room for error if cash flows fall short.
If you want to see how that cash flow output is built line by line and what assumptions drive it, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
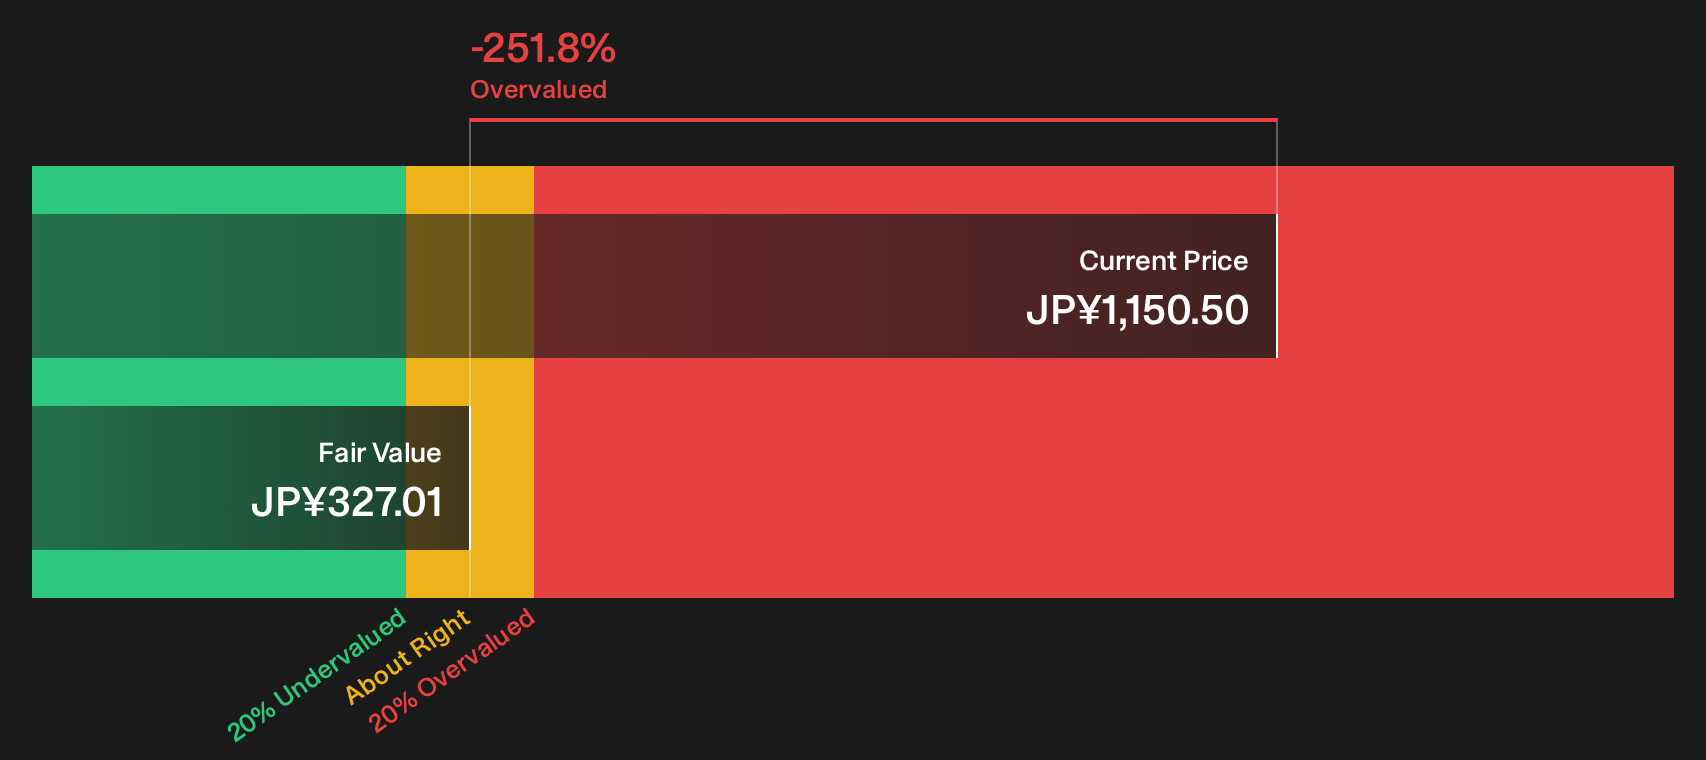
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aeon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Aeon feels familiar, act while the details are fresh and test the story against the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Aeon?
Do not stop with Aeon. Put this analysis in context by scanning other opportunities that fit clear themes and give you fresh angles on risk and return.
- Target resilient balance sheets and steady fundamentals by running a focused screen built around a list of solid balance sheet and fundamentals (22 results).
- Hunt for potential mispricings by filtering for businesses that combine quality metrics with valuation support through a dedicated 13 high quality undervalued stocks.
- Prioritize strength with a twist by zeroing in on 22 resilient stocks with low risk scores that may help you avoid unpleasant portfolio surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com