
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brown & Brown (BRO) Expands Marcus And Millichap Deal As Valuation Debate Builds
Brown & Brown (BRO) just widened its partnership with Marcus & Millichap into Canada, giving commercial real estate investors there tighter access to insurance placement, risk consulting and portfolio analysis support.
Recent trading has been a mixed read on sentiment around Brown & Brown. The share price is up 8.75% over the past week and 6.46% over 30 days, yet the year to date share price return is down 10.82% and the 1 year total shareholder return has declined 20.14%. This suggests that short term momentum is building after a weaker stretch for longer term holders.
Spot potential rebound candidates beyond Brown & Brown by scanning our hand picked 35 high quality undervalued stocks, which pair solid fundamentals with compressed valuations.Brown & Brown has rebounded in the past month yet remains below where it started the year. Does that reset give you a fair entry now, or does it argue for waiting until the valuation case looks cleaner?
Most Popular Narrative: 7% Undervalued
Brown & Brown’s most widely followed narrative points to a fair value of $74.75 a share, compared with the recent close at $69.22. That gap frames the current rebound as a debate about whether the market is still underpricing the business or correctly discounting its risks.
Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year and automating more than 25% of the submission process in many programs. This can free producers and underwriters to handle more volume and support future organic revenue growth and operating margin resilience.
See why 31 investors see Brown & Brown as 7% undervalued.
Result: Fair Value of $74.75 (UNDERVALUED)
Still, the bullish Brown & Brown narrative can crack if producer departures drag on Retail revenue, or if softer CAT property pricing keeps weighing on fee and commission income.
Find out about the key risks to this Brown & Brown narrative.
Another Angle On Brown & Brown’s Valuation
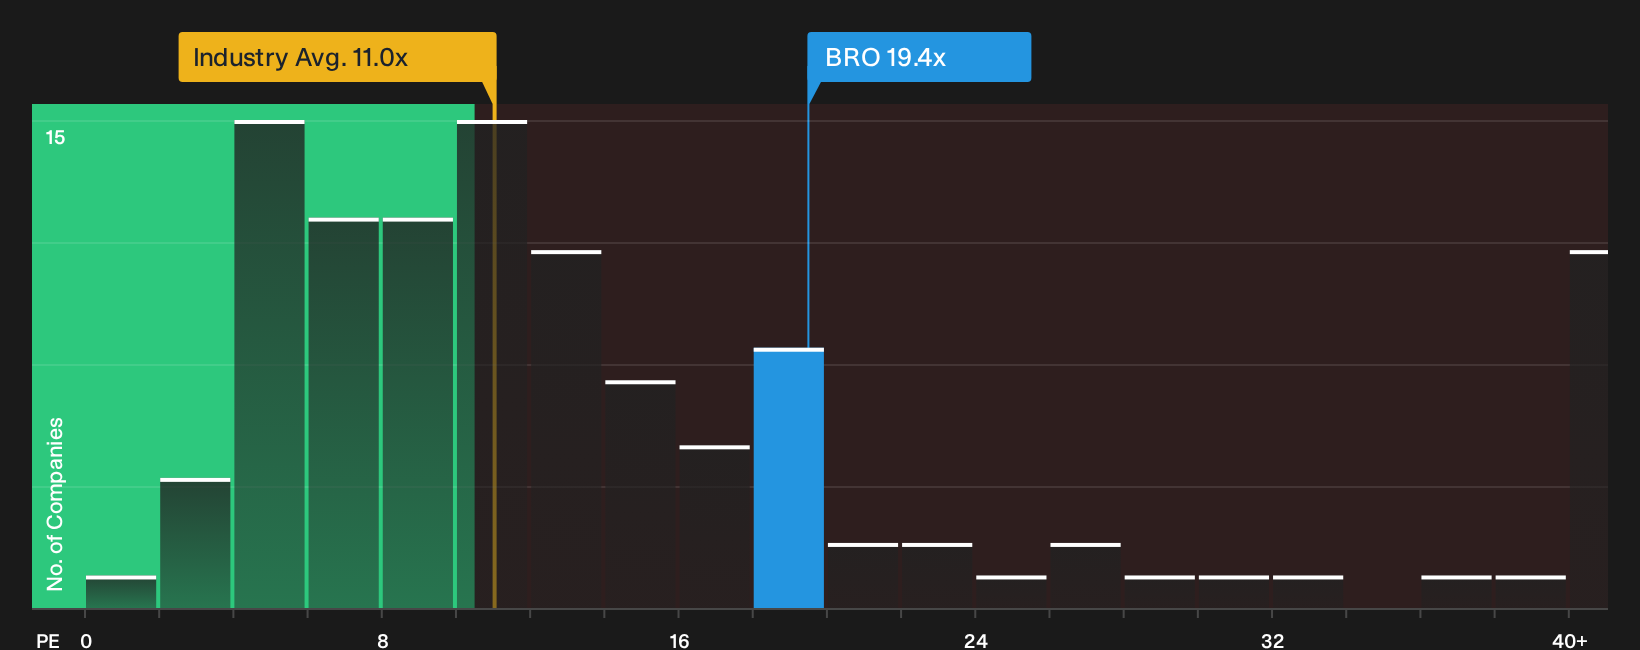
The fair value narrative for Brown & Brown leans on future earnings targets, yet the current P/E of 19.4x paints a different picture. That multiple is higher than the US Insurance industry at 11x and above the fair ratio of 11.9x, which signals less margin for error if growth or margins disappoint. Does that premium reflect quality, or is it asking too much for a stock that has lagged both the market and its sector over the past year?
To see how this price stacks up against earnings assumptions in more detail, review our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals all over this Brown & Brown story, which is exactly why it pays to move quickly and stress test the numbers yourself using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Brown & Brown?
If Brown & Brown has your attention, do not stop here. Broaden your watchlist with a few focused stock shortlists built from clear, data driven filters.
- Target potential mispricing by scanning companies that pair strong fundamentals with muted valuations through the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with higher yield potential and resilient payouts using the 8 dividend fortresses.
- Prioritise resilience by searching for companies with healthier balance sheets and solid financial footing via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com