
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Agios Pharmaceuticals (AGIO) Undervalued On Hopes For A Mitapivat FDA Decision?
Agios Pharmaceuticals (AGIO) is back in focus as traders weigh the upcoming FDA decision on accelerated approval for Mitapivat in sickle cell disease, a potential milestone supported by late-stage trial data.
At a share price of US$34.90, Agios Pharmaceuticals has seen sharp short-term momentum, with a 1-day share price return of 11.43% and a 7-day move of 13.24%, even though the 1-year total shareholder return is down 18.17% and the 3-year total shareholder return is up 66.51%. This combination signals that investors are reassessing both the opportunity and the risks around the upcoming Mitapivat decision.
See how traders are pricing similar rare disease stories by reviewing Agios Pharmaceuticals alongside the hand picked 20 high quality undiscovered gems that may be flying under most radars.
After a double digit weekly jump and a share price still sitting well below analyst targets and some intrinsic estimates, is the market appropriately cautious on Agios Pharmaceuticals, or mispricing the Mitapivat risk and reward?
Most Popular Narrative: 21% Undervalued
Against a last close of $34.90, the most followed narrative pins Agios Pharmaceuticals’ fair value at $44.00 and puts the spotlight firmly on whether the market is discounting its rare disease pipeline too heavily.
Upcoming potential FDA approval and commercial launch of PYRUKYND for thalassemia in the U.S. is set to significantly expand Agios' addressable market, driven by the high rate of disease diagnosis through newborn screening and well-defined patient populations, which should lift revenue growth in coming years.
See why 7 investors see Agios Pharmaceuticals as 21% undervalued.
The narrative applies a 7.15% discount rate to those future cash flows and arrives at a $44.00 fair value, which sits above both the current share price and the analyst consensus target range. That view leans heavily on high forecast revenue growth, a future profit margin assumption of 17.0%, and a future P/E multiple of 41.4x on projected 2029 earnings of $82.4 million, while also acknowledging execution, safety, and concentration risks around mitapivat and Aqvesme.
Result: Fair Value of $44.00 (UNDERVALUED)
Still, the bullish Agios Pharmaceuticals narrative leans heavily on mitapivat success and assumes that high spending, safety questions, and a concentrated rare disease focus do not bite harder than expected.
Find out about the key risks to this Agios Pharmaceuticals narrative.
Another View: Agios Pharmaceuticals Through a Sales Multiple Lens
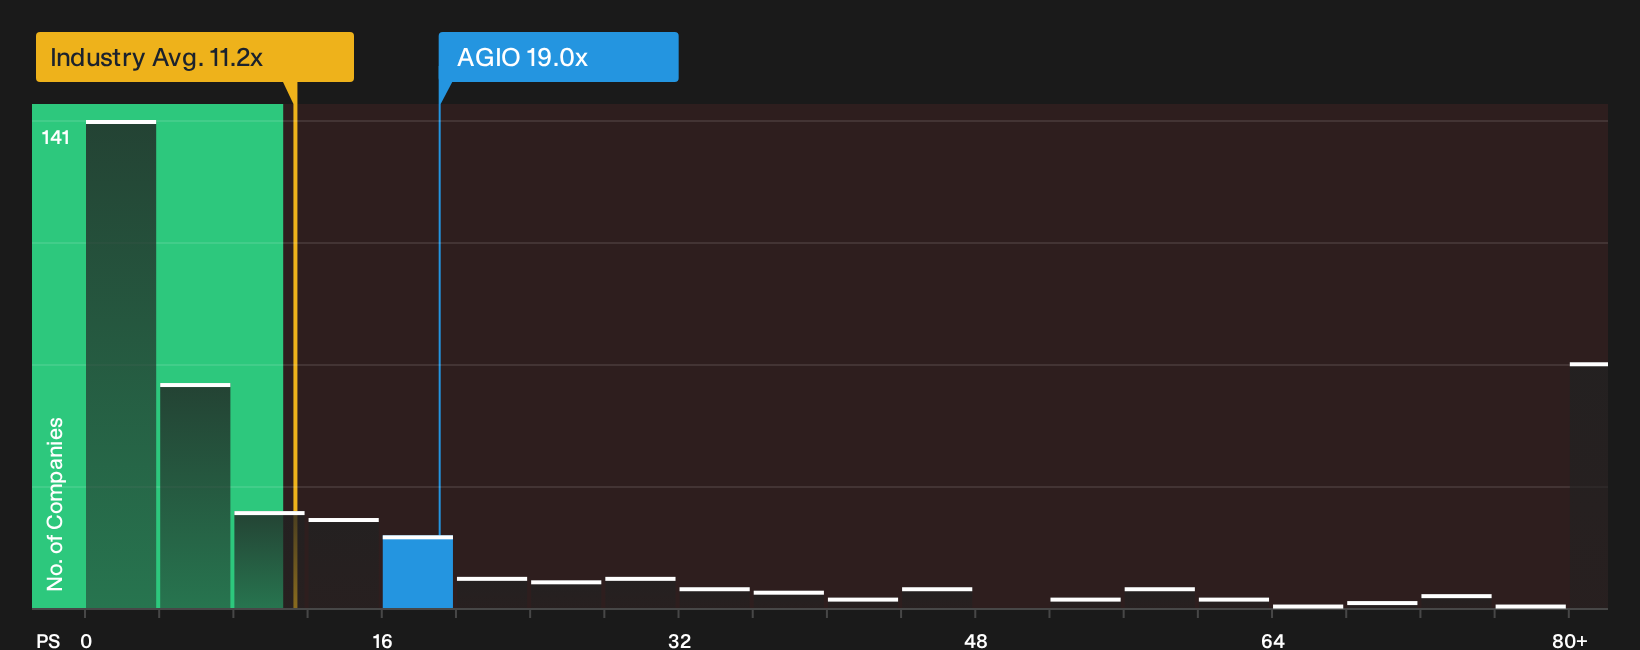
The upbeat fair value of $44.00 leans on future cash flow assumptions. A simple sales multiple tells a very different story. Agios Pharmaceuticals trades on a P/S of 19x, compared with 11.2x for the US Biotechs industry, while the fair ratio sits at just 0.2x. That gap points to meaningful valuation risk rather than a clear margin of safety. So which framework do you trust when expectations are this stretched?
Our preferred ratio view raises tough questions about how much optimism is already embedded in the current tag, and whether investors are paying ahead of the fundamentals for a still unprofitable rare disease story. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Agios Pharmaceuticals has clear bulls and skeptics in the mix, so move quickly, review the data yourself, and decide where you land on the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agios Pharmaceuticals?
If you only stop at Agios Pharmaceuticals, you miss a wider menu of opportunities that could better fit your risk profile, income needs, or value focus.
- Scan for resilient balance sheets and steady fundamentals by jumping into the list of solid balance sheet and fundamentals (25 results), which screens for financial strength upfront.
- Target stronger risk and reward trade offs by reviewing the 32 resilient stocks with low risk scores, which filters for businesses with more controlled risk profiles.
- Hunt for mispriced quality by using the 33 high quality undervalued stocks, which highlights companies combining solid fundamentals with discounted valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com