
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Weak Q3 Results Just Shift CleanSpark's (CLSK) Investment Narrative?
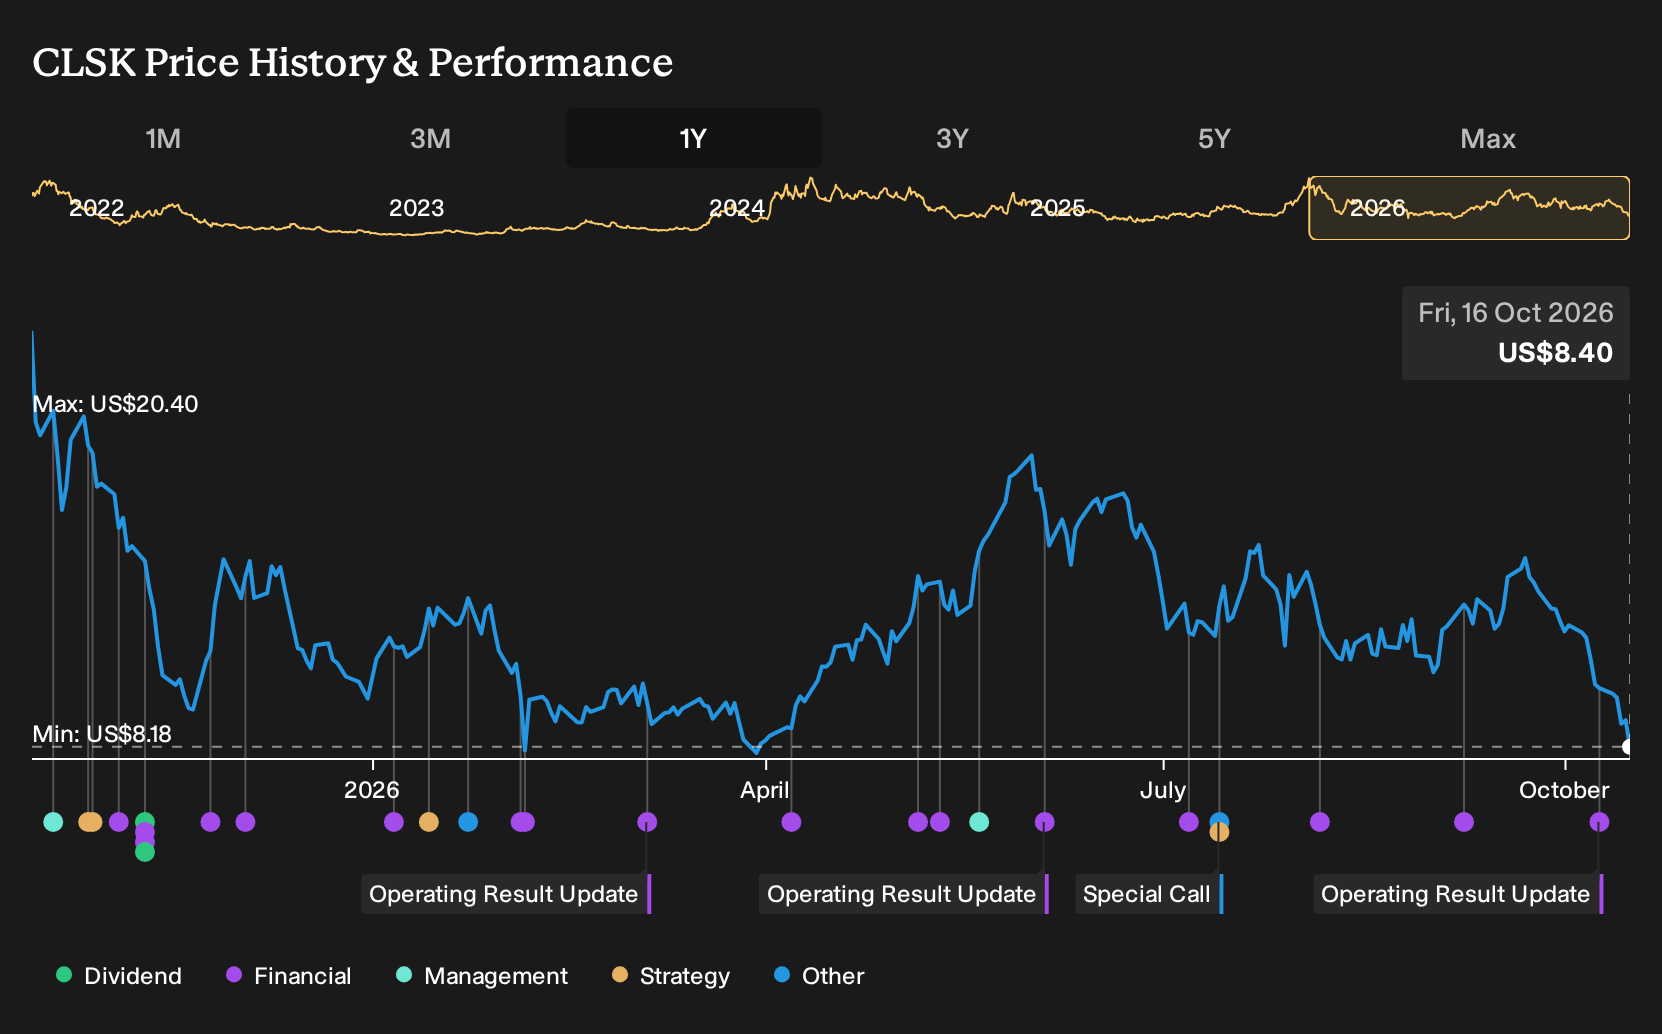
- CleanSpark reported unaudited bitcoin production of 529 coins for September 2026 and 5,432 coins for the year to date, alongside earlier fiscal Q3 results that showed revenue of US$138.01 million and a net loss of US$239.84 million.
- The miner is committing to long-duration infrastructure, including a 20 year triple net data center lease tied to US$6.6b of contracted revenue and US$2.28b of senior secured notes to fund expansion. This increases attention on how CleanSpark balances heavy investment with recent operating losses.
- We will now look at how CleanSpark's investment narrative is affected by its large data center commitments and recent reported net loss.
Scan how other bitcoin miners are handling heavy capital commitments and balance sheet pressure by reviewing our curated list of 18 cryptocurrency and blockchain stocks that echo the crosswinds around CleanSpark today.
CleanSpark Investment Narrative Recap
To own CleanSpark, you need to be comfortable with a pure bitcoin mining play that is leaning into scale, long duration infrastructure, and heavy upfront spending. The short term hinge is whether current production levels, like 529 bitcoin in September and 5,432 year to date, can support day to day liquidity while funding that build out.
The biggest immediate risk is the combination of recent net losses and large fixed commitments against a less than one year cash runway. Recent results do not change that core tension. Execution now largely comes down to how efficiently CleanSpark can ramp new capacity, manage energy costs, and handle bitcoin price swings without repeatedly stretching the balance sheet.
The 20 year triple net data center lease tied to US$6.6b of contracted revenue is the announcement that matters most here. It locks in long term hosting obligations and potential revenue visibility, and it also raises the bar on utilization, uptime, and operating efficiency once deliveries start in late 2027.
For you as a shareholder, that lease and the US$2.28b of senior secured notes concentrate the story around execution and refinancing risk. These commitments can amplify the impact of any future change in bitcoin pricing, regulation, or energy costs and can turn operational discipline into the key catalyst for how the CleanSpark stock story evolves from here.
CleanSpark's current consensus narrative points to revenues of US$857.1 million and earnings of US$98.0 million by 2029, based on assumed yearly revenue growth of 8.1% and an earnings change of roughly US$1.098b from a loss of US$1.0b today to positive territory.
Uncover why CleanSpark's fair value indicates a 183% potential upside to its current price, a discount that could close faster than you expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a very different catalyst for CleanSpark. They lean on the US$6.6b Sandersville lease and projected US$1.2b of revenue and US$12.5m of earnings by 2029 as a future AI and data center engine. Those projections came before this production update, so you should expect opinions to shift and compare several viewpoints yourself.
Explore 4 other CleanSpark fair value estimates, including one that suggests as much as 221% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your CleanSpark research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CleanSpark's overall financial health at a glance.
Looking For More Investment Ideas Beyond CleanSpark?
If the CleanSpark story has you thinking about portfolio balance, it can help to scan a wider field of opportunities using the Simply Wall St Screener and see how other businesses stack up on quality, valuation, and resilience.
- For readers who want potential mispricing with fundamentals in focus, start with a curated set of 33 high quality undervalued stocks that pair financial strength with a market price that may not fully reflect it yet.
- If capital preservation sits high on your priority list, consider a 32 resilient stocks with low risk scores that tilts toward businesses with steadier balance sheets and fewer obvious red flags.
- When you are hunting for future standouts before they become widely followed, scan our 20 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com