
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
7% Above Fair Value? Scandic Hotels Group (OM:SHOT) On Hilton Nordic Hotel Deal
Scandic Hotels Group (OM:SHOT) just signed a multi year agreement with Hilton to pursue new hotel projects across the Nordics, starting with a planned Hilton hotel near Copenhagen Airport in 2029.
Scandic Hotels Group’s agreement with Hilton lands at a time when momentum is already picking up, with a 30 day share price return of 12.46% and a 90 day gain of 24.70%. The 1 year total shareholder return of 20.04% sits on top of very strong 3 and 5 year total shareholder returns of 213.07% and 191.21% respectively.
Scan the Nordic hospitality space for other companies with hotel exposure and similar momentum by running the curated 613 high quality undiscovered gems alongside Scandic Hotels Group.
Bulls point to Scandic Hotels Group’s Hilton tie up and past returns as proof the rerating has more room to run. Bears see stretched P/E and execution risk. Which side do the numbers actually support next?
Most Popular Narrative: 7% Overvalued
Against the last close at SEK100.20, the most followed narrative pegs Scandic Hotels Group’s fair value at SEK93.86. This implies the recent Hilton news is being layered onto an already full valuation built on strong growth assumptions and a relatively demanding discount rate of 10.42%.
Scandic is seeing strong booking trends for the spring and summer seasons, with expectations of increased average room rates and occupancy compared to last year, supporting future revenue growth.
A new hotel with 214 rooms is planned to open in Berlin in the second half of 2026, part of efforts to grow their hotel portfolio, which is expected to provide a positive impact on future revenue.
See why 10 investors see Scandic Hotels Group as 7% overvalued.
Result: Fair Value of SEK93.86 (OVERVALUED)
Still, Scandic Hotels Group faces real pressure if Finland pricing softens further or if new capacity there keeps squeezing occupancy, which could undercut the current rerating story.
Find out about the key risks to this Scandic Hotels Group narrative.
Another View: DCF Points in a Different Direction
The first narrative leans on analyst targets that suggest Scandic Hotels Group is around 7% overvalued at SEK100.20 against a SEK93.86 fair value. A second lens tells a very different story. The SWS DCF model estimates future cash flows at SEK292.04 per share, which implies the stock trades well below that cash flow value today. That kind of gap can mean a valuation cushion if the cash flow path materialises, or it can signal that expectations inside the model are more optimistic than the market is willing to accept right now.
Before leaning on that result, it is worth seeing how the SWS DCF model gets to such a different answer for Scandic Hotels Group, and which assumptions you agree with most. Look into how the SWS DCF model arrives at its fair value.
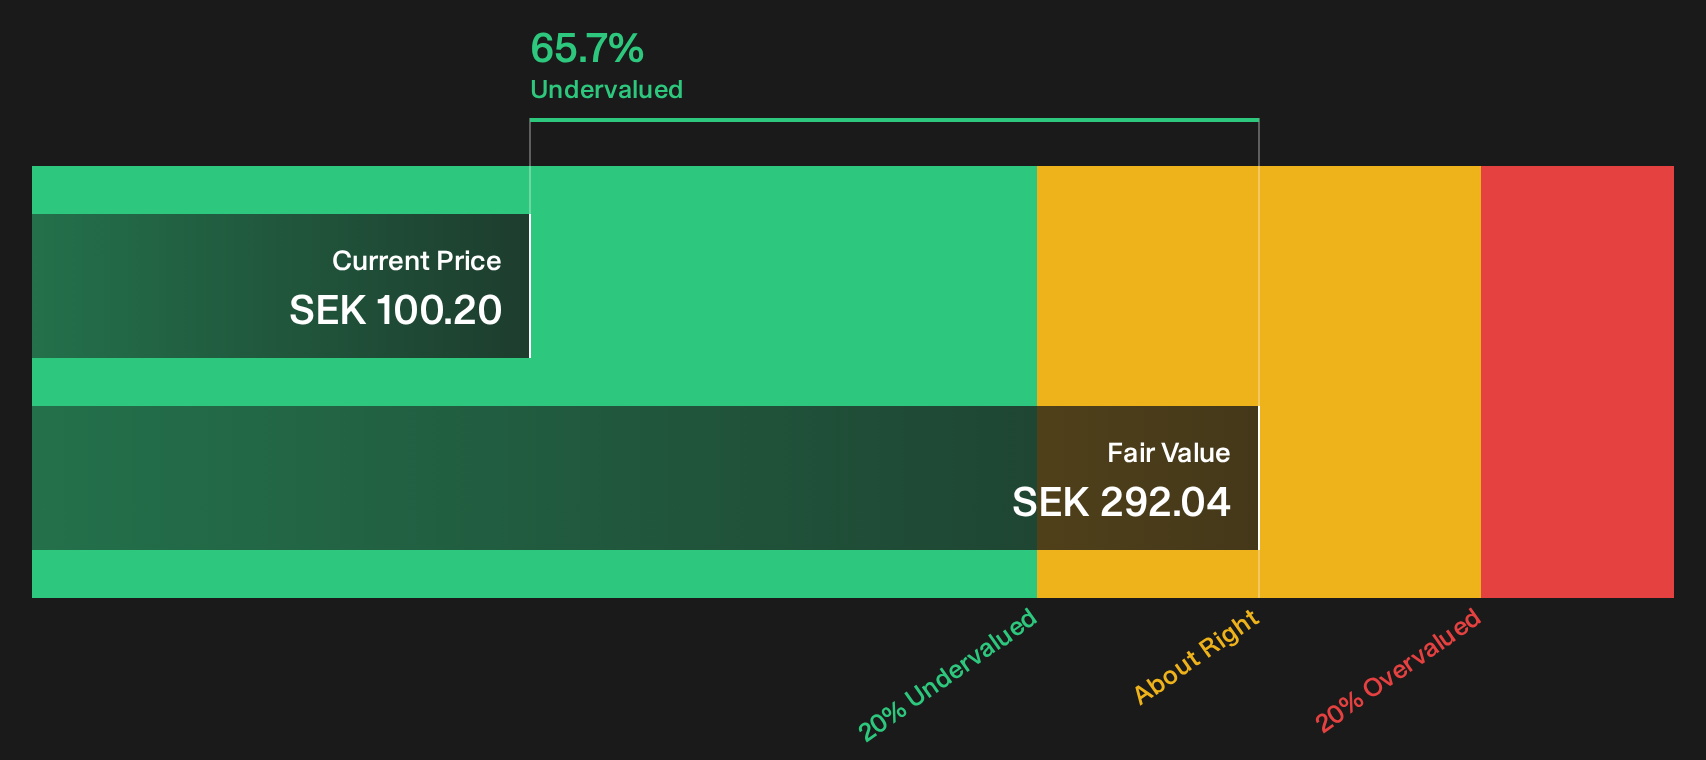
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scandic Hotels Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The sentiment around Scandic Hotels Group is split, with solid past returns on one side and valuation questions plus execution risk on the other. Move quickly, review the underlying data for yourself, and weigh both the potential upsides and pressure points captured in our 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Scandic Hotels Group?
If you stop with Scandic Hotels Group, you risk missing other opportunities that fit your style, your time horizon, and your tolerance for volatility.
- Target reliable income and focus your watchlist on companies that skew toward predictable cash returns by using the 217 dividend fortresses.
- Hunt for quality at a price and sharpen your bargain-hunting edge with the curated 196 high quality undervalued stocks.
- Prioritise resilience and protect your downside potential by filtering for businesses with stronger finances through the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com