
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Electra (TASE:ELTR) Could Be 61% Below Fair Value After Norway EL2 Flight Plans
Bristow Group, Electra (TASE:ELTR), Avinor and Norway’s aviation regulator plan hybrid-electric EL2 test flights at five Norwegian sites in 2027, giving investors a fresh angle on Electra’s role in sustainable aircraft development.
Electra’s latest aviation announcement lands as momentum starts to rebuild in the share price, with a 1-day share price return of 1.73% and a 7-day share price return of 6.29% offsetting a softer 90-day share price return that declined 4.62%. At the same time, the 3-year total shareholder return of 85.92% points to a much stronger longer run for investors than the recent quarterly dip implies.
Scan beyond Electra and identify other potential beneficiaries of the shift to cleaner infrastructure by reviewing our hand picked 231 resilient stocks with low risk scores featuring balanced fundamentals and resilient profiles.
Electra trades at a sizeable intrinsic discount even after the recent rebound. Is the market rightly cautious about execution and capital intensity, or is it mispricing the long term value on offer ahead of the detailed valuation work?
Price-to-Earnings of 44.1x for Electra: Is it justified?
Electra changes hands at a P/E of 44.1x, which sits below a 102.7x peer average yet above the 35.4x figure for the wider IL Construction group. As a result, the market is assigning the stock a mixed valuation signal at a ₪111.5 share price.
The P/E ratio links what investors are paying today for each unit of current earnings. For a contracting and infrastructure group like Electra, that figure often reflects how dependable investors believe future project cash flows and profitability will be, rather than just the last reported year.
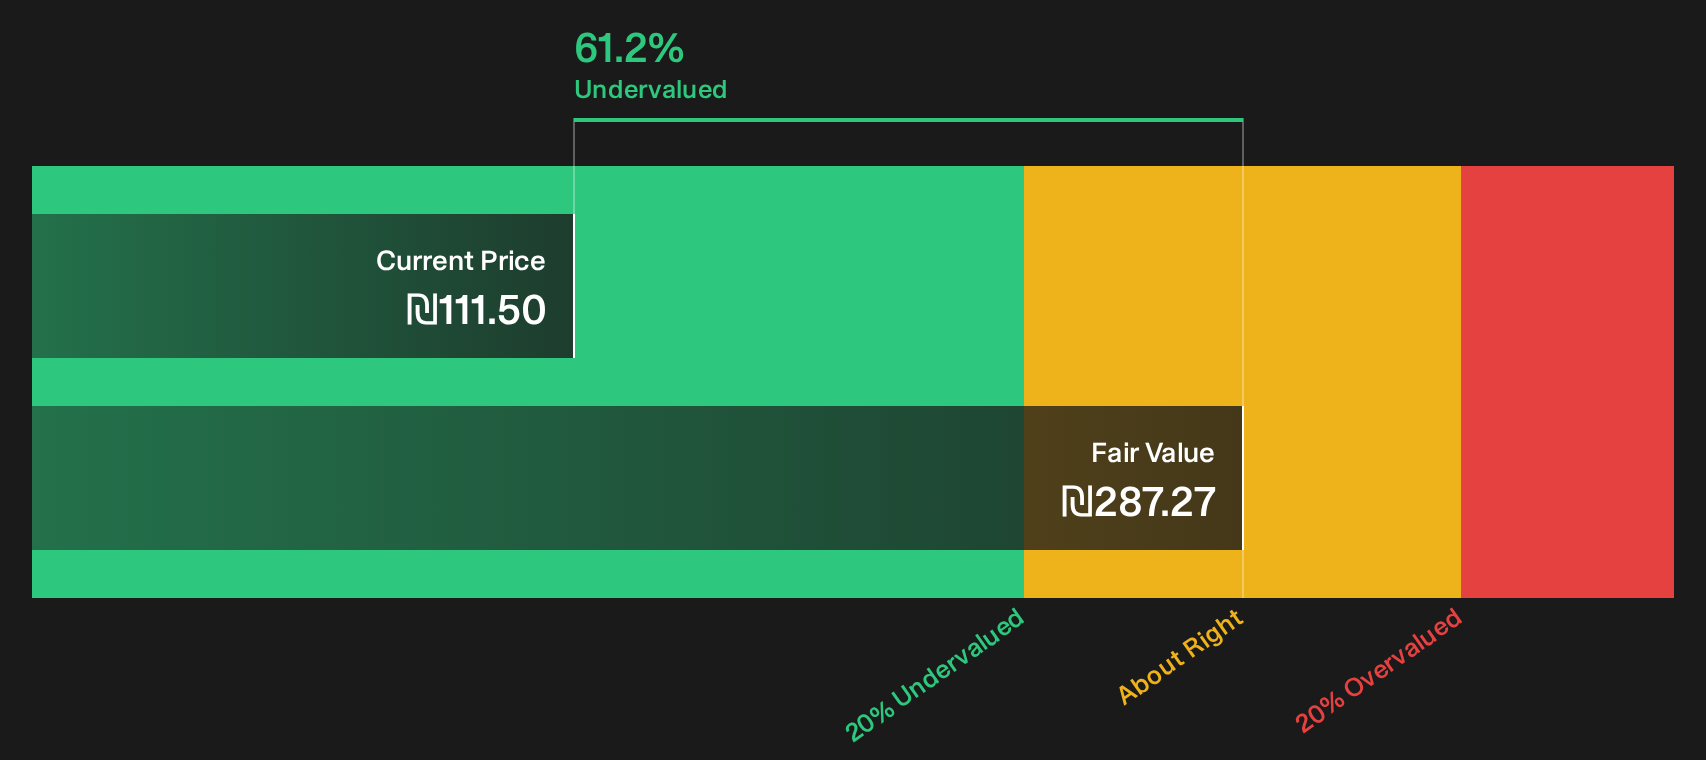
Here, the SWS DCF model flags Electra as trading at a large discount to an estimated future cash flow value of ₪287.27. However, the high absolute P/E level and weaker recent earnings record, including a decline of 4.5% per year over the past 5 years and a one off gain of ₪66.0m in the last twelve months, point to a more complicated picture of quality and sustainability behind those profits.
Against the IL Construction industry average P/E of 35.4x, Electra screens as expensive on this single metric, even though it appears cheap relative to the much higher 102.7x peer average. This suggests the market is neither pricing it as a bargain across the sector nor as the most stretched option among closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 44.1x (ABOUT RIGHT)
Still, execution risk around large construction projects, alongside the capital demands of ventures like hybrid-electric aircraft, could easily disrupt the current Electra valuation story.
Find out about the key risks to this Electra narrative.
Another View on Electra’s Value
The earnings multiple paints Electra as reasonably priced, yet the SWS DCF model points to a very different story. At a market price of ₪111.5 versus an estimated future cash flow value of ₪287.27, the stock screens as deeply undervalued. Which signal do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Electra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Electra, the story clearly mixes optimism and caution, so move quickly and review the full picture of both by checking the 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Electra?
Do not stop with Electra. Use Simply Wall Street’s tools to pressure test your thinking against a wider set of opportunities before committing fresh capital.
- Target potential bargains early by scanning our hand picked 196 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 217 dividend fortresses.
- Prioritise resilience first by focusing on businesses from the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com