
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rathbones Group (LSE:RAT) Could Be 21% Undervalued On Integration Synergy Hopes
New director appointment and completed integration reshape the story
Rathbones Group (LSE:RAT) has brought Michelle Sylvia Scrimgeour onto its board as a director, shortly after completing the Investec Wealth & Investment integration that management links to planned margin improvements.
Rathbones Group’s recent appointment and the completed Investec Wealth & Investment integration arrive after a year where the share price return is down 16.5% year to date, even though the 3 year total shareholder return is up 23.4%. This suggests recent momentum has faded while longer term holders have still seen gains.
Scan how Rathbones Group compares on quality and value beside other wealth managers by lining it up against our curated 8 high quality undervalued stocks.
Rathbones Group shares have fallen this year while analyst targets and intrinsic value models sit meaningfully higher. The next step is to see where fair value really clusters between that trading price and the spread of estimates.
Most Popular Narrative: 21% Undervalued
Rathbones Group last closed at £15.98 while the most followed narrative pegs fair value closer to £20.12, so the gap between price, analyst expectations and intrinsic value models is doing most of the heavy lifting in this story.
The completion of the Investec Wealth & Investment (IW&I) integration unlocks significant scale advantages and operational synergies, providing a tangible opportunity to improve operating margins. Management expects these efficiencies to result in a 28% margin by Q4 2026 (from 25.4%), with full synergy benefit (~£60m annualized) set to be realized by the end of 2025. The remaining upside (target 30%) is described as dependent on organic growth in AUM and advice revenues.
See why 6 investors see Rathbones Group as 21% undervalued.
Result: Fair Value of £20.12 (UNDERVALUED)
Still, margin pressure from lower fee products and the risk that integration synergies arrive slower than expected could quickly weaken the bullish narrative around Rathbones Group.
Find out about the key risks to this Rathbones Group narrative.
Another View: Rathbones Group Through The P/E Lens
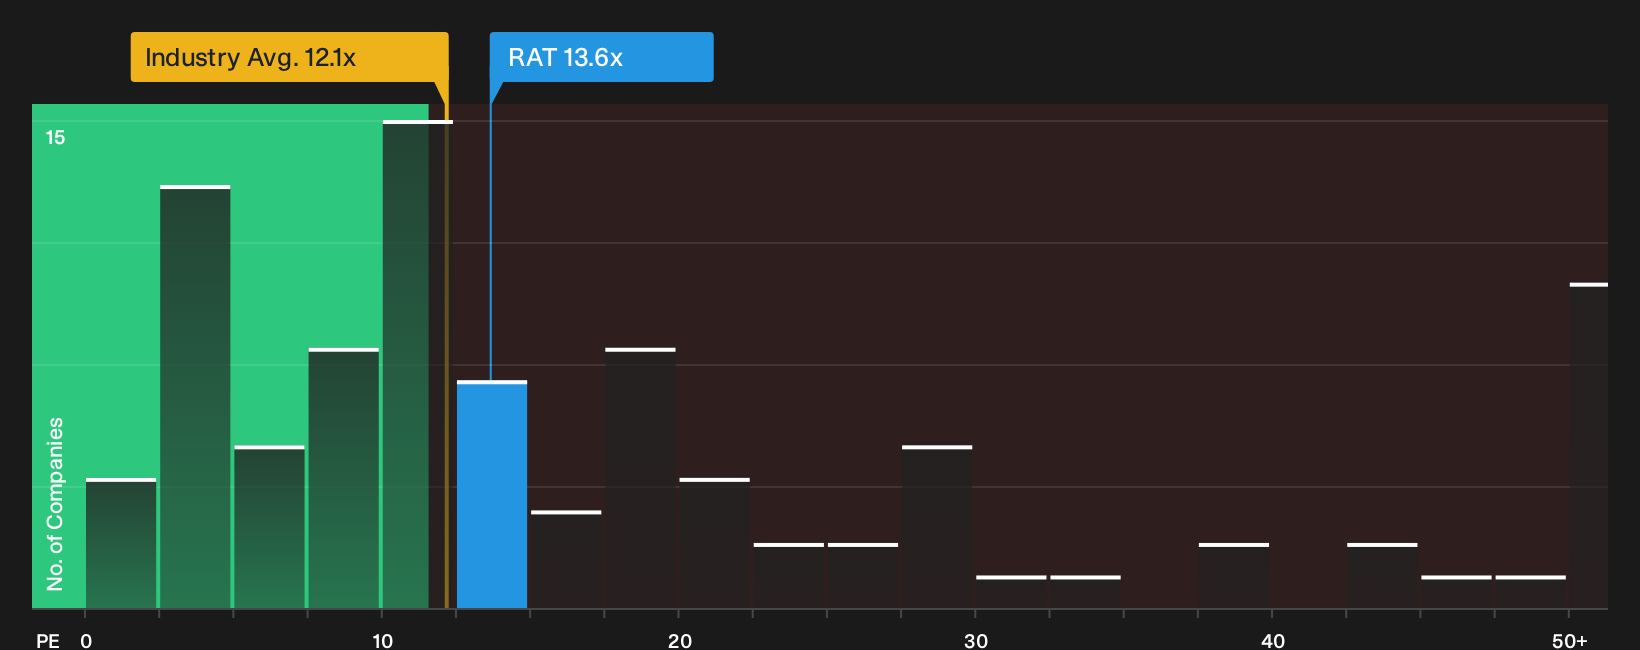
While Rathbones Group screens as undervalued against an internal fair value of £27.52, its P/E of 13.6x tells a different story. That multiple sits above the UK Capital Markets industry at 12.1x and above peer averages at 10.4x, yet is close to a fair ratio of 13.8x. For investors weighing margin ambitions against richer peer comparisons, the question is whether this gap signals a cushion or a thin margin for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Rathbones Group is clearly mixed, with both pressure points and bright spots on the table. Review the data for yourself, decide where you stand, and then weigh those signals against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Rathbones Group?
You have a clear view on Rathbones Group now. Do not stop there. Broaden your watchlist and pressure test your thesis against other opportunities.
- Target potential mispricings by scanning the 8 high quality undervalued stocks that combine solid fundamentals with price tags that may not fully reflect their financial profile.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (9 results) so you can focus on businesses that carry less financial strain when conditions change.
- Hunt for tomorrow's stories early by checking a 5 high quality undiscovered gems before attention and liquidity shift toward them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com