
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Smart Home Rollout Alter The Investment Case For Canadian Tire (TSX:CTC.A)?
- Aqara announced that its smart home devices, including sensors, cameras and locks, are now sold through more than 500 Canadian Tire locations across Canada, marking Aqara’s retail entry into the country.
- The agreement gives Canadian Tire Corporation fresh exposure to connected home hardware that ties into major smart platforms, which could help deepen customer engagement across its wider retail ecosystem.
- Now the focus shifts to how this wider smart home assortment at Canadian Tire could influence the existing investment narrative around earnings mix.
Canadian Tire Corporation Investment Narrative Recap
For Canadian Tire Corporation, the big picture is simple. You need to believe its True North retail integration, Triangle loyalty and financial services arm can steadily compound earnings even while headline revenue growth is modest and CTFS expenses sit near 28% of segment revenue. The Aqara smart home rollout fits this view as another way to deepen in store relevance rather than a new growth engine on its own.
The more pressing near term swing factor is whether margin work, including AI driven pricing and assortment tools, actually shows up in cleaner earnings quality after a year where net profit margins moved from 4.8% to 4.1%. The main risk still looks tied to elevated spend and legal exposure around the 2025 data breach, not this smart home partnership.
The Aqara launch across more than 500 stores lines up most closely with Canadian Tire Corporation’s push to refine pricing and category roles using AI and shared data. Connected devices give management a fresh, higher ticket category where those tools can pressure test promotion depth, attachment rates and how Triangle members respond to more technical assortments.
For you as a shareholder, the interest is less about smart locks or leak sensors and more about execution proof points. If the AI platforms and True North playbook can keep shoppers engaged in new categories like smart home while CT REIT rent and the 3% plus dividend profile remain supported, that reinforces the current earnings mix story. Weak uptake or heavy discounting would instead highlight how reliant the thesis is on disciplined SG&A and credit costs at CTFS.
Canadian Tire Corporation's current analyst narrative points to revenue of CA$17.5b and earnings of CA$797.2m by 2029. That profile assumes 2.0% yearly revenue growth and an earnings increase of about CA$118m from CA$679.2m today.
Uncover why Canadian Tire Corporation's fair value is essentially in line with its current price.
Exploring Other Perspectives
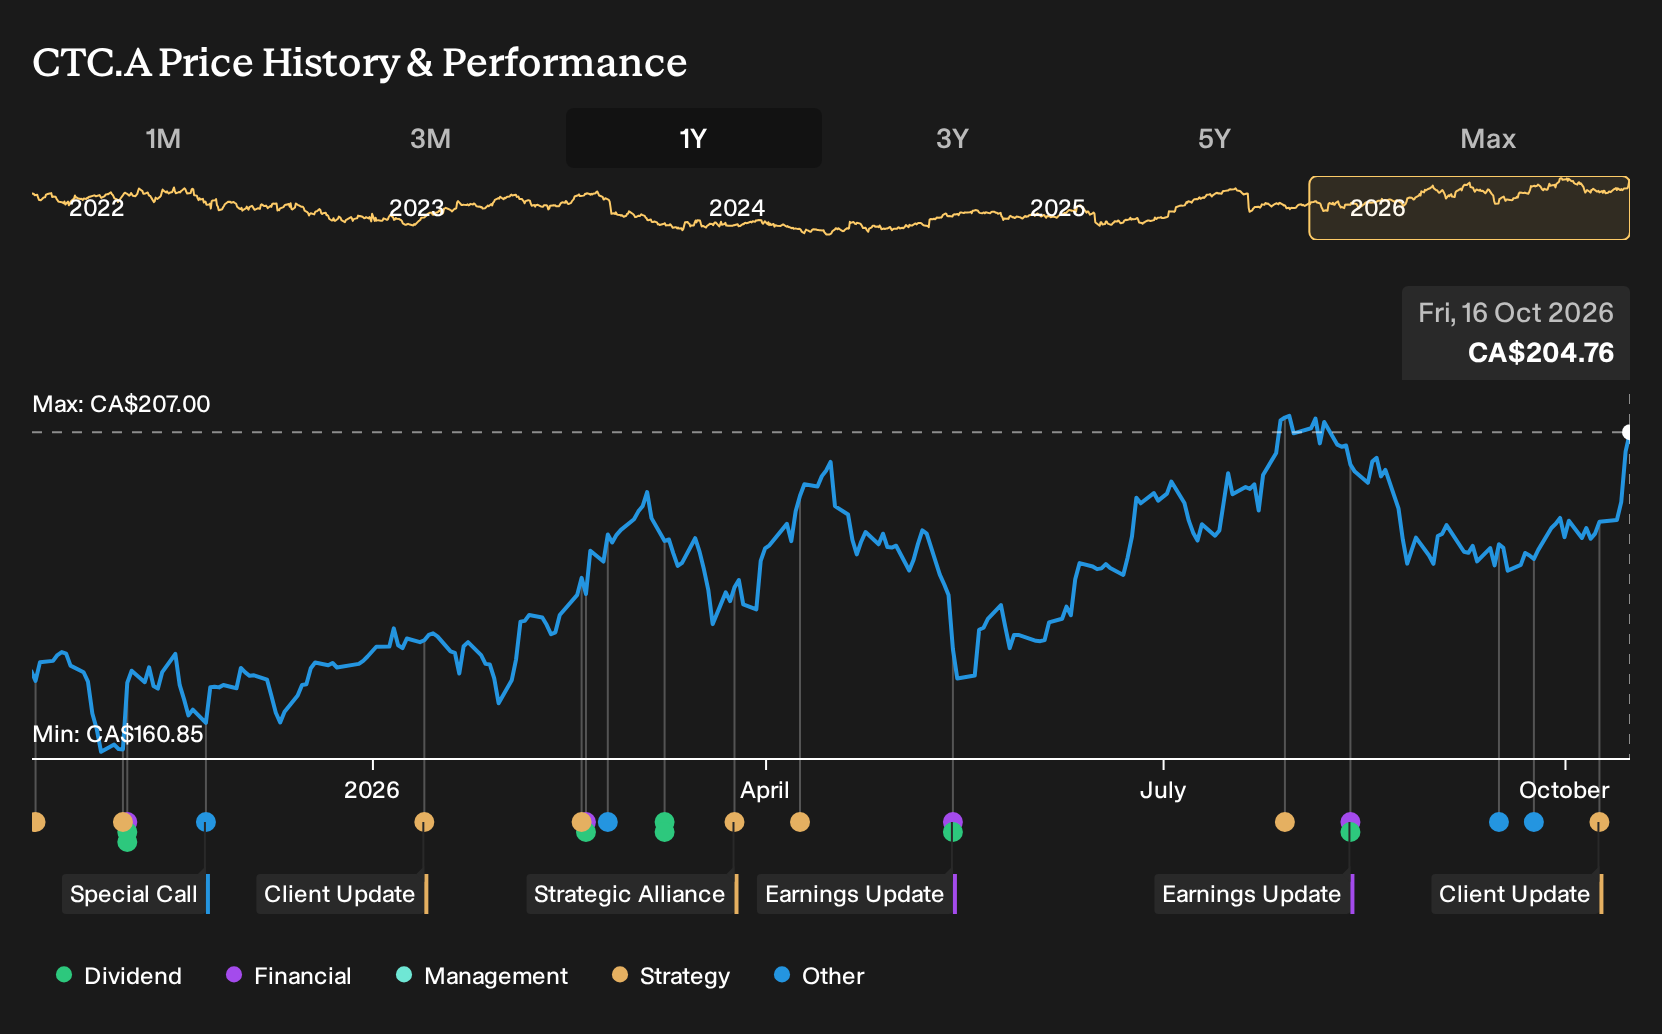
You can see how split the Simply Wall St Community is here. Three fair value estimates cluster between about CA$154.93 and CA$206.60, which leaves plenty of room for arguments about Canadian Tire Corporation being either stretched or cheap. When you also consider the unresolved 2025 data breach class action, it serves as a reminder that legal costs, customer trust and any shift in the P/E multiple could matter as much as smart home buzz. Use these competing views as a prompt to compare several alternative takes before deciding how this story fits into your own portfolio.
Explore 2 other Canadian Tire Corporation fair value estimates, including one that suggests as much as 24% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Canadian Tire Corporation research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian Tire Corporation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Tire Corporation's overall financial health at a glance.
Looking for more Canadian Tire Corporation style ideas?
If the Aqara rollout has you thinking more broadly about where connected hardware, data and recurring engagement could matter, it might be a good time to widen the search beyond Canadian Tire Corporation using the Simply Wall St Screener.
- If capital preservation is high on your list, start with companies that score well on balance sheet strength using the list of solid balance sheet and fundamentals (8 results) to see which businesses pair financial resilience with cleaner fundamentals.
- If you are hunting for income, focus on stocks that combine higher yields with staying power by scanning through the 3 dividend fortresses and sorting for payout profiles that better match your risk tolerance.
- If you want potential upside with quality filters already in place, look across the 10 high quality undiscovered gems and compare how those businesses stack up on earnings, cash flow and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com