
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AB Industrivärden (OM:INDU A) Faces A 72% Fair Value Gap As Mixed Earnings Land
AB Industrivärden earnings jolt puts recent results under the microscope
AB Industrivärden (OM:INDU A) caught investor attention after reporting a third quarter net loss of SEK 1,653 million alongside nine month net income of SEK 35,402 million, a sharp contrast that raises fresh questions.
The mixed earnings picture seems to be landing on a stock that has already cooled off in the short term, with the 30 day share price return down 4.63% even as the year to date share price return sits at 25.18%. AB Industrivärden’s longer track record still looks strong through a different lens, with 1 year total shareholder return of 33.96% and 5 year total shareholder return of 104.63%, which suggests that recent volatility is being weighed against a much stronger multi year experience for investors.
Spot similar high-return investment managers reacting to earnings swings by scanning our hand picked list of 613 high quality undiscovered gems tied to strong long term track records.The recent pullback in AB Industrivärden after a quarter in the red contrasts with a strong nine-month profit picture. Do you increase your position now, or wait for a cheaper entry while you evaluate the valuation more closely?
Preferred P/E of 4.1x for AB Industrivärden: Is it justified?
AB Industrivärden screens as cheap on earnings, with a P/E of 4.1x at a last close of SEK514.5, while still carrying a long track record of profit generation and high reported returns on equity.
P/E compares what investors pay for each unit of earnings, so a lower multiple often signals either a bargain or scepticism about how durable those profits are. For an investment manager like AB Industrivärden, where reported earnings can be heavily influenced by non cash revaluations, that distinction matters a lot when you interpret a headline ratio.
The stock trades on this 4.1x P/E against a peer group average of 5.9x and a European diversified financials benchmark of 10x. That is a steep gap, and it sits alongside an internal estimate that values the shares at a large premium to the current SEK514.5 price, based on a SWS DCF model fair value of SEK1,785.55.
Our DCF model projects AB Industrivärden's expected future cash flows and discounts them back to today using an assumed required rate of return. This approach places less weight on short term accounting swings, which can be heavily affected by non cash earnings, and more on the longer term cash generation profile of the investment portfolio.
For an investor assessing AB Industrivärden, that DCF result highlights how sensitive valuation can be to assumptions about future cash flows and discount rates, particularly for a business whose reported earnings have moved very sharply in recent periods. It also underlines why a simple earnings multiple may not tell the whole story when a high proportion of income is non cash.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of SEK1,785.55 (UNDERVALUED)
Still, AB Industrivärden’s reliance on equity market valuations and a single revenue segment means that sharper portfolio swings or concentration risk could quickly challenge this DCF story.
Find out about the key risks to this AB Industrivärden narrative.
Another view on AB Industrivärden’s valuation
There is a sharp split between the simple P/E story and the SWS DCF model for AB Industrivärden. The market values the shares at SEK514.5, while the cash flow based fair value estimate sits at SEK1,785.55, which frames the stock as heavily undervalued on that method.
Such a wide gap can reflect how investors treat highly non cash earnings and equity market exposure, or it can flag a mispricing that only closes slowly. The key question is which signal you trust most when profits swing and forecasts are thin on the ground.
Look into how the SWS DCF model arrives at its fair value.
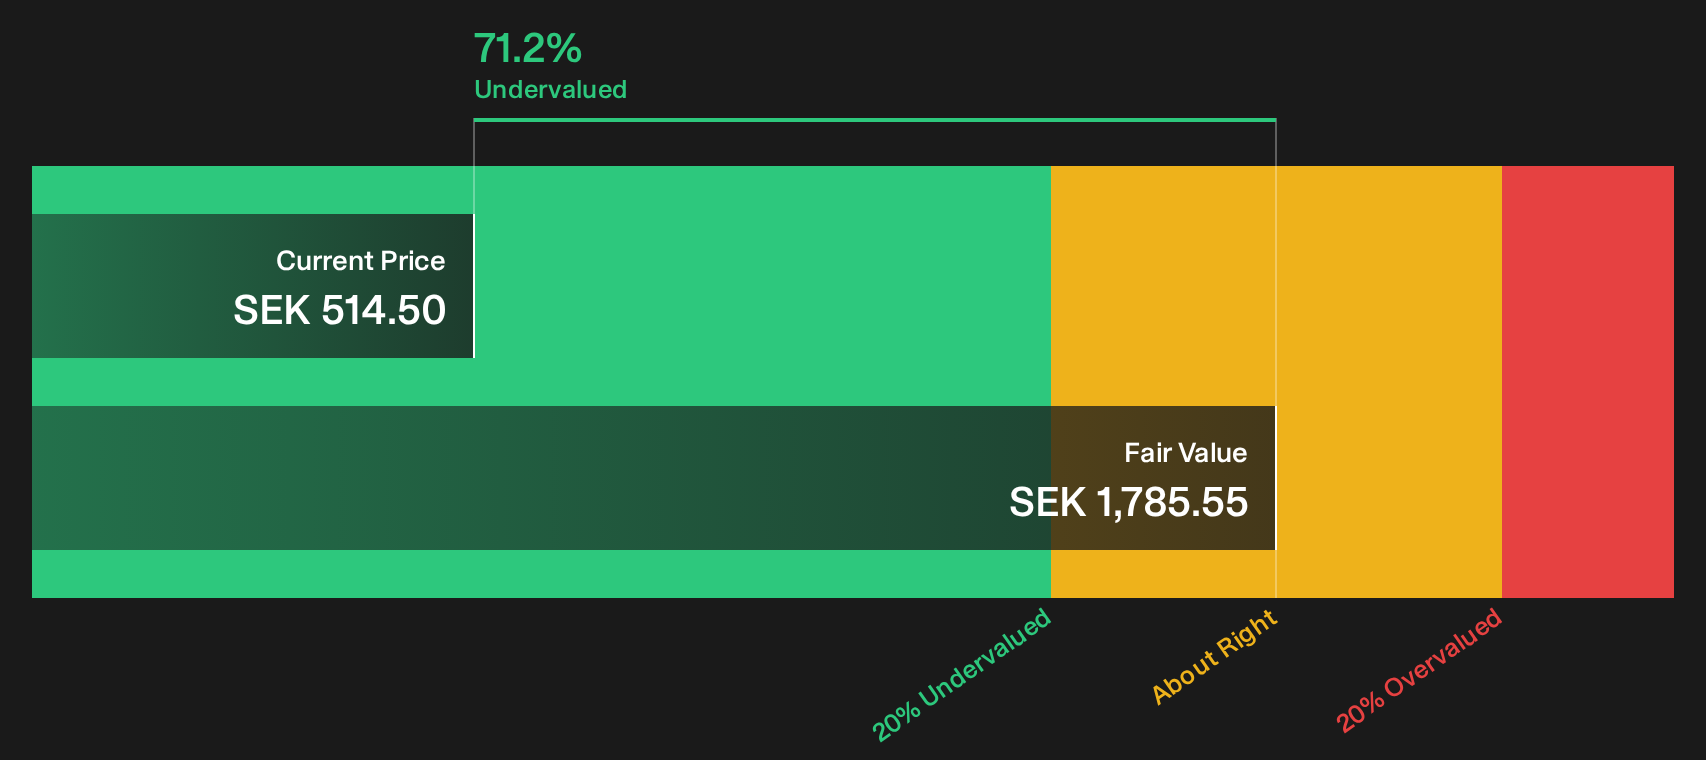
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AB Industrivärden for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around AB Industrivärden in this piece may feel mixed, so move quickly to review the numbers, weigh the concerns alongside the potential upsides, and ground your own view with 2 key rewards and 2 important warning signs.
Looking for more AB Industrivärden style investment ideas?
If AB Industrivärden has sharpened your focus on valuation and quality, do not stop here. Put that momentum to work across a broader watchlist.
- Target robust businesses that blend value and quality by using the 196 high quality undervalued stocks built around strong cash flows and resilient balance sheets.
- Prioritise resilience first by scanning the 231 resilient stocks with low risk scores so you concentrate on companies with steadier risk profiles and fewer nasty surprises.
- Hunt for future outperformance by reviewing the 613 high quality undiscovered gems before other investors start paying attention to the same set of under-followed opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com