
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Q2 Holdings (QTWO) Fairly Valued Following Its Recent Share Price Rebound?
Q2 Holdings (QTWO) drew attention after its recent share-price move, with the stock closing at US$61.93 on 13 October 2026. Investors are weighing that price against the company’s current fundamentals.
Recent trading has been choppy for Q2 Holdings, with a 4.61% 7 day share price return and a 12.31% 90 day share price gain. However, the year to date share price return is still down 10.80%, while the 3 year total shareholder return of 100.88% points to strong longer term momentum.
Spot opportunities around Q2 Holdings by reviewing a curated group of list of solid balance sheet and fundamentals (25 results).After a quick rebound yet a year to date decline, Q2 Holdings now sits in an awkward middle ground. Is this a moment to step in, or a setup to wait for a cheaper entry as the valuation picture comes into focus?
Most Popular Narrative: 17% Undervalued
Analysts following Q2 Holdings see more value than the current $61.93 price suggests, with their narrative focusing on earnings and cash flow potential discounted at 8.91%.
The increasing focus by financial institutions on digital transformation, evidenced by engagement and expanded investments in mission-critical digital banking, fraud prevention, and AI solutions, is described as a potential driver of subscription revenue and retention for Q2 over the longer term.
Higher demand for integrated, omni-channel, and mobile-first banking experiences is cited as accelerating adoption of Q2's unified platform across both new and existing customers, which in turn is presented as expanding the addressable market and supporting higher average revenue per user (ARPU) and overall revenue.
See why 12 investors see Q2 Holdings as 17% undervalued.
Result: Fair Value of $74.25 (UNDERVALUED)
Still, the story around Q2 Holdings can change quickly if bank consolidation drives higher customer churn or if growing competition in fraud and risk tools reduces pricing power.
Find out about the key risks to this Q2 Holdings narrative.
Another View: How Q2 Holdings Looks On Earnings Multiples
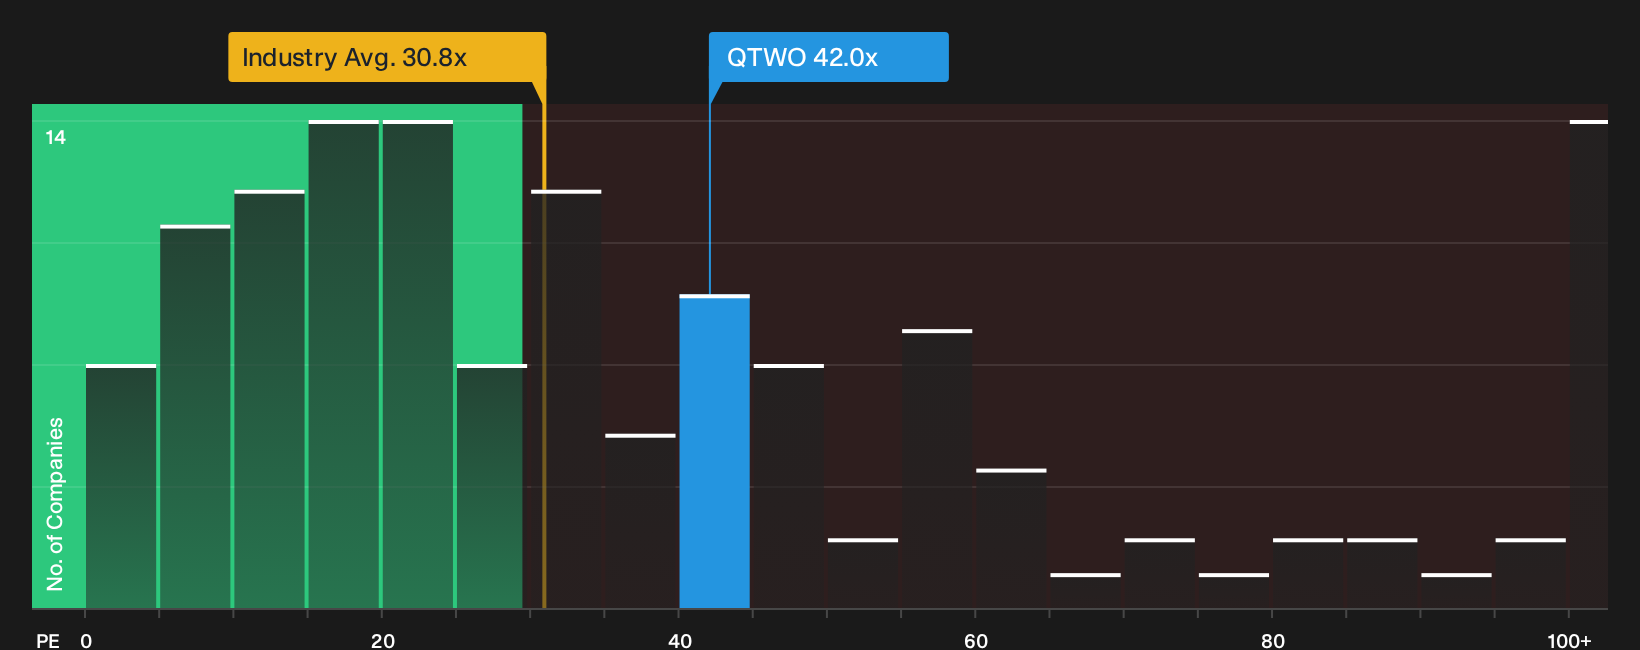
While the fair value of Q2 Holdings at $74.25 suggests upside based on analysts' cash flow and earnings assumptions, the current P/E of 42x tells a tighter story. It is richer than the US Software industry on 30.8x, yet cheaper than peer averages at 71.1x.
The fair ratio for Q2 Holdings sits at 30.8x, well below the current 42x level. That gap points to valuation risk if sentiment cools, even if the analyst narrative argues the stock is 17% undervalued. Which yardstick do you trust more when real money is on the line?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Q2 Holdings feels familiar, consider acting while the data is fresh and test the thesis yourself by reviewing the 4 key rewards.
Looking for more investment ideas beyond Q2 Holdings?
You have momentum on Q2 Holdings already. Do not stop there. Use the Simply Wall St Screener to quickly surface other opportunities that fit your style.
- Start hunting for potential upside where quality meets a marked discount by checking the 33 high quality undervalued stocks.
- Prioritise staying power and sleep-at-night resilience by reviewing a 32 resilient stocks with low risk scores that keeps blowups off your radar.
- Target under the radar opportunities with strong fundamentals before they gain broad attention by using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com