
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Banco di Desio e Della Brianza (BIT:BDB) Pullback Puts Premium Valuation Under Fresh Scrutiny
Recent debate around Banco di Desio e della Brianza (BIT:BDB) has focused on its premium valuation relative to Italian banking peers, as long term shareholders weigh strong historical returns against questions about earnings quality and balance sheet strength.
At a share price of €15.98, Banco di Desio e della Brianza has pulled back sharply in the short term, with the share price down 4.65% on the day and 11.62% over the past month. However, the 70.36% year to date share price return and a one-year total shareholder return of 125.26% show powerful longer term momentum that has fueled debate about whether the current premium valuation still reflects investors’ shifting view of its earnings strength and risk profile.
Spot 231 resilient stocks with low risk scores that, like Banco di Desio e della Brianza, put balance sheet resilience and earnings quality at the center of their premium valuations.Bulls see Banco di Desio e della Brianza’s recent pullback as a reset after a powerful rerating. Bears see a stretched premium under pressure. Which side do the valuation markers lean toward next?
Price-to-Earnings of 15.8x: Is it justified?
Banco di Desio e della Brianza trades on a P/E of 15.8x, which represents a clear premium to the recent share price of €15.98 compared with many banking peers.
The P/E ratio compares what investors are paying for each euro of earnings. For banks, it often reflects how the market weighs earnings quality, loan risk, and the reliability of profits across a cycle.
Here, the premium appears tied to Banco di Desio e della Brianza’s profitability track record. Earnings grew by 11.6% over the past year and have grown by 16.6% per year over the past 5 years, with current net profit margins of 23% compared with last year’s 22% and described as high quality earnings. That mix of growth and margins may help explain why the stock trades on a P/E above both the European Banks industry average of 11.7x and its peer average of 15.1x.
Even with that context, the valuation premium stands out. Banco di Desio e della Brianza’s P/E of 15.8x is lower than the broader Italian market multiple of 17.5x, yet higher than the European Banks industry at 11.7x and the peer group at 15.1x. This indicates that investors are paying extra for its specific earnings profile rather than for the sector as a whole.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.8x (OVERVALUED)
Still, that premium story for Banco di Desio e della Brianza can be challenged if earnings quality is reassessed or if Italian banking sector sentiment weakens.
Find out about the key risks to this Banco di Desio e della Brianza narrative.
Another View: Banco di Desio e della Brianza Through the SWS DCF Lens
The market pays a premium P/E for Banco di Desio e della Brianza, yet the SWS DCF model points in the opposite direction. On that cash flow view, the share price of €15.98 sits well above an estimated value of €8.49, which flags the stock as overvalued on this metric.
This kind of gap matters in practical terms. P/E focuses on current earnings strength. A DCF framework asks a different question. It tests how much cash the bank might realistically generate over time relative to today’s price. When those two stories clash this sharply, which one should guide how you allocate capital?
Look into how the SWS DCF model arrives at its fair value.
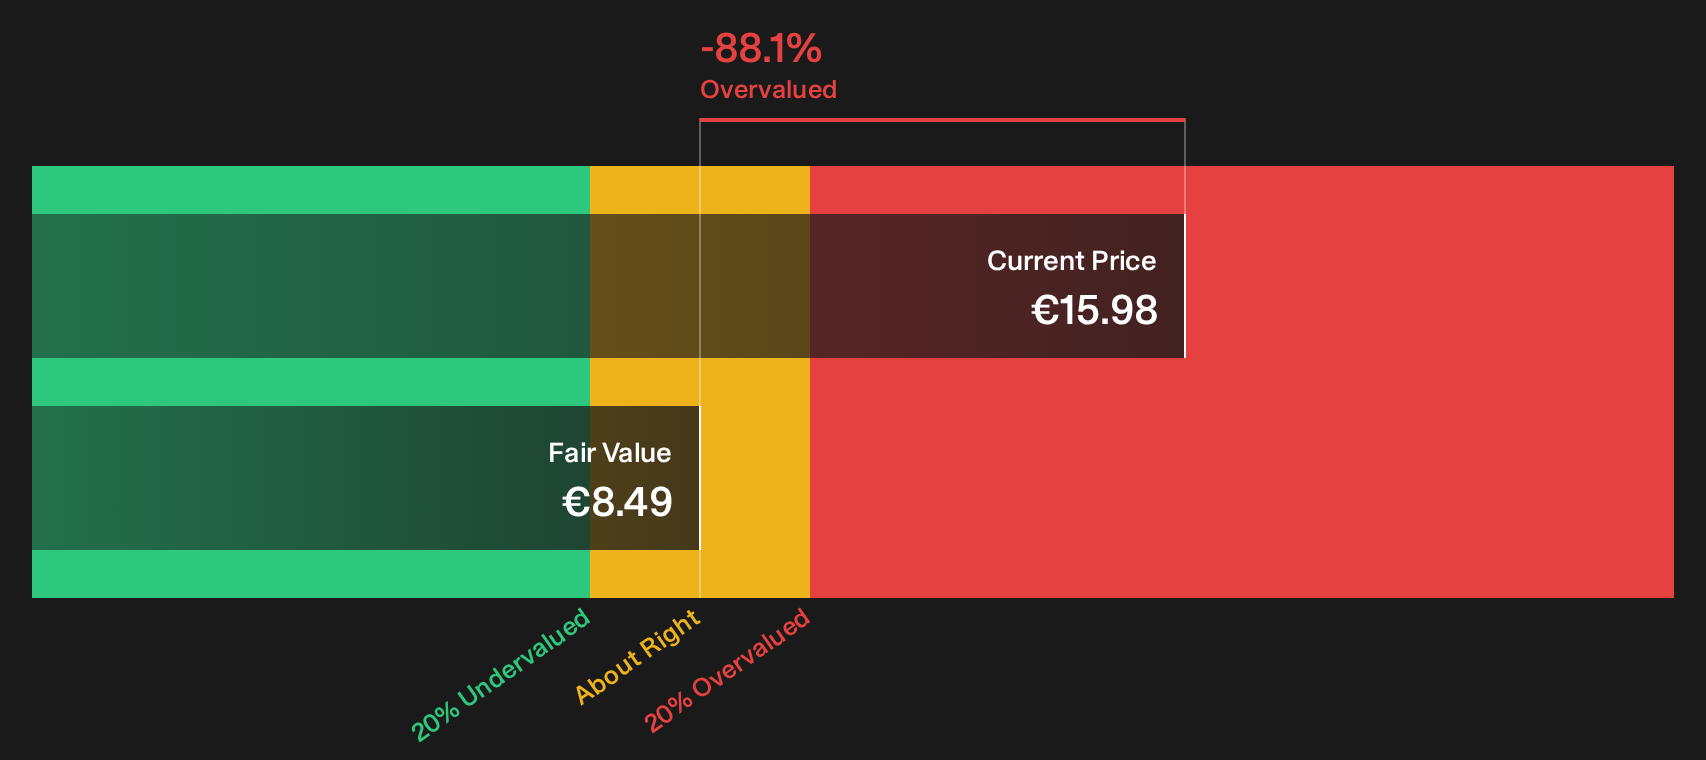
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Banco di Desio e della Brianza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Banco di Desio e della Brianza so far, right? Weigh that combination of flagged risks and identified rewards for yourself, and then round out your view with 2 key rewards and 4 important warning signs
Looking for more ideas beyond Banco di Desio e della Brianza?
If Banco di Desio e della Brianza has sharpened your focus on valuation, risk and quality, do not stop here. Broader research can reveal opportunities you might otherwise miss.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (203 results) to pair financial strength with disciplined fundamentals.
- Hunt for pricing gaps by scanning the 196 high quality undervalued stocks to combine quality metrics with a margin between business value and market price.
- Secure potential income streams by checking the 217 dividend fortresses built around higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com