
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Dedicated Mining Unit Will Impact Volvo Stock Investors
- AB Volvo has created a dedicated mining entity called Volvo Mining, which will sit within Volvo Construction Equipment and, from January 1, 2027, will coordinate global mining related trucks, construction machinery, autonomous offerings and research, initially serving customers and contractors in Sweden, Norway and Finland.
- The appointment of Per-Erik Lindström as Head of Volvo Mining signals a focused push to align leadership, capital and product decisions around mining customers as a distinct end market, rather than treating it as a side segment within existing divisions.
- Attention now shifts to how AB Volvo's investment narrative could be reshaped by the Volvo Mining unit's integrated truck and equipment focus.
AB Volvo Investment Narrative Recap
To own AB Volvo, you need to be comfortable with a cyclical heavy equipment group that is trying to build more stable earnings through services, decarbonisation technologies and autonomous solutions. The Volvo Mining launch does not change the near term picture that much. The key nearer term swing factor still looks like truck and construction volumes in major regions.
The biggest operational risk remains exposure to weak demand in North and South America, combined with under absorption if production cuts persist. Capital tied up in multiple drivetrains and autonomous projects also needs to earn its keep. Volvo Mining concentrates some of that effort in one vertical, which could sharpen execution but also increases mining specific execution risk.
The creation of Volvo Mining is most connected to AB Volvo’s autonomous transport ambitions. Management has outlined plans for driverless operations on U.S. highways from 2027 and a target of more than 300 autonomous trucks and about US$3b in autonomous revenue within five years. A mining focused unit gives those projects a defined industrial use case.
Mining routes are typically repeatable, controlled and well suited to automation, which can help AB Volvo commercialise autonomous platforms and related services faster than in mixed traffic logistics. For you as an investor, the relevant question is execution: can the group integrate trucks, construction equipment and autonomy in mining sites cleanly enough to build a durable, higher margin service stream without overextending balance sheet and R&D commitments?
AB Volvo's current analyst narrative points to revenues of SEK 588.6b and earnings of SEK 57.4b by 2029. That profile rests on 7.7% yearly revenue growth and an earnings increase of SEK 21.6b from SEK 35.8b today.
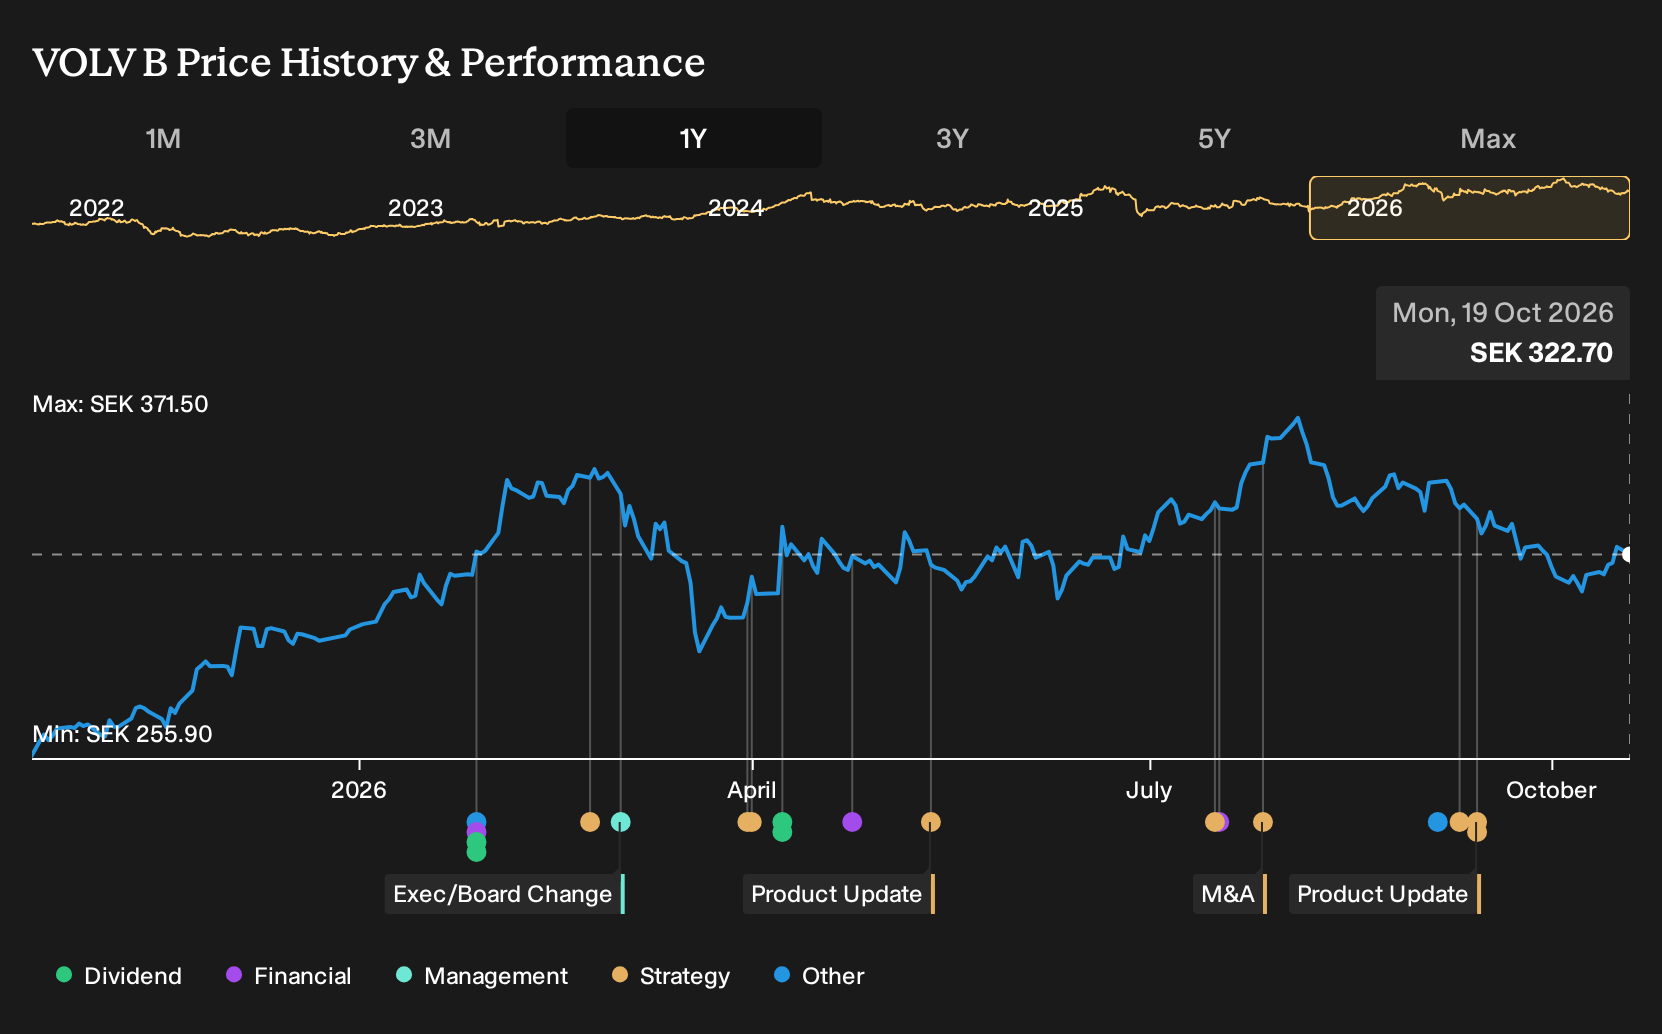
Discover how AB Volvo's fair value indicates a 10% potential upside to its current price, a discount that could narrow quickly once sentiment shifts.
Exploring Other Perspectives
One alternate view focuses on weak demand risk. The most cautious analysts expect Volvo revenue of about SEK 528.8b and earnings of SEK 47.8b by 2029, well below the baseline path. That more pessimistic stance could shift after the Volvo Mining launch, so treat it as one scenario and compare it with others.
Explore 3 other AB Volvo fair value estimates, including one that suggests it could be worth just SEK355.12.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AB Volvo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AB Volvo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AB Volvo's overall financial health at a glance.
Looking For More Ideas Beyond AB Volvo?
If the Volvo Mining story has sharpened your view on AB Volvo, it can help to compare that thesis with other businesses that fit different risk and return profiles. The Simply Wall St Screener lets you move quickly from a single stock to a wider watchlist that matches your own filters on quality, balance sheet strength and income potential.
- For investors hunting for mispriced quality, scan a focused set of undervalued opportunities through 194 high quality undervalued stocks that pair solid finances with more appealing valuations.
- If capital preservation comes first, filter for steadier performers by reviewing a curated 231 resilient stocks with low risk scores that aims to keep balance sheets and risk scores front and centre.
- Those looking to widen the research funnel can broaden their radar with a 613 high quality undiscovered gems that surfaces companies with strong fundamentals that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com