
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Sanmina (SANM) Undervalued As Its Share Price Pullback Raises Fresh Questions?
Sanmina (SANM) has pulled back recently, with the share price down 7% over the past week, 12% over the past month, and 20% over the past 3 months, prompting fresh attention from investors.
While Sanmina’s share price has dropped sharply in recent weeks, with momentum clearly fading in the short term, the stock still carries a 1-year total shareholder return of 32.41% and a 5-year total shareholder return of 352.29%. This indicates how strong the longer term ride has been despite the latest pullback.
Compare this pullback in Sanmina with other high quality tech manufacturers by scanning a curated list of resilient balance-sheet plays using the list of solid balance sheet and fundamentals (25 results).
Sanmina now trades well below the average analyst price target, even as its share price has just fallen sharply. Is that discount signalling opportunity, or is the market applying justified caution about what comes next for this manufacturer?
Most Popular Narrative: 32% Undervalued
Sanmina’s most followed narrative pegs fair value at $260, compared with the last close at $175.67. This comparison puts the recent share price slide into a very different light.
Sanmina is expanding vertical integration in areas such as metal fabrication for AI racks, high technology PCBs, transformers and liquid cooling and test capabilities. This is intended to capture a larger share of each AI and cloud rack build and support higher gross margin and operating margin over time.
See why 19 investors see Sanmina as 32% undervalued.
Result: Fair Value of $260 (UNDERVALUED)
Still, the Sanmina story can break if AI rack demand cools in the face of rising inventory and capital expenditures, or if governance concerns resurface after the whistleblower settlement.
Find out about the key risks to this Sanmina narrative.
Another Angle On Sanmina’s Valuation
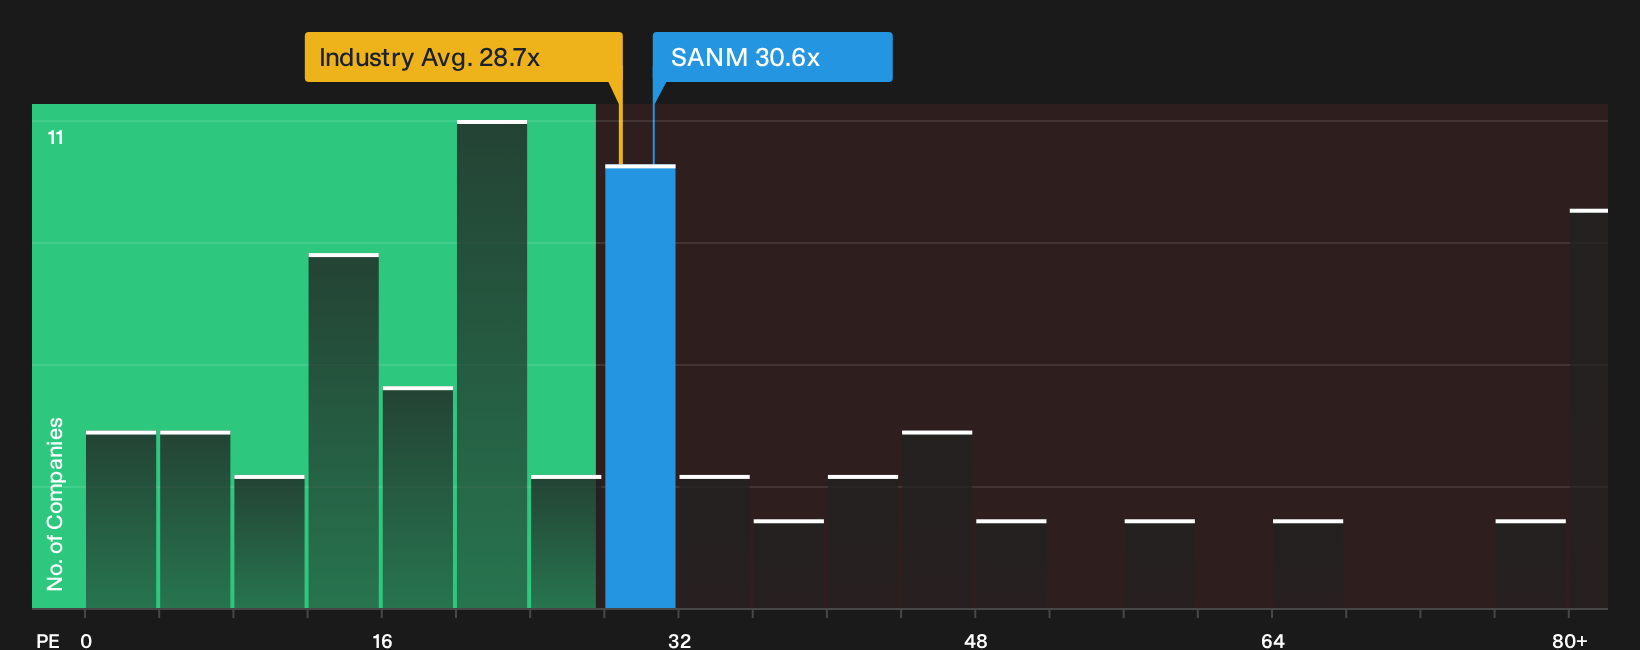
Analyst targets and the popular $260 fair value lean on growth forecasts and sentiment. The market’s own yardstick, the P/E ratio, tells a different story. Sanmina trades on 30.6x earnings, richer than the US Electronic industry at 28.7x but below its 32.6x peer average and a fair ratio estimate of 42.7x. Is that a safety margin or a warning that expectations are already packed in?
To see how this earnings multiple compares with what the numbers imply over time, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Sanmina so far. If you want a clear view rather than inheriting someone else’s narrative, weigh both sides of the story through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sanmina?
If Sanmina has your attention, do not stop here. Use focused screens to uncover other potential opportunities that match your risk tolerance and investing style.
- Target resilient cash generators by scanning a 8 dividend fortresses that prioritise income without ignoring balance sheet strength.
- Hunt for mispriced opportunities by reviewing a 33 high quality undervalued stocks that combines quality fundamentals with appealing valuations.
- Reduce portfolio stress by filtering for a 32 resilient stocks with low risk scores that highlights businesses with steadier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com