
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Consumer Lender Stocks Facing Higher Rates as Fed Inflation Risks Grow
Fed officials now see the AI boom as an inflation risk, which keeps extra pressure on interest-rate-sensitive areas like subprime and near-prime consumer lenders. That is where things can get uncomfortable for borrowers and potentially interesting for you. In this piece you will see three stocks exposed to this macro story, all from the same screener, and how the current backdrop could either reward patience or punish complacency.
The three lenders covered below are just a sample set, and the full screen surfaced 18 more U.S. subprime and near prime consumer finance stocks with equally compelling narratives that are not discussed in this article. If you want to identify which of these issuers best fits your risk tolerance and rate view, go straight to the U.S. Subprime & Near‑Prime Consumer Lenders screener to filter and analyze the broader opportunity set.
Atlanticus Holdings (ATLC)
Overview: Atlanticus Holdings is a financial technology company that provides non prime focused credit cards, point of sale financing, and auto related lending solutions to U.S. consumers.
Operations: Atlanticus generates about US$694 million from Credit as a Service and US$36 million from Auto Finance, with all US$730 million earned in the United States.
Market Cap: US$1.40b
Atlanticus Holdings matters in this screener because it gives you direct exposure to near prime and underserved borrowers through credit cards and point of sale finance, in areas where higher rates and shifting consumer budgets can quickly reshape returns.
"The acquisition and integration of Mercury Financial has roughly doubled the balance sheet to about US$7b and brought a US$3b portfolio under Atlanticus portfolio management methods."
What happens to margins and earnings from here largely depends on how one less visible cost pressure evolves relative to those larger balances.
That hidden cost pressure is exactly where the full narrative for Atlanticus Holdings shows whether Atlanticus Holdings is quietly compounding value or simply increasing its balance sheet risk.

World Acceptance (WRLD)
Overview: World Acceptance offers short and medium term consumer installment loans and related services to U.S. borrowers who struggle to access traditional credit.
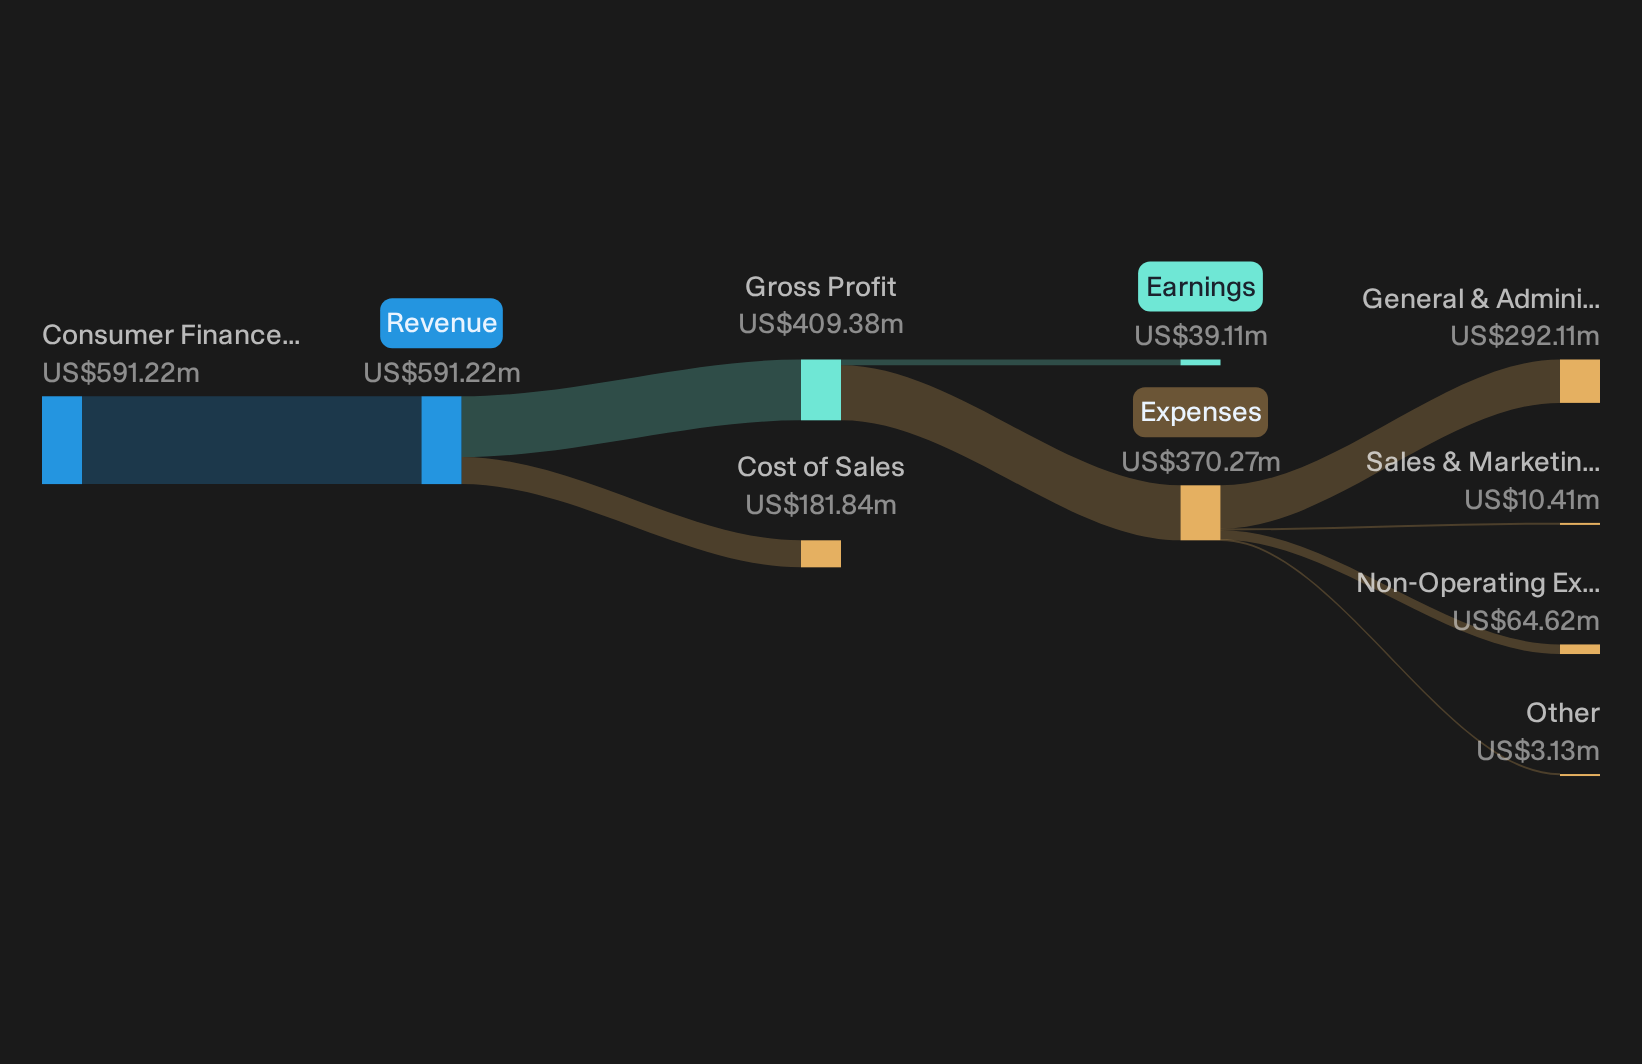
Operations: World Acceptance generates about US$591 million from consumer finance activities, with all revenue coming from customers in the United States.
Market Cap: US$776 million
World Acceptance sits close to the screener theme because it directly prices credit for subprime and near prime borrowers. As a result, every move in rates, charge offs, or funding costs can quickly show up in its earnings power.
"The stated intention to rely less on new customers after a period when new customer originations rose about 40% year over year and the new customer portfolio increased 35%, in favor of higher quality repeat and returning former borrowers whose first payment defaults have tracked pre COVID cohorts, can shift World Acceptance toward a more stable book that supports net interest income and credit costs."
What happens if a single cost of capital assumption moves against that plan will likely decide where margins and growth settle.
That hinges on whether those assumptions quietly compress returns or open the door to a cleaner, faster compounding book. Read the full narrative for World Acceptance to see how that trade off could be accelerating.
Oportun Financial (OPRT)
Overview: Oportun Financial focuses on personal loans and credit cards for underbanked and near prime borrowers who rely heavily on consumer credit.
Operations: Oportun Financial generates about US$744 million from consumer financial services, tying its entire revenue base to borrower credit health.
Market Cap: US$418 million
For this screener, Oportun Financial sits right in the crosshairs, because every shift in credit conditions or borrowing costs hits its underbanked customers directly.
"Oportun's focus on leveraging advanced data analytics (for example, expanded use of Plaid's bank transaction data for underwriting and integration of AI in decisioning) is driving improved credit outcomes and lower loss rates."
What happens if a single funding cost assumption moves against those cleaner credit outcomes will likely decide where its margins settle.
If that funding swing is what you care about, read the full narrative for Oportun Financial to see how Oportun Financial’s risk, pricing and upside could be decoupling.

Seeking Alternatives Before Momentum Flies Past
Fresh themes often break out quietly, then move fast once the crowd catches on. Scan these curated ideas while they are still under the radar for now.
- Review a curated mix of mature businesses in the 8 dividend fortresses to evaluate potential income streams from dividend-paying companies.
- Explore early movers in cutting edge computing by running through the carefully filtered 25 quantum computing stocks while these opportunities may still be considered niche.
- Track supply chain trends by scanning miners and producers in the focused 17 top copper producer stocks to see how changing demand could be reflected in this segment of the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com