
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Murphy USA (MUSA) Tests Its Fuel Margin Story On An Undervalued View
Murphy USA (MUSA) has drawn fresh attention after its recent share price move, with the stock closing at $547.67. Investors are weighing that level in relation to the retailer’s fuel-focused business and earnings profile.
Recent trading tells a mixed story. The 7 day share price return of 4.22% and year to date gain of 35.12% suggest momentum has picked up again, even though the 90 day share price performance declined 10.38% from earlier levels.
Scan beyond Murphy USA and size up fuel retail peers with a similar earnings profile using our hand-picked screener of list of solid balance sheet and fundamentals (25 results).
Murphy USA now sits at a crossroads. Is the recent climb a clean read on the fuel retailer’s earnings power, or just a swing in sentiment that the valuation has run ahead of?
Most Popular Narrative: 11% Undervalued
Murphy USA’s most followed valuation story pegs fair value at $617.80, above the latest close at $547.67. This puts today’s price against a richer earnings backdrop built on fuel margins, nicotine categories and loyalty economics.
Structurally higher all in fuel margins, supported by guidance of about $0.35 per gallon for the back half of 2026 and evidence of rational pricing and higher breakeven levels for marginal retailers, could keep Murphy USA’s gross profit and net margins above prior cycles. Consistent contribution from the integrated fuel supply chain, with controllable economics in the range of $0.02 to $0.03 per gallon and leverage to periods of tight physical supply and price volatility, creates an additional earnings stream that can support overall margin resilience.
See why 12 investors see Murphy USA as 11% undervalued.
Result: Fair Value of $617.80 (UNDERVALUED)
Still, this bullish Murphy USA story can be knocked off course if fuel margins retreat from the guided levels or if insider selling pressures the P/E multiple.
Find out about the key risks to this Murphy USA narrative.
Another View On Murphy USA’s Valuation
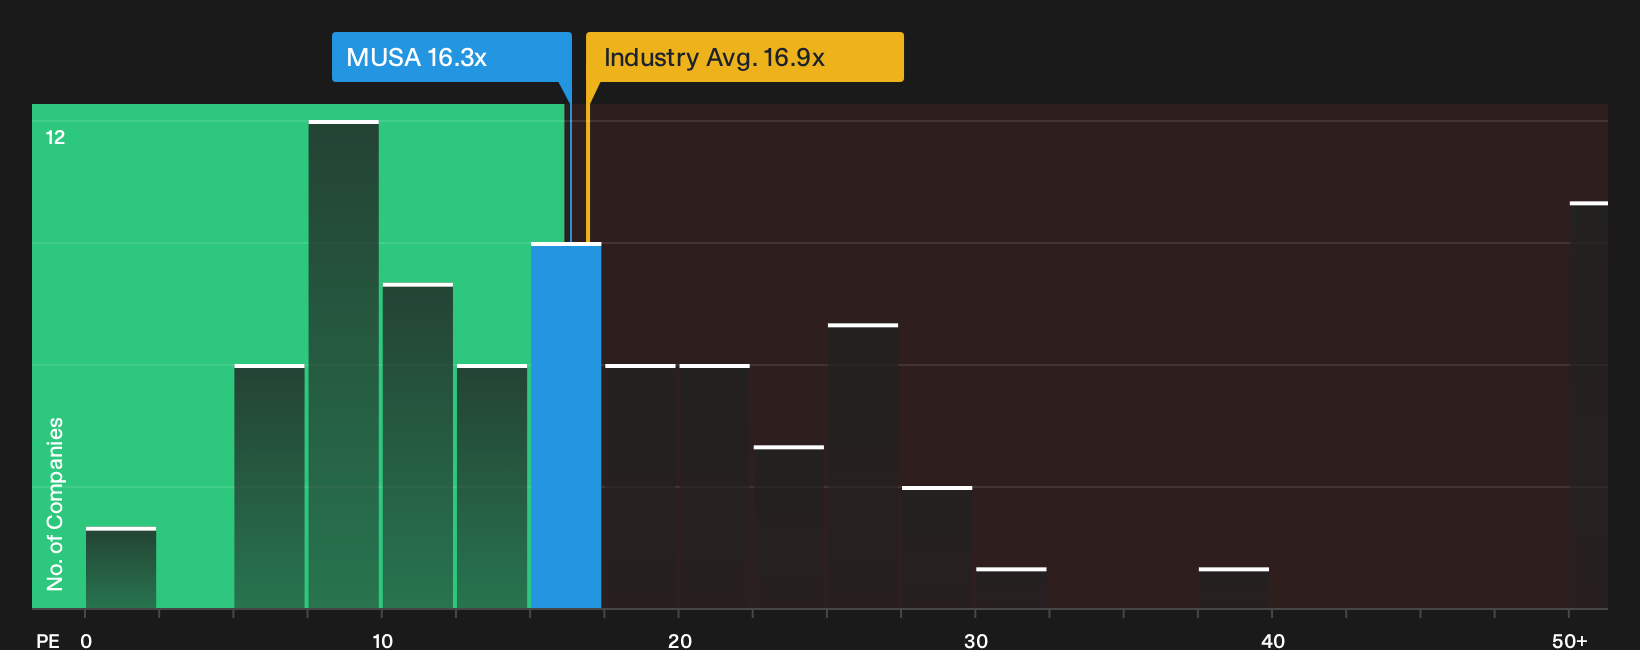
The DCF narrative paints Murphy USA as undervalued, yet the P/E picture is less forgiving. The current P/E of 16.3x sits only slightly below the US Specialty Retail industry at 16.9x, above peer average at 14.3x, and well above a fair ratio of 12x. That gap points to valuation risk if sentiment cools.
For a closer look at how this earnings based yardstick could evolve over time, review the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy USA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message, either way, Murphy USA gives you enough information to pressure test the story yourself and move quickly. Start by weighing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Murphy USA?
Do not stop your research with a single stock. Broader opportunity hunting across different styles of businesses can sharpen your next move and widen your edge.
Use the Simply Wall St Screener to compare other ideas before the market does.
- Target potential mispricings by scanning a curated set of undervalued opportunities with strong fundamentals using the 33 high quality undervalued stocks.
- Prioritise resilience by focusing on companies that pair sturdy finances with lower risk scores through the 32 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems before they are widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com